

Maximus Is Paid by the Case, and 21 Million Medicaid Redeterminations Start in January
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
One industry heading holds a company whose earnings multiple has halved and another that has more than doubled on data-center construction, and the label explains neither.
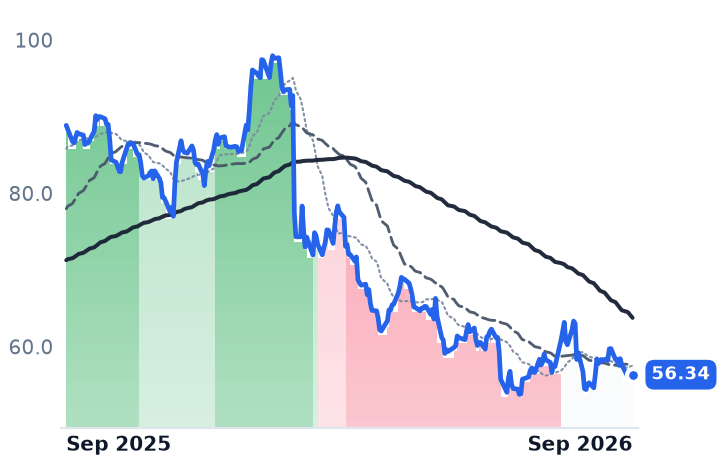
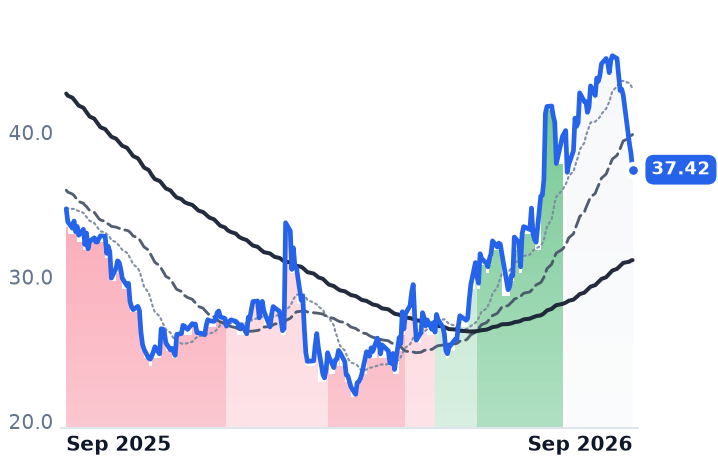
Maximus, which administers government health programs, has reported falling revenue for three straight quarters and cut fiscal 2026 adjusted earnings guidance to $7.90–8.20 after the Department of Veterans Affairs paused performance incentives worth roughly $0.35 a quarter. Consensus earnings per share still rise this year, yet the shares change hands near 8.3 times trailing earnings against roughly 16.4 times a year ago.
The de-rating is not idiosyncratic — Booz Allen and Leidos fell with it while defense-weighted CACI and SAIC rose. What the multiple prices is permanence, and a Medicaid caseload fixed in law arrives on 1 January.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
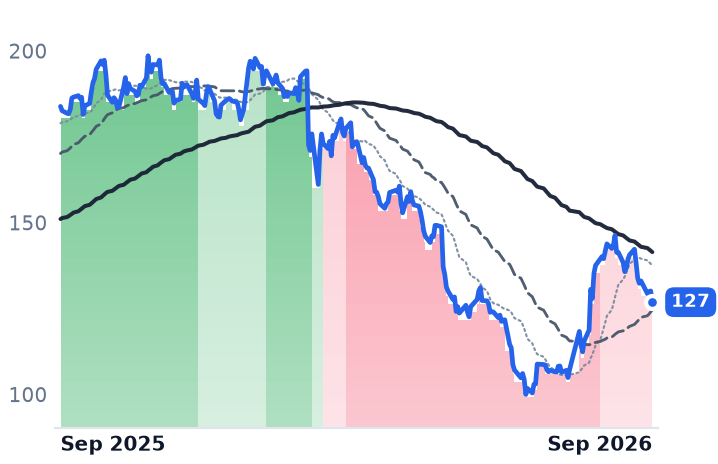
MMS | Maximus | Government & Workforce Services | ⚠️ Emerging Bear | +3.6% | −36.6% |
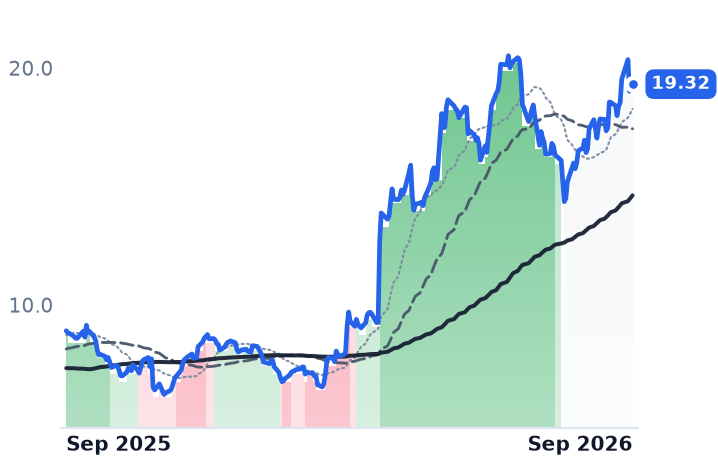
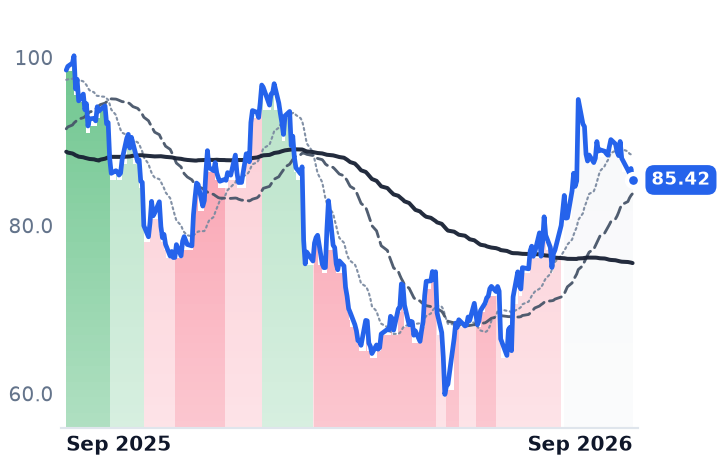
TH | Target Hospitality | Government & Workforce Services | 🟢 Cont. Bull | +17.6% | +116.8% |
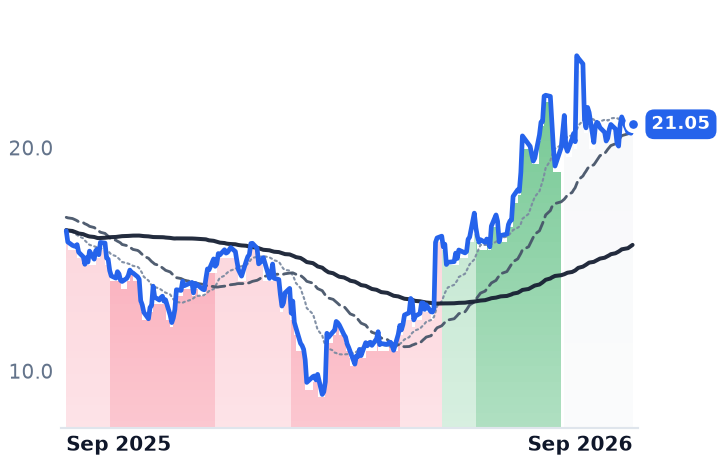
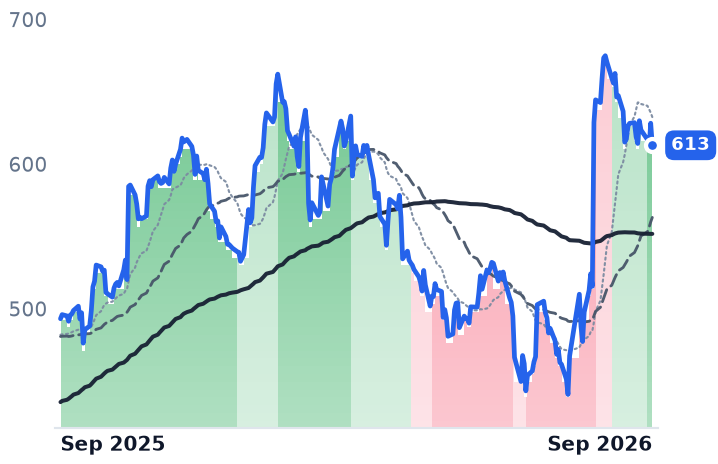
FA | First Advantage | Government & Workforce Services | 🌱 Emerging Bull | +0.8% | +29.3% |
| Compared against · context, not the story | |||||
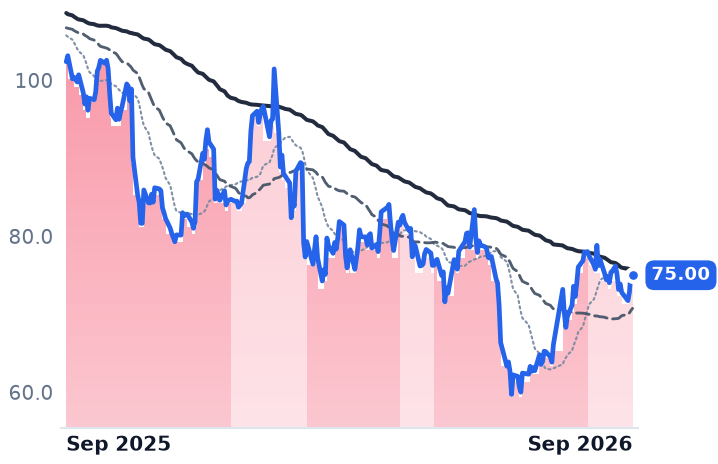
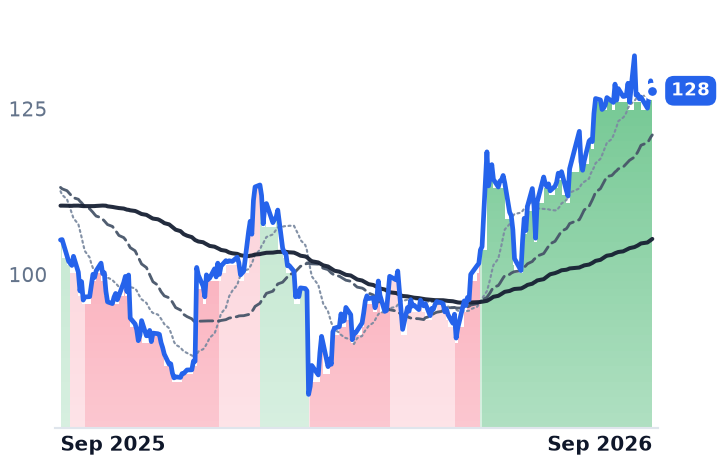
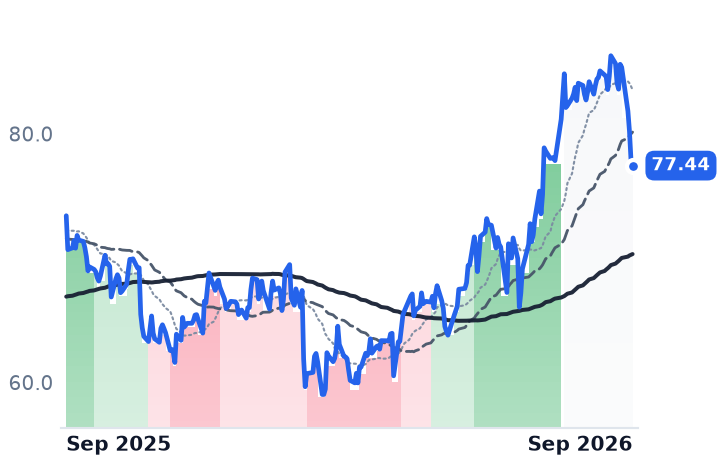
BAH | Booz Allen Hamilton | Government & Defense Consulting | 🔴 Cont. Bear | −3.8% | −26.7% |
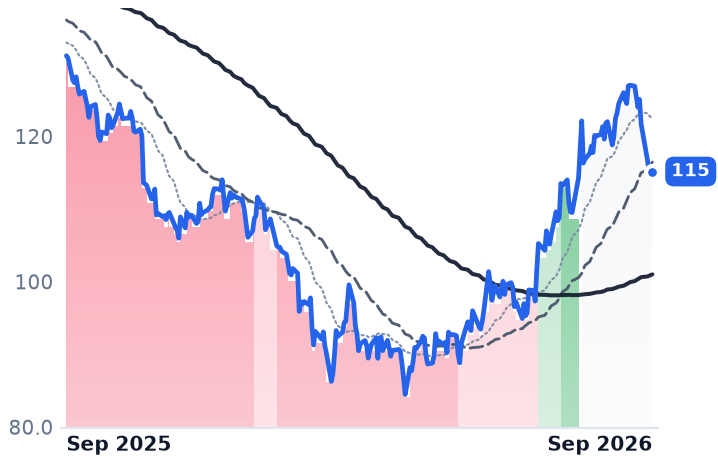
LDOS | Leidos | Defense & Government Solutions | ⚠️ Emerging Bear | −9.1% | −31.0% |
ICFI | ICF International | Government & Defense Consulting | 🔴 Cont. Bear | −3.5% | −13.3% |
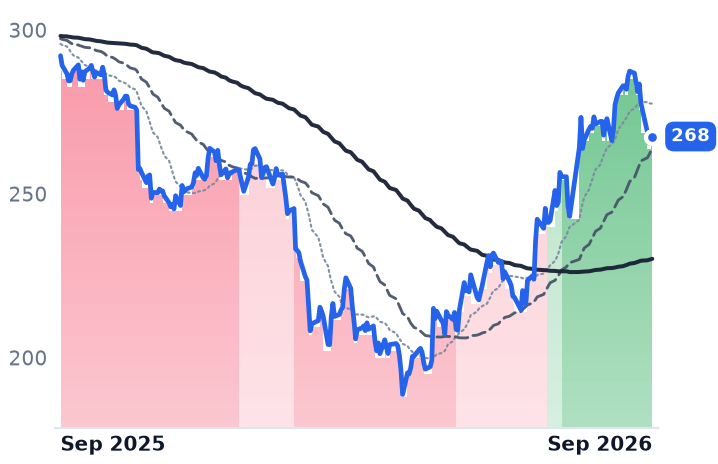
CACI | CACI International | Defense & Government Solutions | ⚠️ Emerging Bear | −9.0% | +24.3% |
SAIC | Science Applications International | Defense & Government Solutions | 🌱 Emerging Bull | +2.1% | +21.4% |
RHI | Robert Half | Staffing & Recruitment | 🌱 Emerging Bull | −9.6% | +7.8% |
KFY | Korn Ferry | Executive Search & Consulting | 🌱 Emerging Bull | −6.4% | +5.5% |
ADP | Automatic Data Processing | HCM Software & Payroll | 🌱 Emerging Bull | −0.2% | −8.4% |
PAYX | Paychex | HCM Software & Payroll | 🌱 Emerging Bull | −3.7% | −12.2% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.9% | +16.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MMS | $3.0B | 8.3x | 7.1x | 0.6x | 0.6x | 2.3x | 2.3x | 6.4x | 14.5% |
TH | $1.9B | n/m | — | 5.5x | 4.4x | 75.0x | 59.7x | 60.4x | 4.7% |
FA | $3.6B | 142.8x | 16.5x | 2.2x | 2.1x | 6.0x | 5.8x | 12.7x | 6.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BAH | $9.5B | 12.3x | 12.3x | 0.9x | 0.8x | 1.9x | 1.9x | 10.4x | 11.8% |
LDOS | $16.8B | 12.4x | 10.8x | 1.0x | 0.9x | 5.5x | 5.3x | 9.9x | 12.9% |
ICFI | $1.1B | 13.1x | 8.7x | 0.6x | 0.6x | 1.7x | 1.6x | 8.5x | 13.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CACI | $13.6B | 25.3x | 18.7x | 1.4x | 1.3x | 6.6x | 5.8x | 17.1x | 9.4% |
SAIC | $5.4B | 14.7x | 11.9x | 0.7x | 0.7x | 5.7x | 5.8x | 7.8x | 11.5% |
RHI | $4.0B | 34.1x | 30.9x | 0.8x | 0.8x | 2.1x | 2.1x | 26.3x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KFY | $3.3B | 12.3x | 11.1x | 1.1x | 1.1x | 1.3x | 1.3x | 6.0x | 8.7% |
ADP | $113.3B | 25.8x | 23.1x | 5.2x | 4.9x | 10.7x | 10.1x | 18.0x | 4.4% |
PAYX | $45.2B | 25.9x | 21.3x | 6.9x | 6.6x | 9.3x | 8.9x | 16.1x | 5.1% |
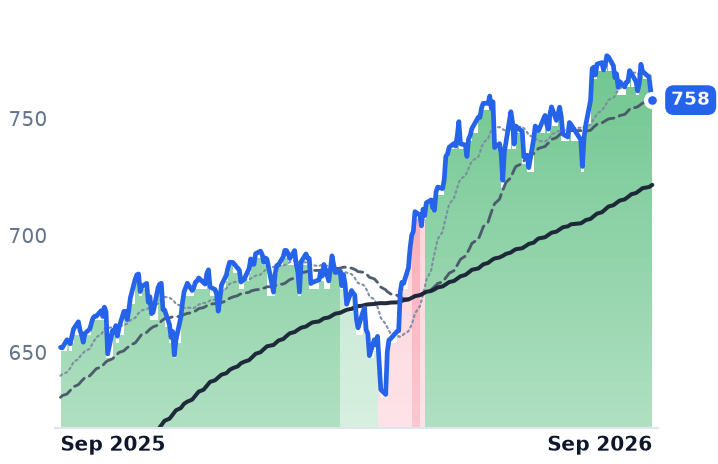
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MMS | Revenue | −4.2% | +2.9% | +8.5% |
| EPS | +7.5% | +4.4% | +12.3% | |
TH | Revenue | +37.6% | +67.7% | +11.7% |
| EPS | −86.6% | −2065.4% | +33.5% | |
FA | Revenue | +10.3% | +6.6% | +8.2% |
| EPS | +26.9% | +18.0% | +17.0% | |
BAH | Revenue | −6.1% | +0.7% | +4.2% |
| EPS | −4.3% | +5.1% | +5.1% | |
LDOS | Revenue | +5.2% | +6.1% | +4.7% |
| EPS | +17.1% | +4.6% | +3.2% | |
ICFI | Revenue | +2.0% | +5.4% | +8.7% |
| EPS | +3.7% | +9.4% | +7.0% | |
CACI | Revenue | +10.9% | +12.7% | +6.7% |
| EPS | +14.2% | +16.7% | +15.4% | |
SAIC | Revenue | −2.4% | +0.0% | +1.1% |
| EPS | +15.3% | +6.0% | +5.8% | |
RHI | Revenue | −1.0% | +4.1% | +5.2% |
| EPS | −4.5% | +55.5% | +26.1% | |
KFY | Revenue | +6.7% | +3.3% | +5.0% |
| EPS | +9.6% | +8.2% | +10.7% | |
ADP | Revenue | +7.0% | +5.9% | +5.7% |
| EPS | +11.0% | +10.7% | +9.2% | |
PAYX | Revenue | +16.5% | +5.5% | +5.5% |
| EPS | +10.1% | +8.6% | +7.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Maximus runs the eligibility files and phone lines behind American public health programs — Medicaid and Affordable Care Act marketplace enrollment, multilingual contact centers for government health and human-services agencies, independent medical reviews and appeals — and it has now reported three consecutive quarters of shrinking revenue. Analysts still expect its earnings per share to rise this year.
The shares have lost more than a third of their value over twelve months, and profits did almost none of that work. A year ago the company was worth about 16.4 times the earnings it went on to report for fiscal 2025; it now trades near 8.3 times trailing earnings, with free cash flow equal to roughly 14.5% of its market value. Underneath the halved multiple is a federal civilian services market that stopped buying on schedule — and a company whose largest earner is rebid every year.
The hole in this year's earnings
The Department of Veterans Affairs paused performance incentives and disincentives on its Medical Disability Exam program effective 1 July 2026, expected to run through the end of December. Those incentives had contributed about $0.35 of earnings per share in each of the first three quarters of fiscal 2026. Maximus cut adjusted earnings guidance to $7.90–8.20 from $8.25–8.55 and left revenue guidance of $5.2–5.35bn untouched — an earnings event rather than a demand one.
"These incentives have become a bigger contribution for us in our fiscal year '26 than they have been in prior years, which is really a testament to the investments we've made into the program over the past several years that have brought us to the high level of performance across the incentive metrics," chief financial officer David Mutryn told investors on August 6.
That program is also the recompete. Maximus holds one of four positions on the follow-on veterans exam contract vehicle, with a $13.2bn ceiling, alongside Leidos subsidiary QTC Medical Services, Optumserve Health Services and Loyal Source Government Services. The regional awards carry a one-year base with a single option year, so the risk recurs annually rather than on a comfortable multi-year cycle. Chief executive Bruce Caswell said preliminary analysis of the draft performance work statement indicates it covers all six regions the company serves today.
A budget-line split, not a company one
Maximus was not singled out. Over the same twelve months Booz Allen Hamilton fell 27.8%, Leidos 31.5% and ICF International 13.6%, while defense- and intelligence-weighted CACI rose 24.3% and SAIC 20.1%. The line runs through the appropriation, not through execution quality, and Maximus is trying to cross it: it has identified a $47bn addressable market in defense and national security, with wins at the Air Force and the Transportation Security Administration.
The bear's evidence is conversion. The pipeline is $50.4bn, more than half of it federal, but year-to-date signed awards were $1.25bn — a book-to-bill near half — with another $1.35bn awarded and unsigned as long recompetes cleared protest. Management described civilian-agency opportunities delayed, rescoped or canceled, with more bridge contracts and short extensions.
What comes next is dated. The 2025 reconciliation law requires 44 states and the District of Columbia to condition Medicaid eligibility for the expansion population on work requirements from 1 January 2027, with 34 of them verifying compliance every six months at renewal. That is 21 million beneficiaries to be redetermined semiannually — the caseload Maximus is paid per case to process. A federal court rejected the challenge to the requirements on 29 July, and the company expects its U.S. Services segment back to mid-single-digit organic growth in the September quarter.
The label's other tenants
Two companies share Maximus's industry heading and share nothing else with it. Target Hospitality owns 27 temporary-accommodation communities holding roughly 15,500 beds, and has more than doubled over the year on work unrelated to any appropriation: since January it has signed over 9,000 contracted beds representing more than $1.4bn of multiyear contracts for AI data-center construction crews, including a 48-month agreement expected to exceed $750m. Its government segment — the part the shared label implies is the engine — shrank to $13m in the June quarter, with $5–7m of transitional costs booked to redeploy those assets. The business is still loss-making, at an operating margin of -8.8% in the quarter and 60.4 times trailing enterprise value to EBITDA, which is a price for 2027, when consensus has revenue at $731m.
First Advantage, which screens job applicants and bills per screen, is the read on hiring, and it is soft. Base revenue grew 6.7% in the June quarter; management attributed about half of that to episodic enterprise-wide rescreening and labor restructuring, implying underlying volume growth near 3%, and guided the fourth quarter to a neutral base contribution. It raised full-year revenue guidance to $1.67–1.71bn on pricing, attach rates and Sterling synergies, and at 16.5 times forward earnings against 26.9% expected earnings growth this year, the price is not the stretch here. US payrolls rose 162,000 in August with unemployment at 4.1%; nothing in the screening book contradicts that.
The verdict
Four percent less revenue and a $0.35 incentive hole earn a lower price for Maximus. They do not obviously earn a multiple half what it was, on a company consensus still has growing earnings every year through fiscal 2028. The market is pricing permanence — that civilian agencies keep buying less, that recompetes keep landing as bridges, and that the veterans exam work is lost rather than repriced. The January redeterminations are the first thing on the calendar capable of testing that, and they are a policy, not a forecast. Federal funding itself runs to 11 December 2026 under the latest extension.
The rebid is decided a year at a time; the caseload arrives on a date already written into law. The current price assumes neither goes Maximus's way.