

Akamai Is Spending 40% of Revenue to Replace a Delivery Line Repricing Down 6% a Year
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Akamai's revenue grew last quarter and its gross profit shrank — the clearest sign yet that its move into AI compute costs cash long before it pays. Gross profit fell 0.5% on 5.4% revenue growth, gross margin dropped to 55.8%, and the buyback is suspended to fund the buildout. The company's own quarterly filing names the cause of the shrinking legacy business: "downward pricing of contract renewals."
Cloudflare sells essentially the same edge and has declined the same spending — dollar-based net retention of 120%, network capital spending running at 7% of revenue through June against a 14-15% full-year guide. Its shares are up roughly half in six months; Akamai's have gone nowhere.
The derating at Akamai is earned by margins rather than by demand. What is not explained is Tuesday's 9.2% jump, which arrived on Cloudflare's product news.
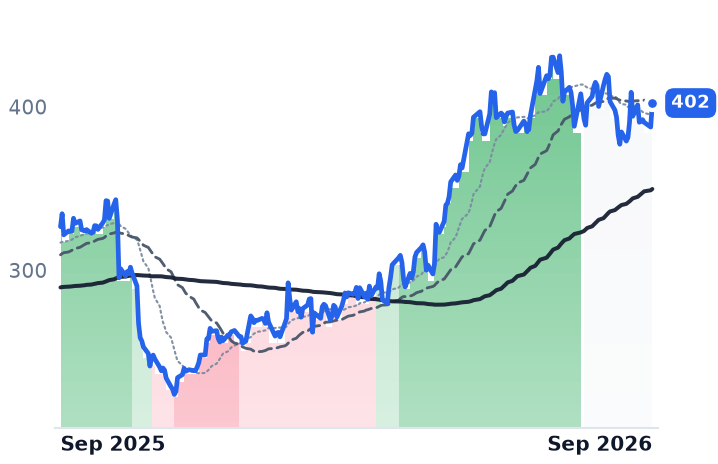
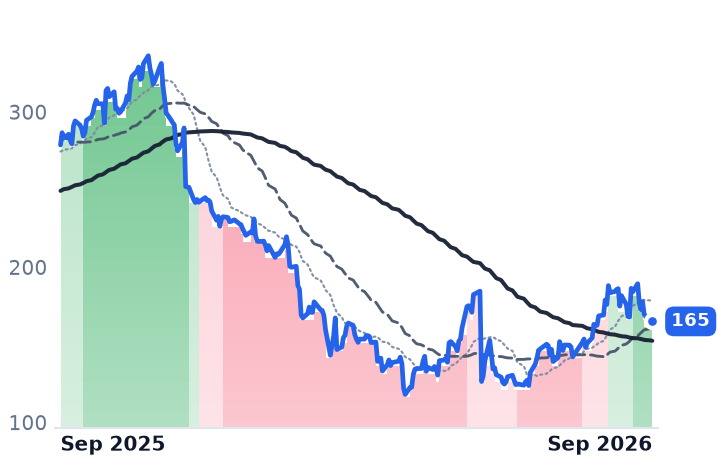
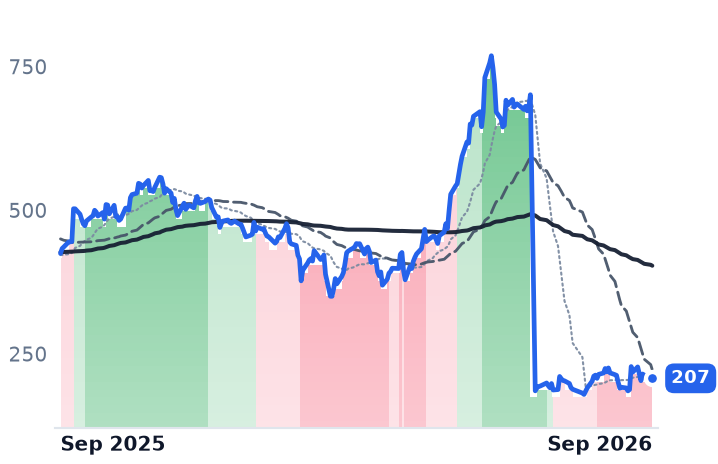
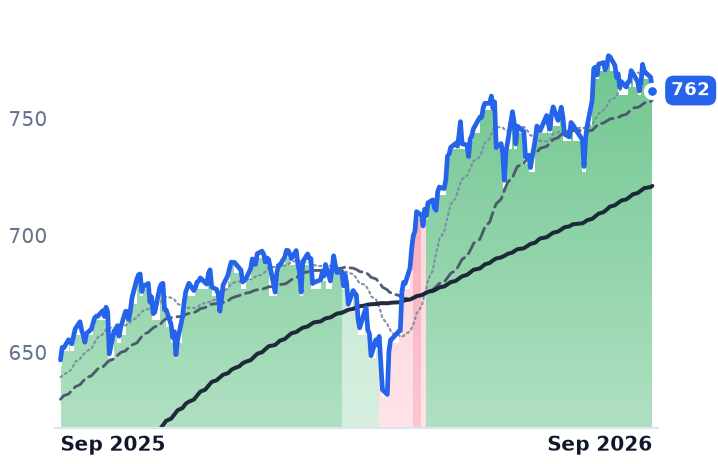
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
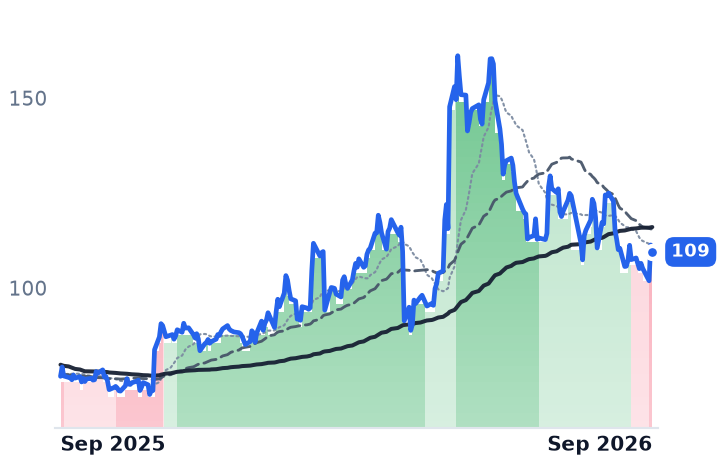
AKAM | Akamai Technologies | Network & Application Delivery | ⚠️ Emerging Bear | −6.3% | +42.7% |
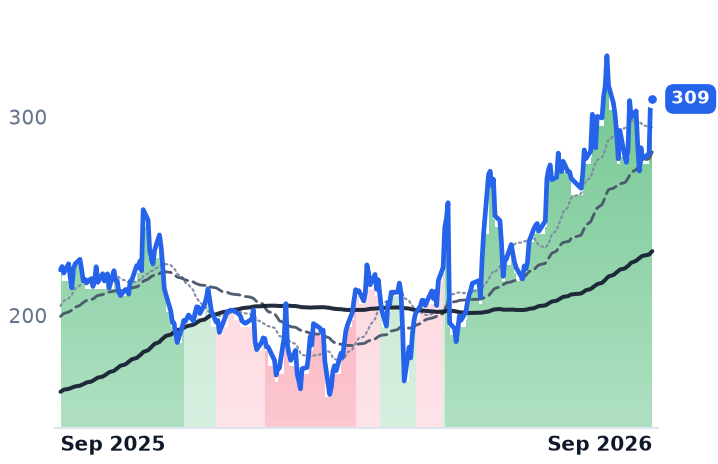
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | −0.4% | +38.6% |
| Compared against · context, not the story | |||||
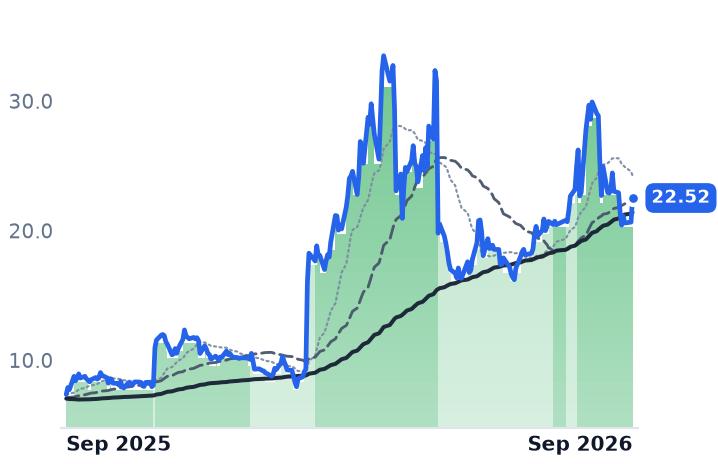
FSLY | Fastly | Cloud Infrastructure & Platform | 🟢 Cont. Bull | −21.8% | +206.0% |
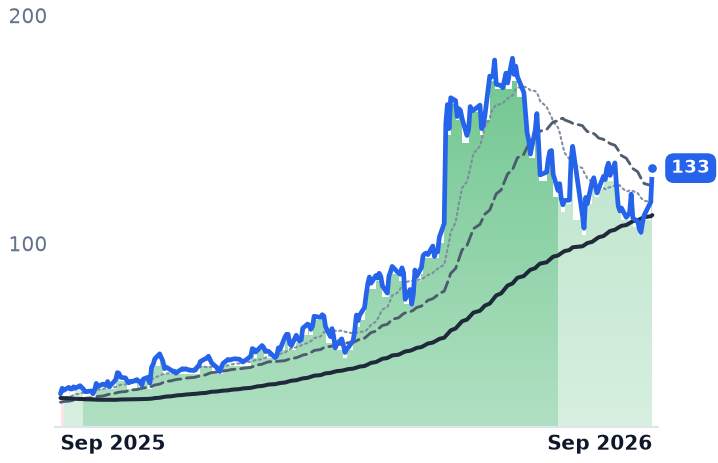
DOCN | DigitalOcean | Cloud Infrastructure & Platforms | 🟢 Cont. Bull | +3.9% | +289.3% |
FFIV | F5 | Network & Application Delivery | 🟢 Cont. Bull | −3.5% | +23.1% |
ZS | Zscaler | AI & Data Intelligence | 🔴 Cont. Bear | −7.7% | −40.8% |
CRWD | CrowdStrike | Cybersecurity & Threat Protection | 🔴 Cont. Bear | −7.6% | −51.2% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.1% | +17.8% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +3.0% | +26.2% |
ORCL | Oracle | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +11.4% | −50.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AKAM | $15.9B | 38.6x | 16.3x | 3.7x | 3.5x | 6.5x | 6.3x | 18.5x | 4.0% |
NET | $109.9B | n/m | 245.4x | 43.7x | 38.3x | 60.3x | 52.8x | — | 0.3% |
FSLY | $3.6B | n/m | 43.9x | 5.2x | 4.9x | 8.5x | 7.9x | n/m | 1.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DOCN | $13.0B | 44.1x | 76.5x | 12.9x | 11.1x | 22.5x | 19.3x | 36.7x | 0.1% |
FFIV | $21.7B | 30.3x | 22.2x | 6.6x | 6.4x | 8.0x | 7.8x | 21.1x | 4.5% |
ZS | $27.5B | n/m | 35.0x | 8.2x | 7.0x | 10.7x | 9.1x | 152.2x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRWD | $217.0B | — | 170.1x | 40.2x | 36.2x | 53.4x | 48.0x | 487.1x | 0.7% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ORCL | $433.0B | 25.3x | 18.7x | 6.4x | 4.8x | 9.8x | 7.3x | 17.4x | -5.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AKAM | Revenue | +7.2% | +13.0% | +11.2% |
| EPS | −4.6% | +6.4% | +13.9% | |
NET | Revenue | +33.7% | +28.4% | +27.1% |
| EPS | +38.0% | +32.6% | +35.1% | |
FSLY | Revenue | +20.9% | +12.0% | +11.2% |
| EPS | +897.9% | +11.2% | +17.0% | |
DOCN | Revenue | +31.2% | +53.5% | +43.7% |
| EPS | −29.0% | +23.2% | +60.4% | |
FFIV | Revenue | +10.1% | +7.4% | +7.5% |
| EPS | +12.6% | +4.0% | +11.7% | |
ZS | Revenue | +25.2% | +17.8% | +16.4% |
| EPS | +29.2% | +17.6% | +15.5% | |
CRWD | Revenue | +22.2% | +24.9% | +22.6% |
| EPS | −1.2% | +34.9% | +27.4% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
ORCL | Revenue | +17.8% | +33.2% | +45.5% |
| EPS | +25.3% | +7.6% | +35.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Akamai told investors this summer that the business which gave the company its name is shrinking because customers pay less each time a contract comes up for renewal. Its Delivery and other cloud applications segment brought in $396m in the June quarter, down 6% year on year, and the quarterly filing attributes the decline to "downward pricing of contract renewals," with media and gaming customers optimizing costs in ways that cut traffic across the network — a moderation management expects to continue through the rest of 2026. The decline is deepening: down 2% in the December quarter, then 7%, then 6%.
What replaces it is arriving, and it costs money first. Akamai — a content-delivery network that has added web-application security and an edge compute cloud sold to enterprises and carriers — has signed more than $2.8bn of multi-year cloud-infrastructure commitments this year, including a seven-year, $1.8bn contract with Anthropic disclosed on May 7 and a $600m, four-year robotics compute deal announced with second-quarter results. Capital spending hit $347m in the June quarter, 32% of revenue against 21% a year earlier, and is guided to roughly 40% of revenue for the full year. The buyback is suspended after $616m of repurchases, and the balance sheet now carries about $7.6bn of convertible debt against $4.6bn of cash and securities.
The arithmetic of a front-loaded contract
Management has been explicit about the shape of these deals: the large compute contracts carry 60-70% cash gross margins and 20-30% operating margins after depreciation, with costs incurred before revenue and target profitability reached roughly a quarter after deployment. Run that through the income statement and the result is what the June quarter showed. Revenue rose 5.4% to $1.0997bn while gross profit fell 0.5% to $613.8m, gross margin slipped to 55.8% from 59.1%, and the GAAP operating margin came in at 7.3% — a fourth consecutive quarter of compression from 15.7% last September. Revenue growth, meanwhile, has sat in a 5-7% band for four straight quarters. Security, at $604m and up 10%, is now more than half the company; cloud infrastructure grew 39% to $99m.
"Akamai continues to build momentum and gain wide industry recognition as a key infrastructure provider for the AI-driven economy," chief executive Tom Leighton told investors on August 6. The finance side supplied the cost: all existing graphics-processor capacity is sold out, requiring another $500m of investment, about $60m this year and the rest in early 2027. The revenue guide has barely moved since February — $4.4bn-$4.55bn then, $4.445bn-$4.530bn now — while the non-GAAP operating margin guide has been cut by roughly a point and a half, to 25-26%. Consensus models 2026 revenue up 7.2% and earnings per share down 4.6%, then a 13.0% revenue re-acceleration in 2027 on the contracted book.
The mirror that declined the buildout
Cloudflare, which sells firewall, bot mitigation, content delivery, zero-trust access and a serverless developer platform on the same kind of global edge, monetizes it as expansion inside existing accounts. June-quarter revenue rose 35.9% to $696.1m, a fourth consecutive acceleration; dollar-based net retention reached 120% and remaining performance obligations $2.732bn, up 38%. Non-GAAP gross margin ticked up 30 basis points sequentially, its first sequential gain in eight quarters. Network capital spending ran at 7% of revenue through June against a 14-15% full-year guide, so the step-up is all in the second half. "We're in a very different business than the hyperscalers," chief executive Matthew Prince said on the August 6 call, arguing the company sells completed work rather than rented servers. That posture has its own bill: $99m of severance in the quarter and full-year restructuring charges raised to $165m after May's decision to cut about 1,100 employees.
What the shares have earned
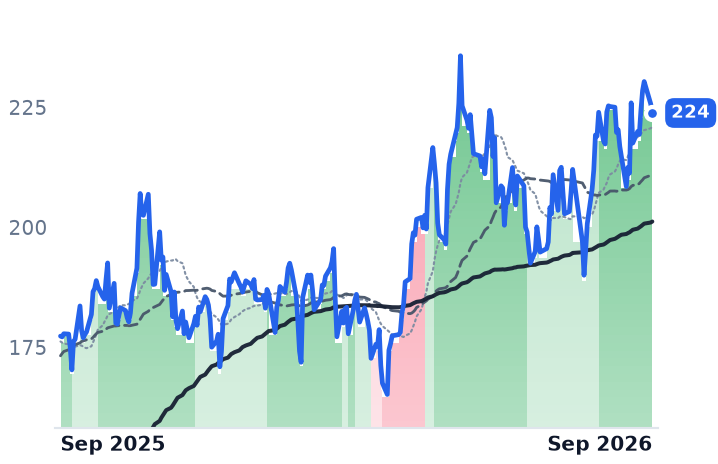
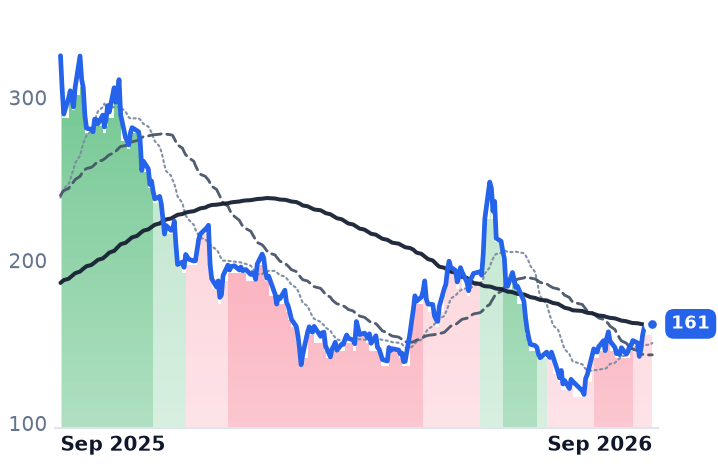
Akamai closed at $109.49 on September 10, 25.9% below its $147.71 close on the day the Anthropic deal landed and 15.8% below mid-June, with its 50-day average crossing below its 200-day in early September. Cloudflare is up 48.9% over six months. The gap tracks gross profit, not orders. HSBC cut Akamai to Hold on August 10, taking its target to $123 from $171 and its valuation multiple to 17x near-term earnings from 25x on cloud margin concerns; JPMorgan upgraded to Neutral in mid-August on inference-led growth. At 16.3x forward earnings against 38.6x trailing, Akamai looks cheap only on earnings that are depressed by design — on enterprise value to trailing EBITDA it is 18.5x, and free cash flow is being consumed. Cloudflare, at 38.3x forward sales and 52.8x forward gross profit, has re-rated well past the 25-28x of enterprise value to 2026 revenue it carried in May.
One session resists explanation. On September 9, Cloudflare rose 10.6% after launching a vulnerability discovery and remediation service built on OpenAI models inside its managed defense product. Akamai rose 9.2% the same day with no contract or earnings of its own — the discoverable event was Leighton at Citi's technology conference, repeating the low-teens 2027 outlook and warning that near-term margins could stay under pressure. The S&P 500 exchange-traded fund fell that day; Fastly and DigitalOcean rose with the complex. The likelier reading is sympathy, not news.
Akamai's 2027 promise now rests on capacity it has pre-sold and must still build, with seven years of economics tied to one private artificial-intelligence company through 2033. Its processors are sold out and the next $500m of them is already spoken for. The growth is contracted; the margin trough is what shareholders own until it arrives.