

Boston Properties Is Refinancing Its October Notes at More Than Double the Old Coupon
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Three big-city office landlords beat estimates and raised guidance this summer, and all three have since given back 12–15% of their share price. The leasing meters are genuinely inflecting — BXP ended June 88.4% occupied against 91.3% leased, a signed-but-not-yet-paying pipeline of about 1.3m square feet, and SL Green signed Manhattan leases 18.0% above the prior rents on the same space.
The cash meters are not. BXP guides same-property cash net operating income flat for 2026 because free rent on newly commenced leases offsets the occupancy gain, and it lifted 2026 leasing capital spending to roughly $500m — about 45% of guided funds from operations. Two-thirds of SL Green's guidance raise is an accounting recognition at One Vanderbilt rather than new rent. Meanwhile the interest bill reprices first.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
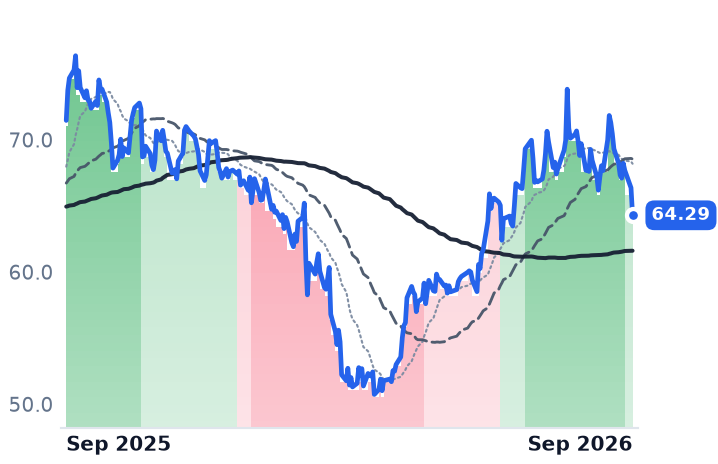
BXP | BXP | Major Urban Markets | 🌱 Emerging Bull | −5.1% | −10.0% |
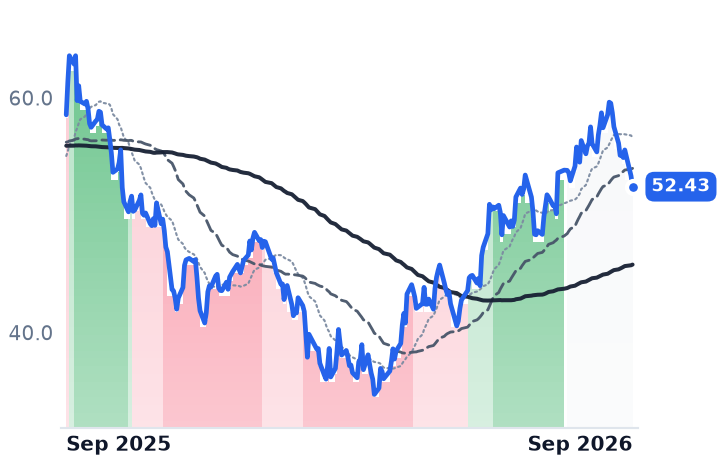
SLG | SL Green Realty | Major Urban Markets | 🌱 Emerging Bull | −6.2% | −10.5% |
| Compared against · context, not the story | |||||
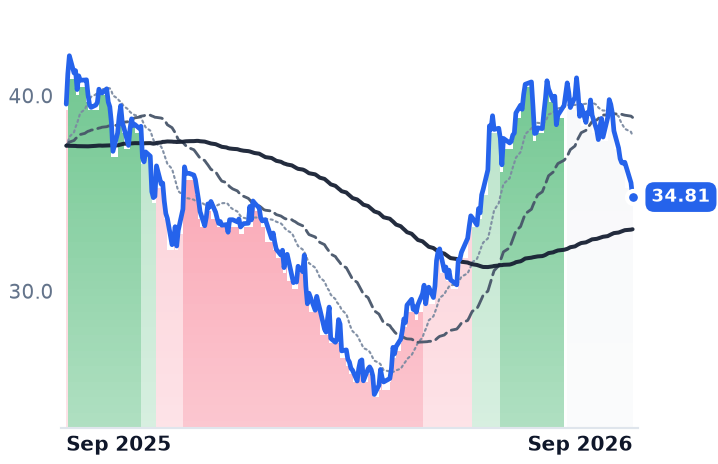
VNO | Vornado Realty Trust | Major Urban Markets | 🌱 Emerging Bull | −11.1% | −12.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BXP | $10.3B | 34.6x | 30.3x | 2.9x | 2.9x | 6.2x | 6.3x | 14.0x | 3.5% |
SLG | $3.7B | n/m | — | 3.6x | 5.5x | 7.0x | 10.7x | 17.7x | -1.0% |
VNO | $6.5B | — | — | 3.6x | 3.4x | 8.4x | 7.9x | 16.2x | 4.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BXP | Revenue | +2.0% | +2.7% | +2.0% |
| EPS | +194.3% | −5.3% | +10.6% | |
SLG | Revenue | +15.3% | −2.4% | −22.0% |
| EPS | +166.4% | −27.9% | −17.1% | |
VNO | Revenue | +4.4% | +7.4% | +7.2% |
| EPS | −108.5% | −145.1% | −18.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Boston Properties is about to pay more than twice as much for the same borrowed dollar. Its operating partnership priced $700m of senior notes due 2036, carrying a 6.050% coupon, explicitly to redeem $1.0bn of 2.750% notes maturing October 1, with the roughly $300m shortfall coming from cash and the revolver. That is a step-up of about 330 basis points on debt already on the balance sheet, and it lands in the same year the company told investors its leasing recovery would not reach cash flow.
That sequencing is the story in office property right now. Demand for premier buildings is measurably improving; the money it produces arrives two years after the signature, while the cost of the capital underneath the building resets immediately.
What the leasing actually says
BXP — 196 assets and 51.2m square feet of Class A space across Boston, Los Angeles, New York, San Francisco and Washington — signed 106 leases totaling roughly 1.8m square feet in the second quarter at a 9.9-year weighted average term, about 129% of its ten-year second-quarter average. Occupancy rose 100 basis points to 88.4%. The portfolio was 91.3% leased, and that 290-basis-point gap is roughly 1.3m square feet of contracted rent that has not started paying. Funds from operations came in at $1.78 a share, eight cents above the guidance midpoint, and full-year guidance went to $6.99–$7.05.
Who is signing matters. "With what we would refer to as these artificial intelligence companies, this is office space, pure and simple office space," president Doug Linde told investors on the July 29 call. "We are simply leasing our space to the next version of technology dot-com."
Where the money goes instead
Same-property cash net operating income is guided flat for 2026 anyway, because free-rent periods on the leases just commenced offset the occupancy gain; management expects the reversal into cash in 2027. And 2026 leasing capital expenditure was raised to about $500m from $400m, with $330m spent by mid-year. Against guided funds from operations of roughly $1.12bn, that is close to 45% — about $3.13 a share of the $7.02 midpoint, before any development spending, against a $2.80 annual dividend.
SL Green, Manhattan's largest office landlord and a third of BXP's market value, shows the same split in a different accounting dress. Its cash meters are the strongest of the group: signed Manhattan leases came in 18.0% above the prior fully escalated rents and same-store cash net operating income rose 4.3%. But of the $1.20 guidance raise to $5.60–$5.90, only $0.40 is portfolio income and fees; $0.80 is additional income recognized from One Vanderbilt. Management does not expect funds available for distribution to cover the $2.47 dividend until 2028. On September 9 the company agreed to sell 110 Greene Street for $226.0m, about $216m net, to repay corporate debt; it paid $255m for the building in 2015.
Vornado, concentrated in New York, posted the best operating quarter of the three — comparable funds from operations of $0.67 against $0.56 a year earlier, New York office occupancy up to 92.2% from an 84.4% trough, cash same-store growth of 11.9%. "The landlord's market that we have been predicting for the past many quarters is here," chairman Steven Roth said on the August 4 call. Its shares have fallen 14.9% since that day, the steepest drop of the three.
The discount rate did the rest
BXP is down 12.9% from its July 29 report day; SL Green is off 12.1% from an August peak. All three are still up 22–34% over six months, off the February crash when fears that agentic software would shrink white-collar headcount knocked an office-property index down 6.7% in two sessions. The 10-year Treasury has since reached 4.818%, its highest since November 2023 — above BXP's 4.36% dividend yield and SL Green's 4.71%.
So the summer's evidence splits cleanly. Manhattan's strongest first half of leasing since 2002, with trophy availability at 3.7% in Midtown, is real demand for exactly the buildings these three own, and it earns the six-month recovery. What nothing in the quarter earns is a lower cost of capital: BXP trades at roughly 9.2x its own guided funds from operations and 13.97x trailing EV/EBITDA, while SL Green's apparent 9.1x becomes about 10.6x once the One Vanderbilt item comes out, against 1.16x its book value. Cheapness is doing real work here rather than none.
The October redemption is the first tranche of a repricing that runs through 2027, and it is the one number in this story that is already contracted. The leases are signed; so is the coupon.