

Talen Already Sold 70% of Its 2027 Power; Its Capacity Auction Cleared at the Cap
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Talen Energy's operating numbers improved all summer and its shares kept falling. The June quarter lifted gross margin from 20.7% to 49.3%, and management raised full-year guidance on August 5 — yet the same quarter carried a $92m net loss.
The explanation is structural. Most of the next two years of generation was sold forward before the data-center bidding began, so a rising PJM curve arrives as hedge marks rather than as margin, and the capacity leg is set administratively: the 2028/29 auction cleared 2.5% below the prior year's ceiling even as PJM's reserve shortfall widened. Talen now trades at 15.2x 2026 consensus earnings against Constellation's 24.8x. TransAlta, sorted into the same industry group, is a flat Alberta story with none of this exposure.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
TLN | Talen Energy | Wholesale Power Producers | ⚠️ Emerging Bear | −12.7% | −22.4% |
TAC | TransAlta | Wholesale Power Producers | 🌱 Emerging Bull | −1.8% | −3.2% |
| Compared against · context, not the story | |||||
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +4.3% | −27.5% |
CEG | Constellation Energy | Diversified Renewable Generators | ⚠️ Emerging Bear | +2.9% | −10.2% |
NRG | NRG Energy | Integrated Retail & Generation | 🔴 Cont. Bear | −3.7% | −28.0% |
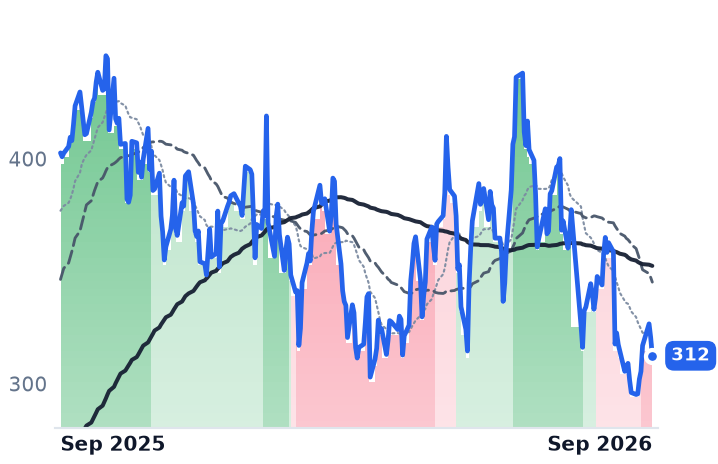
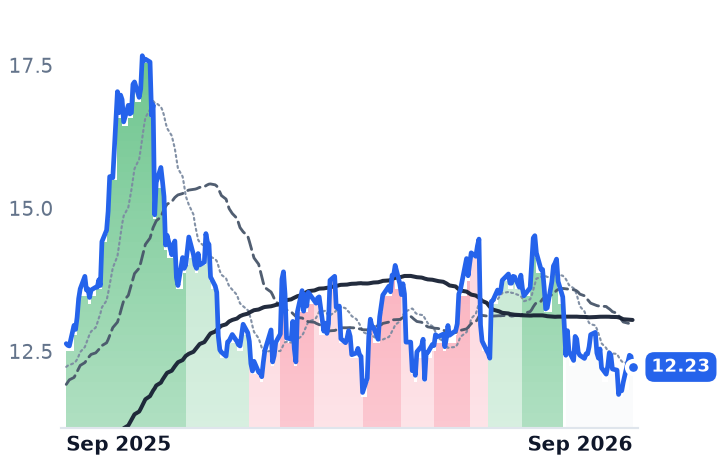
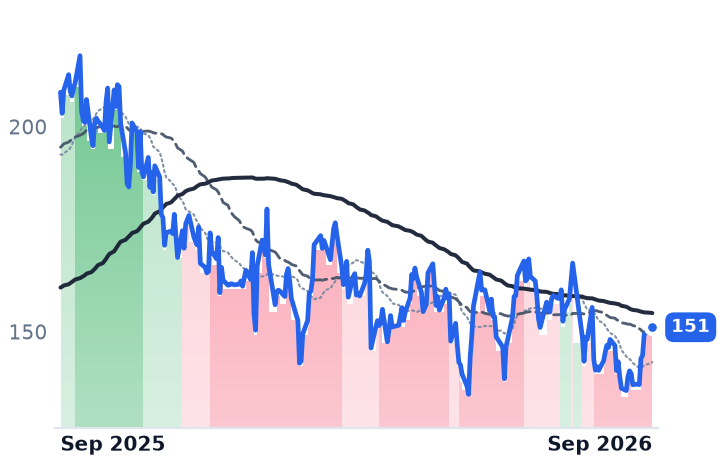
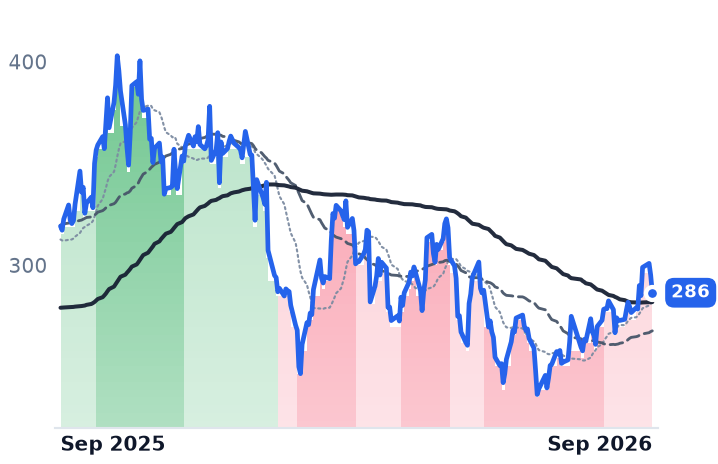
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TLN | $14.2B | n/m | 15.2x | 4.0x | 3.2x | 9.0x | 7.2x | 29.7x | 3.6% |
TAC | $3.7B | n/m | 38.0x | 2.4x | 1.7x | 5.4x | 3.9x | 11.3x | 8.5% |
VST | $51.2B | 25.3x | 17.6x | 3.2x | 2.3x | 24.7x | 17.6x | 10.9x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEG | $107.4B | 29.1x | 24.8x | 3.4x | 3.2x | 3.6x | 3.4x | 15.4x | 0.3% |
NRG | $25.2B | 31.3x | 13.5x | 0.7x | 0.7x | 4.2x | 4.4x | 11.5x | 1.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TLN | Revenue | +84.0% | +15.8% | +4.6% |
| EPS | +247.6% | +48.4% | +17.8% | |
TAC | Revenue | −17.7% | +10.3% | +12.6% |
| EPS | −40.1% | +78.4% | +32.8% | |
VST | Revenue | +16.7% | +9.3% | +4.7% |
| EPS | +80.0% | +18.7% | +18.0% | |
CEG | Revenue | +36.6% | +2.6% | +5.5% |
| EPS | +28.7% | +10.1% | +26.3% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.6% | +15.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
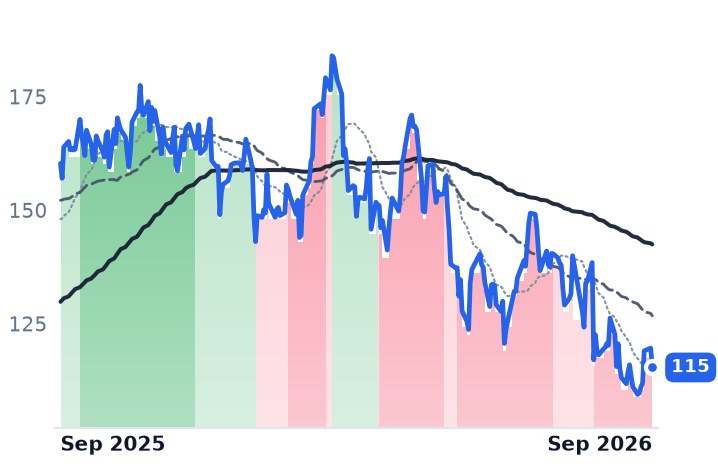
Talen Energy books much of its power years before it delivers it, which is why its most recent quarter shows a 64.5% jump in revenue and a $92m net loss on the same page. The Houston-based independent power producer sells electricity, capacity and ancillary services from roughly 10.7 GW of nuclear, gas, coal and solar generation, and on August 5 it raised 2026 guidance to $2.025bn–$2.225bn of adjusted earnings before interest, taxes, depreciation and amortization. The shares are down 22% over twelve months and slipped into a downtrend on September 3, when the 50-day average crossed below the 200-day.
What is at stake is the roughly $4bn of cumulative adjusted free cash flow Talen expects across 2026 through 2028, and whether a power market that keeps setting records can reach it. On the two legs that carry most of its margin, for now, it cannot.
Sold forward, and capped
At June 30, including the nuclear production tax credit, Talen had hedged about 85% of expected 2026 generation, about 70% of 2027 and only about 30% of 2028. Management cited West Hub spark spreads up nearly 50% year on year in its second-quarter materials — a move that reaches reported income as mark-to-market noise rather than as revenue. The accounts show it as violence: June-quarter gross profit rose 291% to $368m while operating income was minus $72m; the December 2025 quarter paired 58% revenue growth with a $363m loss.
The second leg is set by administrators. PJM's 2028/29 base residual auction cleared at $325 per megawatt-day across the footprint — the preset cap, for the third auction running, and 2.5% below the prior year's $333.44 ceiling. PJM's own simulation put the uncapped price at $554.72, with the auction still leaving a 6.8 GW shortfall against the target reserve margin. Talen keeps 98% of its generation in PJM, per Mizuho's August 24 initiation at Outperform. Scarcity worsened; its capacity revenue per megawatt-day went down.
Even the celebrated data-center contract is a volume schedule rather than a price bet: the Amazon agreement runs to 2042 at up to 1,920 MW from Susquehanna, ramping to 840–1,200 MW in 2029, with roughly $18bn of revenue expected at full quantity. "We believe blending new capacity with existing energy on a front-of-the-meter grid-connected site is more reliable and durable, and in fact, less expensive than any behind-the-meter solution," chief executive Mac McFarland told investors on the second-quarter call.
The per-share number is a financing decision
Talen closed the ~$3.5bn Cornerstone purchase of about 2.6 GW of PJM gas plants, funded with roughly $2.6bn of cash and 2,399,998 shares issued to Energy Capital Partners, $983.5m of which was registered for resale in June with lock-ups beginning to expire in mid-September. Against that, some 15 million shares have been repurchased for about $2.3bn since 2024, taking the diluted count from 53.17m to 45.90m. Management targets net leverage below 3.5x adjusted EBITDA by year-end.
The decisive session was August 18, when Talen fell 11.4% on 2.17m shares — attributed to a post-earnings reset, the share registration and rotation out of power names — while Constellation fell about 4%. Over three months Constellation is up 16.1% and Vistra 3.2%, so the complex is not de-rating together.
The other name in the group
TransAlta, the Calgary generator sorted into the same industry classification, is a different trade entirely. Alberta spot power averaged C$29 per megawatt-hour last quarter against C$40 a year earlier, its own hedges realized C$63, and it reaffirmed C$950m–C$1.05bn of adjusted EBITDA. Its shares are down 3.6% over twelve months and its trend has been flat since late July. At 11.3x trailing enterprise value to EBITDA it sits between Vistra and Constellation; at 38x forward earnings on profits guided down 40%, it is dear.
The verdict
Nothing in Talen's reported business explains a 22% decline. Revenue accelerated, gross margin more than doubled, cash guidance went up, and the shares now fetch 15.2x 2026 consensus earnings against Vistra's 17.6x and Constellation's 24.8x, and 9.0x trailing gross profit against the 16.5x recorded in early May while that gross profit grew. What the business does explain is why record power headlines never showed up in the numbers investors were repricing: the hedge book fenced 2026 and 2027, and the capacity cap took the rest. This was a valuation reset rather than an earnings one — but a company whose reported loss is a hedge artifact has few defenses when sentiment turns, because its trailing earnings multiple offers no floor to argue from.
The part of Talen a rising power curve can still reach is 2028, about 70% of it unsold. Shareholders wait two years to find out what it fetches.