

Supernus's Shares Became a Claim on Indivior's SUBLOCADE at 1.5401 to One
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Supernus posted its fastest growth in years and raised guidance, and the market has ignored every number since. June-quarter revenue rose 32.4% to $219.1m, and full-year guidance went up to $860–890m.
The same day, the company agreed to merge into Indivior, each Supernus share converting into 1.5401 Indivior shares. Supernus has traded as a fixed claim on Indivior ever since, falling almost exactly as much.
What sets the price now is Indivior's buprenorphine franchise, which posted record quarterly SUBLOCADE revenue of $253m and raised guidance while its shares got cheaper, at 8.1x forward earnings. Supernus trades slightly above dividend-adjusted parity, which points at a markdown of the merger currency rather than doubt about closing.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
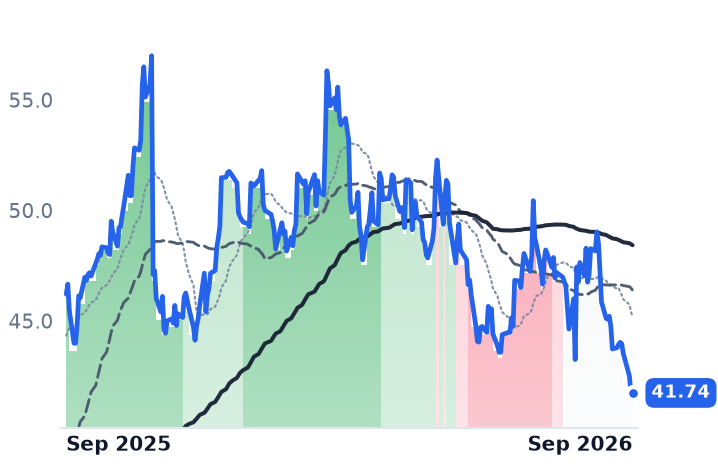
SUPN | Supernus Pharmaceuticals | Specialty Branded Pharma | ⚠️ Emerging Bear | −13.6% | −9.7% |
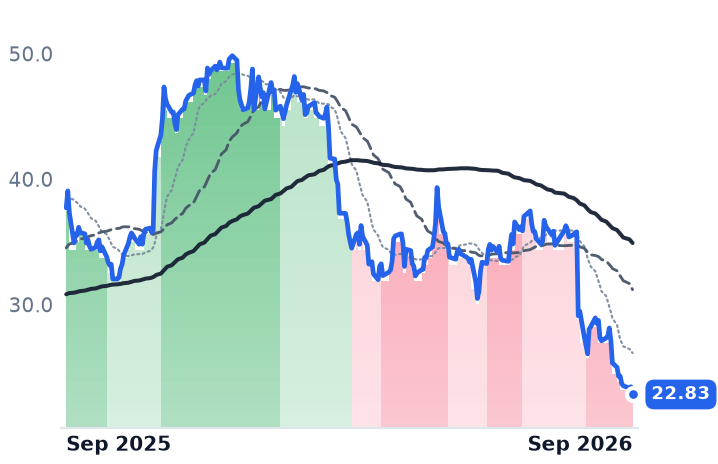
COLL | Collegium Pharmaceutical | Specialty Branded Pharma | ⚠️ Emerging Bear | −14.6% | −39.4% |
| Compared against · context, not the story | |||||
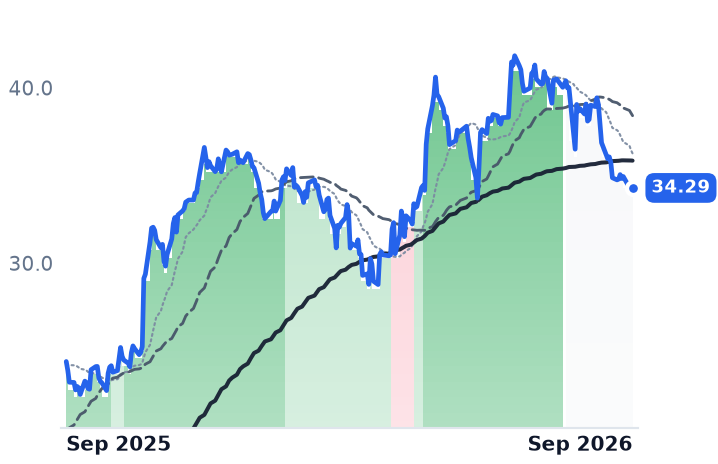
INDV | Indivior Pharmaceuticals | Specialty Branded Pharma | 🟢 Cont. Bull | −12.2% | +40.6% |
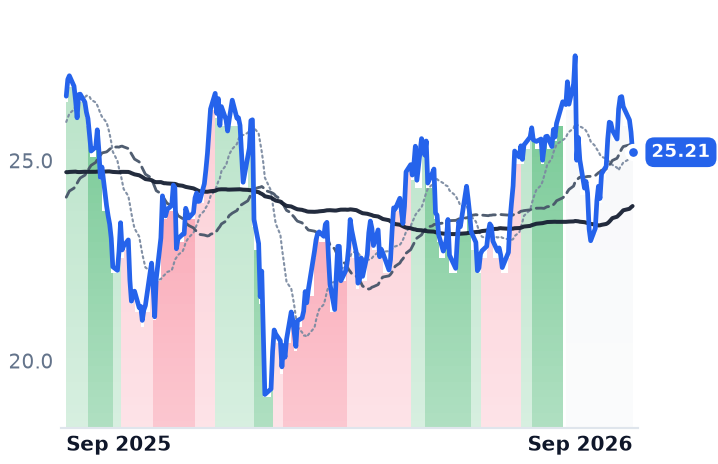
PCRX | Pacira BioSciences | Specialty Branded Pharma | 🌱 Emerging Bull | +3.0% | −5.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SUPN | $2.4B | n/m | 16.2x | 2.9x | 2.7x | 3.3x | 3.1x | n/m | 0.8% |
INDV | $4.3B | 12.1x | 8.1x | 3.2x | 3.2x | 3.8x | 3.8x | 10.6x | -2.6% |
COLL | $739.8M | 14.9x | 3.1x | 0.9x | 0.9x | 1.5x | 1.5x | 2.5x | 44.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCRX | $1.0B | 73.5x | 9.0x | 1.4x | 1.4x | 1.7x | 1.7x | 10.7x | 17.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SUPN | Revenue | +25.1% | +56.0% | +21.3% |
| EPS | −17.2% | +73.9% | +21.1% | |
INDV | Revenue | +11.8% | +5.1% | +6.4% |
| EPS | +79.4% | +9.4% | +4.8% | |
COLL | Revenue | +7.0% | +0.8% | +0.5% |
| EPS | −1.3% | −10.2% | −4.3% | |
PCRX | Revenue | +3.2% | +4.7% | +13.1% |
| EPS | −2.4% | +19.6% | +37.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Supernus Pharmaceuticals, a Rockville, Maryland developer of central-nervous-system medicines, told investors on 3 August that 2026 revenue would land between $860m and $890m, raising its own forecast after a June quarter in which sales grew 32.4% to $219.1m. The same morning it announced something that made the guidance largely irrelevant to its shareholders: an all-stock merger of equals with Indivior, in which every Supernus share converts into 1.5401 Indivior shares and Indivior holders take about 56.5% of the combined company.
A fixed exchange ratio is a wire, and it has been carrying current in one direction. From 5 August to 10 September Supernus fell 12.0% and Indivior fell 12.2%. Rebuilding Supernus's price each day as 1.5401 times Indivior's close, less the roughly $7.75 a share of the $1bn special dividend Indivior holders collect immediately before the exchange, reproduces Supernus within about two percent through mid-August and within five percent since. Qelbree prescriptions no longer price this equity. Buprenorphine does.
The business the price left behind
Supernus's own quarter was the best in its recent history. Qelbree, its non-stimulant attention-deficit treatment, grew net sales 15% to $89.2m on 264,545 prescriptions, up 17%. The four products management counts as growth assets — Qelbree, GOCOVRI, ZURZUVAE and ONAPGO — together reached $175.7m, up 52%, enough to bury the decline in the legacy epilepsy drugs Trokendi XR and Oxtellar XR.
The reported loss of $58.4m is purchase accounting and a write-down, not trading: a non-cash $54.9m impairment of the APOKYN intangible plus $25.3m of acquired-intangible amortization, most of it on ZURZUVAE from last year's Sage transaction. Gross margin, at 84.6%, slipped from 89.8%.
What Qelbree does not have is a protected socket. It competes against generic atomoxetine in a market where stimulants take about 76% of drug-class revenue, so growth is bought with sales representatives and payer coverage. Collegium Pharmaceutical, the Massachusetts pain specialist that cut its own 2026 guidance three days after Supernus raised its, is buying the same prescribers: Jornay PM grew 41% to $46.1m in the June quarter, took 29.2% of the branded long-acting methylphenidate market, and Collegium now fields 190 attention-deficit representatives. Collegium's shares are down 39% over twelve months and trade at 2.5x trailing enterprise value to earnings before interest, taxes, depreciation and amortization.
What sets the price now
Indivior, based in North Chesterfield, Virginia, sells buprenorphine medicines for opioid dependence and had its strongest quarter on record: revenue of $343m, SUBLOCADE — its monthly injectable — at $253m, up 21%, adjusted EBITDA up 111% to $186m, and full-year SUBLOCADE guidance lifted to $1.01–1.05bn. "Every fundamental metric in support of SUBLOCADE is trending in a strong direction," chief executive Joe Ciaffoni said on the 4 August merger call. "In the quarter, we had record new patient starts. We've seen stable market share at 76%."
The shares got cheaper against all of it — 8.1x forward earnings against 12.1x trailing. Supernus, by contrast, is at 16.2x forward earnings and 3.29x trailing gross profit; the comparison runs on gross profit because gross margins under this label differ too widely for sales multiples to mean anything.
The verdict
Nothing company-specific was discoverable to explain a steady slide that began the week both companies raised guidance. Because Supernus trades at a small premium to dividend-adjusted parity rather than a discount, the likelier reading is not deal-break risk but a re-rating of the currency itself: Indivior's holders are diluting a business earning a 46% adjusted EBITDA margin into one earning 18%, then paying themselves $1bn of it — partly with a $650m Citibank term loan — on the way out. Indivior's own merger filing says the dilution is real and the benefits are not guaranteed. Management targets $125m of annual cost savings within a year of closing and has given no 2027 forecast.
Until the ratio is broken, Supernus's earnings reports are informational. The merger is due to close in the fourth quarter, subject to two shareholder votes whose dates have not been set — and the last legacy opioid settlement instalment, $50m, falls due in December 2027, inside the combined company's first full year.