

Freshpet Deferred Capex Below Its $150m Budget Because Installed Lines Outperformed
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A company that spent a decade building factories ahead of its customers has started spending less than it planned, and the market has treated it as two different companies in six months. Freshpet's sales growth re-accelerated for three straight quarters, reaching 15.5% in the June quarter on volume alone, and adjusted gross margin excluding depreciation hit 48.6%. Free cash flow was positive in consecutive quarters for the first time.
The operating case is real; the catch sits in the household data. Penetration growth slowed to 5% year over year from 8% the prior quarter, while existing heavy buyers spent more — a shift from recruiting households to milking them. Central Garden & Pet, the other pet name in the same classification, raised earnings guidance while its revenue declined for a fourth year.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
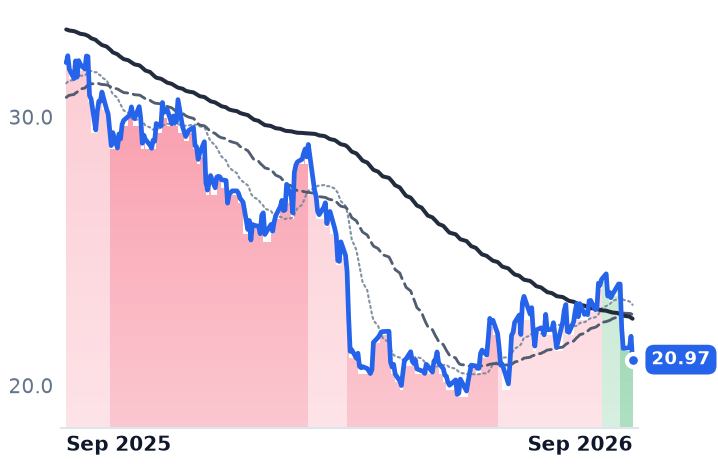
FRPT | Freshpet | Pet Food & Nutrition | 🔴 Cont. Bear | −8.8% | +23.6% |
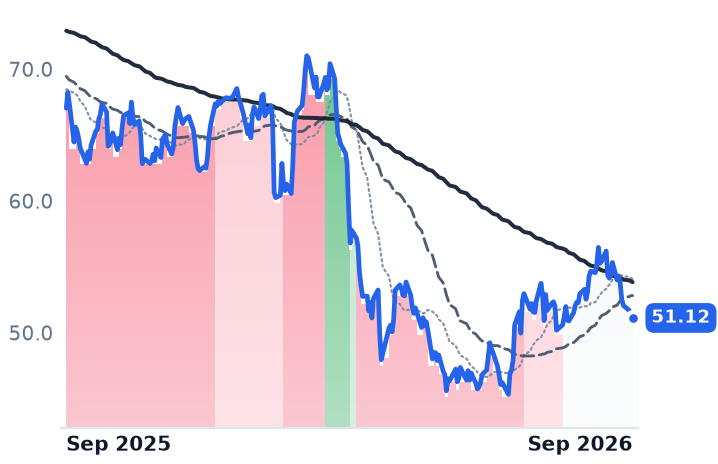
CENT | Central Garden & Pet | Pet Food & Nutrition | 🟢 Cont. Bull | −8.4% | +9.9% |
| Compared against · context, not the story | |||||
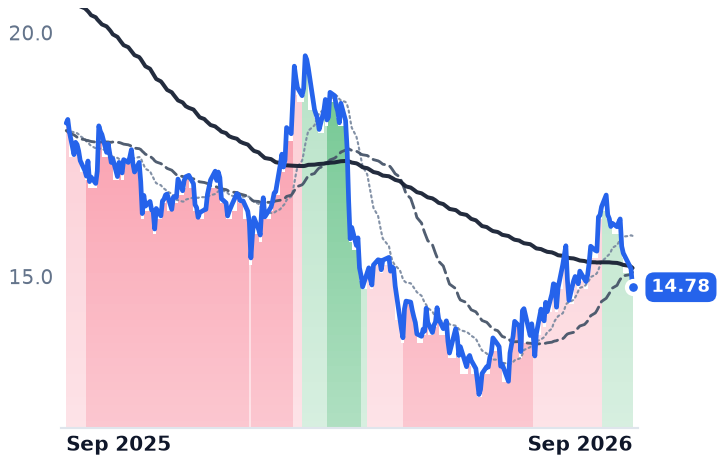
CHWY | Chewy | Pet & General Specialty | 🔴 Cont. Bear | −5.4% | −39.1% |
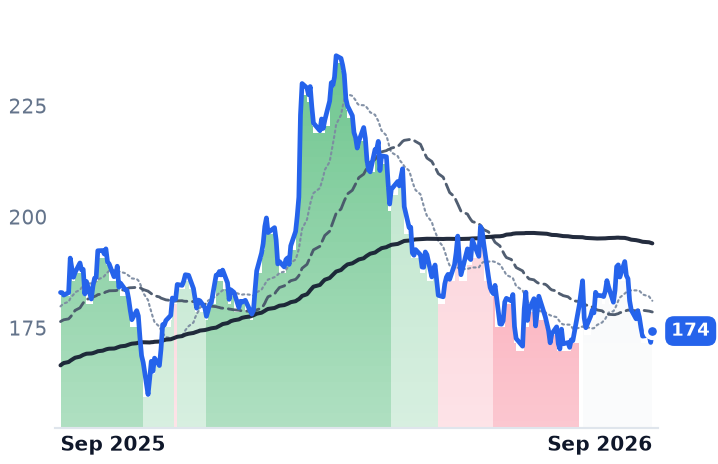
GIS | General Mills | Cereals & Breakfast | 🔴 Cont. Bear | −4.0% | −24.6% |
CPB | Campbell Soup | Frozen & Prepared Foods | 🌱 Emerging Bull | −7.7% | −34.5% |
MKC | McCormick & Company, Incorporated | Condiments & Sauces | 🔴 Cont. Bear | −2.7% | −23.7% |
CAG | Conagra Brands | Frozen & Prepared Foods | 🔴 Cont. Bear | −0.8% | −18.5% |
HSY | The Hershey | Food Confectioners | ⚠️ Emerging Bear | −4.3% | −4.7% |
ZTS | Zoetis | Animal Health | 🔴 Cont. Bear | −2.1% | −50.4% |
IDXX | IDEXX Laboratories | Specialty & Veterinary Diagnostics | ⚠️ Emerging Bear | −13.6% | −19.9% |
WOOF | Petco Health and Wellness | Pet & General Specialty | 🔴 Cont. Bear | −10.6% | −30.6% |
ELAN | Elanco Animal Health Incorporated | Animal Health | ⚠️ Emerging Bear | +1.6% | +26.1% |
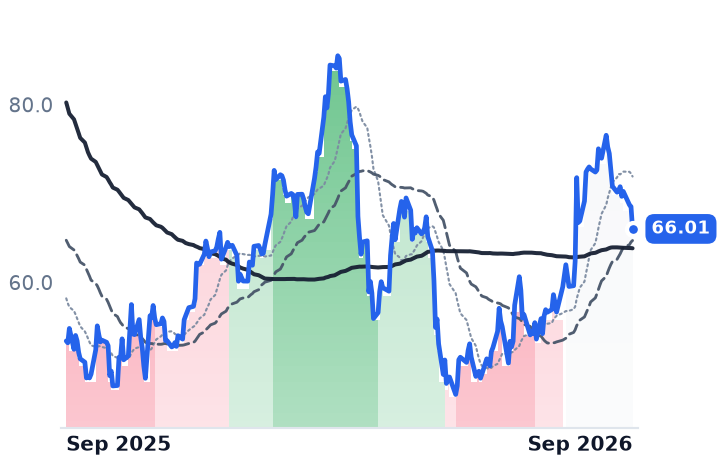
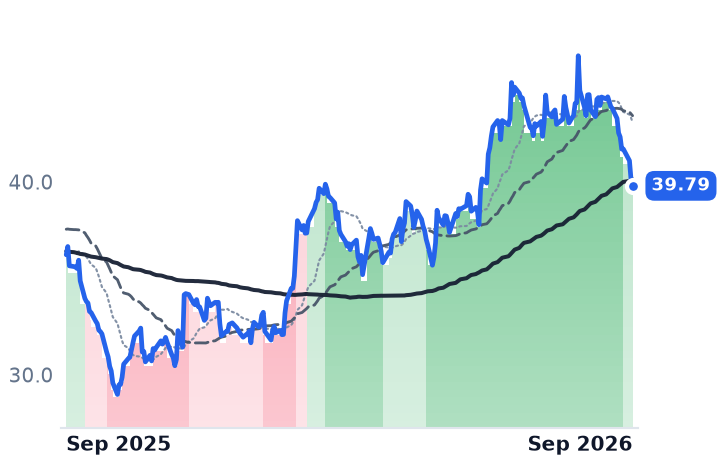
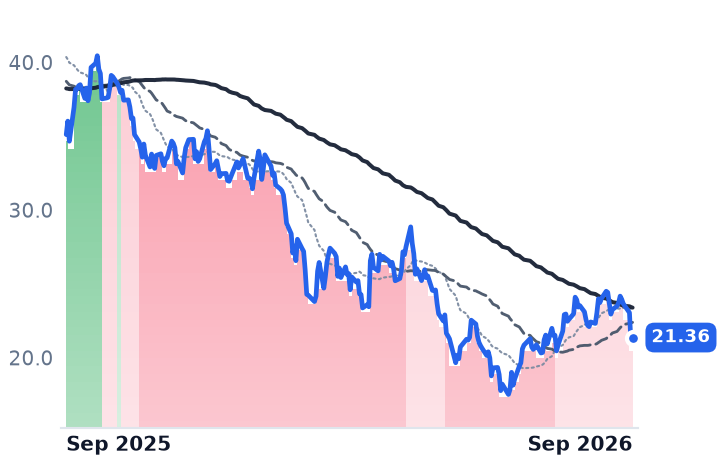
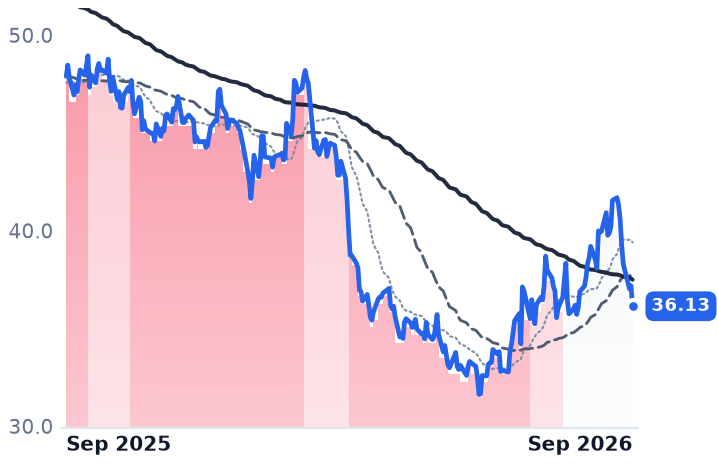
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FRPT | $3.2B | 15.7x | 33.7x | 2.7x | 2.6x | 6.9x | 6.7x | 13.3x | 5.3% |
CENT | $2.5B | 14.7x | 13.3x | 0.8x | 0.8x | 2.5x | 2.5x | 7.4x | 13.9% |
CHWY | $8.8B | 39.6x | 24.1x | 0.7x | 0.6x | 2.4x | 2.2x | 21.4x | 6.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GIS | $17.6B | 8.1x | 9.6x | 1.0x | 1.0x | 2.9x | 2.9x | 10.1x | 9.4% |
CPB | $6.0B | 10.8x | 9.2x | 0.6x | 0.6x | 2.0x | 2.1x | 8.6x | 15.4% |
MKC | $12.5B | 7.6x | 15.0x | 1.8x | 1.6x | 4.6x | 4.2x | 13.8x | 6.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CAG | $6.4B | n/m | 7.9x | 0.6x | 0.6x | 2.4x | 2.4x | 13.8x | 13.1% |
HSY | $37.9B | 34.0x | 22.2x | 3.2x | 3.1x | 9.1x | 8.9x | 20.8x | 5.7% |
ZTS | $31.1B | 11.9x | 10.7x | 3.3x | 3.2x | 4.6x | 4.5x | 7.3x | 6.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IDXX | $41.7B | 38.7x | 36.1x | 9.4x | 8.9x | 15.1x | 14.3x | 28.0x | 2.0% |
WOOF | $710.8M | 77.6x | 12.5x | 0.1x | 0.1x | 0.3x | 0.3x | 10.3x | 40.2% |
ELAN | $9.9B | n/m | 18.8x | 2.0x | 2.0x | 4.1x | 4.0x | 17.9x | 3.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FRPT | Revenue | +11.1% | +8.5% | +8.0% |
| EPS | −20.4% | −3.9% | +11.3% | |
CENT | Revenue | −3.2% | −2.8% | +9.3% |
| EPS | +13.3% | +5.0% | +6.4% | |
CHWY | Revenue | +6.7% | +8.4% | +7.9% |
| EPS | −32.6% | +68.1% | +36.6% | |
GIS | Revenue | −5.6% | −2.5% | +1.0% |
| EPS | −18.2% | −4.5% | +4.0% | |
CPB | Revenue | −4.7% | −0.2% | +0.6% |
| EPS | −25.4% | −1.0% | +5.3% | |
MKC | Revenue | +15.5% | +3.6% | +3.8% |
| EPS | +2.8% | +7.5% | +9.6% | |
CAG | Revenue | −3.1% | −1.3% | +1.1% |
| EPS | −26.5% | −0.9% | +5.0% | |
HSY | Revenue | +5.8% | +2.8% | +2.7% |
| EPS | +40.4% | +18.1% | +8.6% | |
ZTS | Revenue | +3.8% | +4.4% | +5.1% |
| EPS | +9.5% | +7.6% | +8.4% | |
IDXX | Revenue | +9.9% | +8.8% | +9.1% |
| EPS | +13.4% | +12.9% | +13.2% | |
WOOF | Revenue | −2.7% | +0.6% | +1.4% |
| EPS | −275.3% | +36.8% | +40.4% | |
ELAN | Revenue | +8.5% | +5.2% | +4.9% |
| EPS | +13.3% | +12.3% | +14.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Freshpet spent a decade building refrigerated kitchens before it had the demand to fill them. This year the company budgeted $150m of capital spending and is deliberately spending less, because the production lines it already installed are running better than planned and management wants to optimize a new bagging technology before committing to more. Free cash flow was $14.7m in the June quarter against $0.5m a year earlier, the second consecutive positive quarter after $12.7m in the March quarter.
That matters because Freshpet's unit of business is not a shelf. The company makes refrigerated fresh dog and cat food and sells it out of branded coolers it owns and installs inside other retailers' stores — 30,721 stores as of the June quarter, of which about a quarter now carry two or three fridges, with total distribution points up 13% year over year. Growth is household penetration multiplied by how much each household spends. Margin is a capacity-utilization number, which is why the depreciation on those company-owned kitchens sits inside cost of goods sold.
The gap between two gross margins
The June quarter shows the arithmetic plainly: adjusted gross margin excluding depreciation reached 48.6%, up 1.7 points, against a reported gross margin of 42.1%. The roughly six-and-a-half-point difference is the build-ahead. Net sales rose 15.5% to $305.6m, essentially all of it volume, and guidance went up twice — sales growth to 10–12% and adjusted earnings before interest, taxes, depreciation and amortization to $210–220m.
"We now have 3 lines utilizing our new bag product technology 2 in Bethlehem and 1 in Ennis, and we are encouraged by the improvement in quality, throughput yield and unit economics," chief executive Billy Cyr told investors on the August 5 call. "At fully optimized performance, we expect over 100 basis points of gross margin improvement on the entire business from the lines we have already installed."
Where the model is straining
Two things cut the other way. Household penetration reached 15.9 million households, up 5% year over year — down from 8% growth the prior quarter — while buy rate rose 7% to $117 and the heaviest users, who spend about five times the average, now account for 71% of sales. Growth is migrating from new households to existing ones. And logistics ran at 6.9% of sales against 5.7%, roughly $8m more than originally guided, on fuel and trucking costs.
The category is no help. On September 9, Chewy's management said the broader pet consumables market was roughly flat year over year, with de-premiumization visible in treats and toppers; its shares fell about 9% that session. Meanwhile Mars, General Mills, Nestlé Purina and Colgate-Palmolive's Hill's have all entered fresh formats — refrigerated and frozen dog food grew 17.8% to $1.6bn in the year to August 2025, the only pet food category growing.
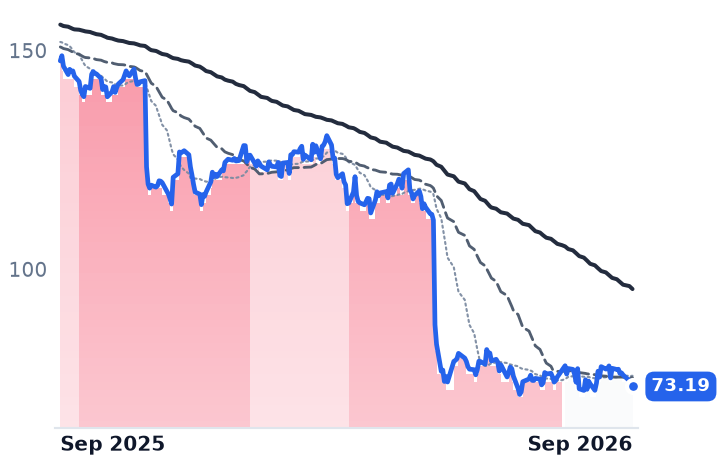
The shares have moved in jumps, not drifts. Freshpet fell 38% between March and June, on a Bank of America downgrade to Neutral with a $60 target, the Hill's entry and removal from Russell growth benchmarks, then rose 30% — including 15.1% on the August 5 print. Two years of de-rating remain: the stock is half its September 2024 level while trailing revenue is 21% above the 2024 full year, compressing the sales multiple from roughly 7x to 2.7x. At 13.3x trailing enterprise value to EBITDA the shares are not expensive against their own history; at 33.7x forward earnings they are not cheap in absolute terms.
The mirror
Central Garden & Pet, filed under the same packaged-foods classification, runs pet supplies alongside a weather-driven lawn-and-garden half and demonstrates the opposite engine. Fiscal third-quarter net sales fell 8% to $882m, organic sales rose 2% after exiting pet distribution, gross margin expanded 1.3 points to 35.9% — and earnings per share fell on both reported and adjusted measures, even as full-year adjusted guidance was raised to "$2.85 or better." The diluted share count is down 3.6%, which offset roughly three-quarters of the decline in net income. Revenue has now fallen four years running, and consensus models further declines in each of the next two. At 7.4x trailing EBITDA with a trailing free-cash-flow yield near 14%, it is priced as what it is: a cash machine that shrinks.
The verdict divides cleanly. Freshpet's operating inflection is earned — accelerating volume, a widening margin as the kitchens fill, capital spending falling below budget rather than above it. What nothing in the June quarter explains is how the company keeps compounding once penetration growth halves and the flat category stops handing it new households. Central's improvement is arithmetic performed on a declining base, and the arithmetic has a floor.
Freshpet's next print carries a comparison headwind of more than two points from a large club customer's prior-year expansion. It is the first quarter in which the fridge network has to grow through the calendar rather than with it.