

Darling Ingredients' Fuel Venture Out-Earned Its Entire Rendering Business Last Quarter
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two companies filed under Packaged Foods sell almost no packaged food, and last quarter their earnings were set by two mechanisms neither controls: an Environmental Protection Agency blending rule and the corn market's timing.
Darling Ingredients, the world's largest renderer, earned combined adjusted EBITDA of $742m in its June quarter against $250m a year earlier — and $389m of that came from Diamond Green Diesel, the 50/50 renewable-fuel venture with Valero whose results never appear in Darling's revenue. Ingredion, a corn wet-miller, ran the same commodity in reverse: gross margin fell three percentage points to 23.0% as corn near multi-year highs landed inside contracts priced months earlier.
Darling's move is earned. Its cheap-looking forward multiple is not a discount — it is peak-cycle arithmetic, since consensus already models earnings fading two years out.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
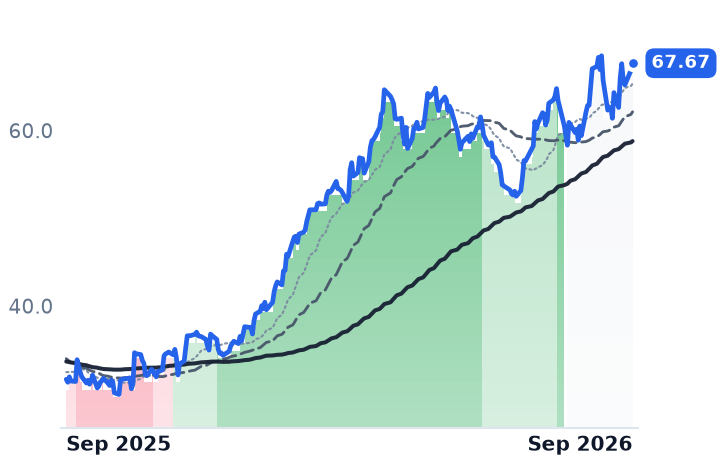
DAR | Darling Ingredients | Specialty Ingredients & Co-Products | 🟢 Cont. Bull | +8.9% | +113.9% |
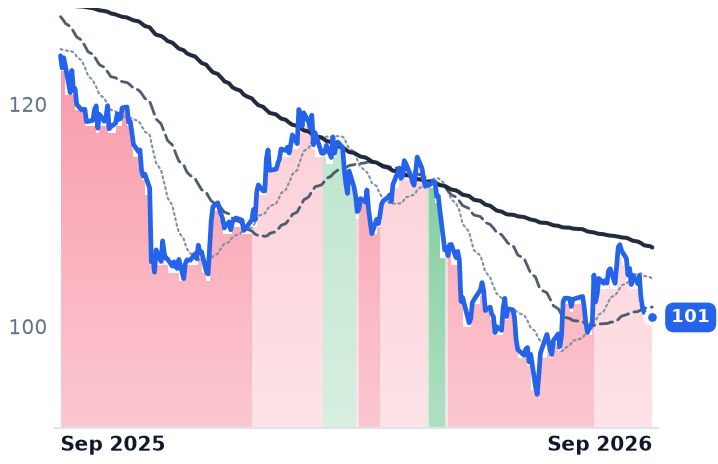
INGR | Ingredion Incorporated | Specialty Ingredients & Co-Products | 🔴 Cont. Bear | −3.0% | −18.9% |
| Compared against · context, not the story | |||||
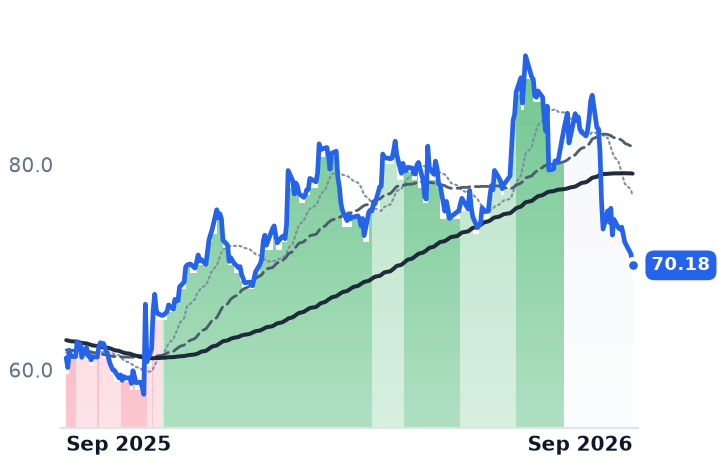
JBSS | John B. Sanfilippo & Son | Specialty Ingredients & Co-Products | 🟢 Cont. Bull | −15.2% | +14.7% |
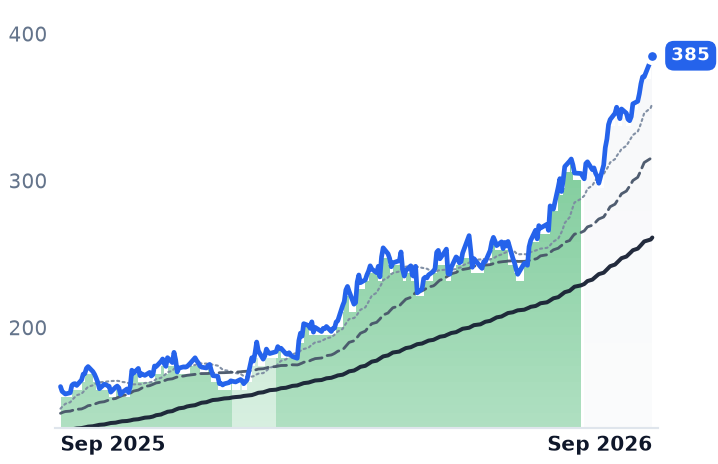
VLO | Valero Energy | Integrated Refiners | 🟢 Cont. Bull | +24.0% | +140.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DAR | $10.7B | 17.9x | 10.6x | 1.6x | 1.6x | 6.5x | 6.3x | 9.9x | 8.2% |
INGR | $6.4B | 10.8x | 9.6x | 0.9x | 0.9x | 3.7x | 3.7x | 6.4x | 10.3% |
JBSS | $875.7M | 13.1x | 11.4x | 0.8x | 0.7x | 4.1x | 4.0x | 7.7x | 5.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VLO | $98.4B | 14.2x | 9.1x | 0.7x | 0.7x | 6.5x | 6.0x | 7.7x | 10.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DAR | Revenue | +3.6% | +14.5% | +4.1% |
| EPS | −68.8% | +1308.0% | −7.4% | |
INGR | Revenue | −0.6% | +1.4% | +1.4% |
| EPS | −5.9% | +6.4% | +5.6% | |
JBSS | Revenue | +1.0% | +0.1% | — |
| EPS | +12.2% | +0.1% | — | |
VLO | Revenue | +20.4% | −13.1% | −10.9% |
| EPS | +275.0% | −29.2% | −26.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Darling Ingredients is filed under Packaged Foods, and it makes none. The Irving, Texas company collects slaughterhouse by-products, used cooking oil and bakery waste — it is often paid to take them — and converts them into feed fats, proteins, collagen and fuel feedstock. In the quarter ended July 4 it reported net income of $387.3m against $12.7m a year earlier. Roughly half of the earnings power behind that figure sits in a business whose sales Darling never books.
That business is Diamond Green Diesel, the 50/50 renewable-diesel and sustainable-aviation-fuel venture with Valero. It contributed $389m of EBITDA to Darling in the quarter, against $43m a year earlier, on about 356m gallons — roughly $2.23 a gallon, or nearer $1.95 stripping out $51m of tariff recovery. Darling's own consolidated ingredients operations produced $353m. The venture out-earned the company that owns half of it, and it did so because of a rule.
A margin Washington sets
On April 1 the Environmental Protection Agency published record Renewable Fuel Standard volume obligations for 2026 and 2027 — 25.82bn and 25.98bn compliance credits, with 70% of past small-refinery exemptions reallocated into those years. Prices for the credits that renewable diesel generates have risen about 130% this year. "This policy, which was only implemented April 1st, has essentially achieved or it's achieving the objectives of the EPA and the administration as a whole," chief financial officer Bob Day told investors on the July 30 call. "It's leading to higher prices at the farm gate, which is what they wanted."
The farm gate is the other half of Darling. Feed Ingredients adjusted EBITDA rose 77% to $240.5m, per the company's earnings filing, on rallying fat and protein values. The same rally is a cost inside the venture: Fastmarkets put domestic tallow at 615 cents a gallon delivered and Gulf used cooking oil near four-year highs, after early clean-fuel-credit guidance disqualified imported feedstock. Darling is long that squeeze on one side of its accounts and short it on the other.
Leverage fell to 2.3x from 2.9x at year-end, helped by $280m of distributions from the venture; $73m of stock was repurchased. "Essentially we will be investment grade if we want to be," chairman and chief executive Randall Stuewe said on the same call.
Ingredion buys the same rally as a cost
Ingredion, the corn wet-miller that sells starches, syrups and dextrose and books corn oil and gluten feed as co-product credits, has no offsetting leg. Corn traded around $5.12 a bushel for September delivery in early September, the highest in more than three years, with world stocks-to-use at 12-year lows; tapioca root is up 40% since January. Those costs arrive inside annual contracts priced months earlier, and management says pass-through takes a quarter to a quarter and a half. Gross margin fell to 23.0% from 26.0% and operating income dropped 30.6%. A run of problems at the Argo, Illinois plant cost roughly $40m in the first quarter and $20m-25m in the second.
Not all of it is deteriorating. "Quarter 2 marked the ninth consecutive quarter of net sales volume growth in the segment, up 7%," chief executive James Zallie said on August 4 of Texture & Healthful Solutions, which grew operating income 5%. The Tate & Lyle acquisition approved by shareholders on July 28 would push more than half of revenue into that segment — but completion is expected in the second half of 2027.
What each price earns
Darling has earned its year: the rule changed, the credit stack repriced, and both its legs responded. What the shares do not yet contain is durability. At 17.9x trailing earnings and 10.6x forward on consensus of $6.37 for the year ending January 2027, the forward figure looks cheap only against a number the same analysts expect to fade — $5.90 then $5.02, or 13.5x two years out. Ingredion's de-rating is the plainer case: at 10.8x trailing against roughly 11.6x a year ago, the multiple barely moved. The price fell because earnings did.
The recent softness in this corner of the market belongs to neither. It traces to John B. Sanfilippo, the snack-nut packer, whose August 19 quarter missed badly on 15.7% gross margin.
Final clean-fuel-credit regulations remain pending after a May 28 hearing. Half of Darling's economics can be re-cut in Washington without a gallon changing hands.