

Robert Half's Consulting Arm Lost 19.9% of Its Billable Hours as Staffing Margins Held
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The industry that was supposed to be artificial intelligence's first casualty is watching its labour meters turn — and at Robert Half the part that is shrinking is the arm that has nothing to do with hiring. Permanent placement revenue grew 2.9% year over year in the June quarter and contract talent gross margin held at 39.1%, while Protiviti, the consulting business, shed revenue as United States financial-services deregulation gutted its compliance book.
The market has not sorted this out. Robert Half trades at 30.9x forward earnings against consensus that puts 2026 profit below 2025's, while ManpowerGroup, four quarters into accelerating revenue, sits at 15.8x forward. Kforce, the third name under the label, reported technology job orders up 18%. All three gapped down together on September 8 with no company news at any of them.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
RHI | Robert Half | Staffing & Recruitment | 🌱 Emerging Bull | −6.9% | +14.7% |
MAN | ManpowerGroup | Staffing & Recruitment | 🌱 Emerging Bull | +2.0% | +52.7% |
| Compared against · context, not the story | |||||
KFRC | Kforce | Staffing & Recruitment | 🌱 Emerging Bull | −12.4% | +75.3% |
12-month price & trend
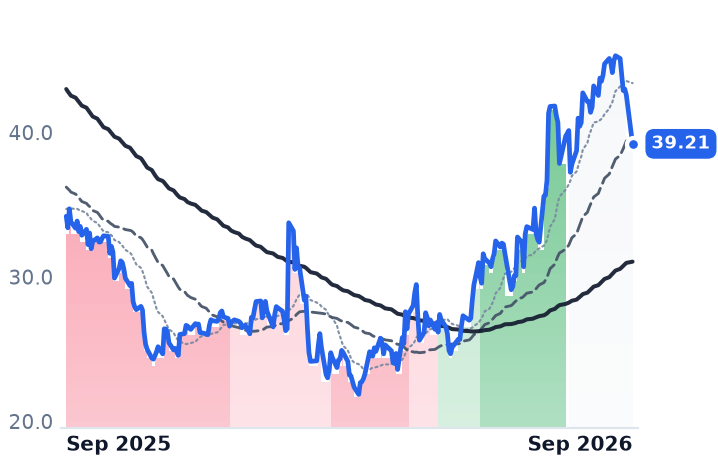
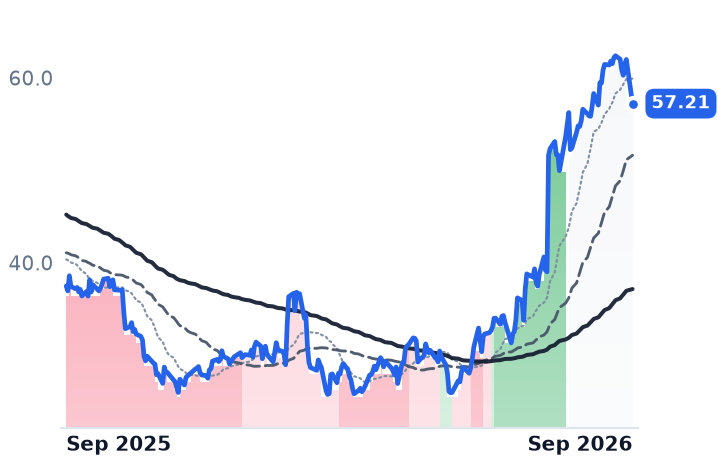
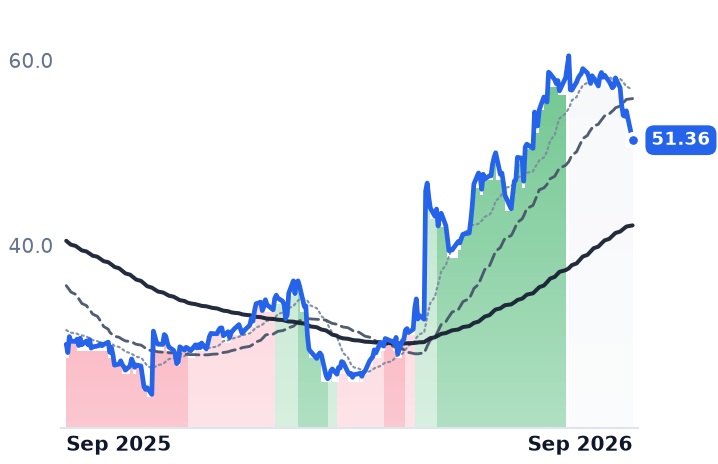
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RHI | $4.0B | 34.1x | 30.9x | 0.8x | 0.8x | 2.1x | 2.1x | 26.3x | 5.4% |
MAN | $2.7B | 25.5x | 15.8x | 0.1x | 0.1x | 0.9x | 0.9x | 9.0x | 2.2% |
KFRC | $915.9M | 24.1x | 20.1x | 0.7x | 0.7x | 2.5x | 2.4x | 18.1x | 2.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RHI | Revenue | −1.0% | +4.1% | +5.2% |
| EPS | −4.5% | +55.5% | +26.1% | |
MAN | Revenue | +7.2% | +3.7% | +4.0% |
| EPS | +26.3% | +34.4% | +34.3% | |
KFRC | Revenue | +4.3% | +4.4% | +4.6% |
| EPS | +19.2% | +21.6% | +19.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Robert Half's June quarter answered a question nobody in staffing thought to ask: which half of the company is actually broken. It was the half that does not sell labour. Protiviti — the consulting arm that does internal audit, risk, regulatory-compliance and technology project work — saw revenue fall 4.9% to $471m, on billable hours down 19.9% against average hourly bill rates up 15.0%. The staffing side steadied. Contract talent gross margin held at 39.1% of applicable revenue, unchanged from a year earlier, and permanent placement revenue grew 2.9% to $118m, with the average fee per placement up 5.5% offsetting a 2.6% decline in placements.
That inverts how the business is usually read. Protiviti is 35% of Robert Half's $1.336bn of quarterly revenue and it is the reason group gross margin fell 172 basis points year over year, to 35.5%. The cause is not the hiring cycle: changes in the US financial-services regulatory environment shrank demand for the risk-and-compliance practice, now under 20% of Protiviti's revenue, and the company expects the headwind to begin easing in the first quarter of 2027. A $7m severance charge at Protiviti in the quarter cost $0.04 a share; Robert Half guided the segment's third-quarter adjusted margin back to 7–9% and group earnings growth of 8–12%.
The labour meters are the part that is working
US temporary-help services payrolls rose 6,800 in August and have increased in every month of 2026, the longest positive run for temporary staffing in nearly five years. The American Staffing Association's index showed temporary and contract employment running 5.2% above the same weeks of 2025. Staffing Industry Analysts projects the US market to grow 2.4% this year to $183.1bn after three straight annual declines — a recovery, and a modest one.
Kforce, the Tampa-based US professional staffing firm split between technology and finance-and-accounting placement, is the cleanest read on it: revenue up 4.5% to $349.3m, gross margin up to 28.1% from 27.1%, technology job orders and new assignment starts both up 18% year over year, and flex margins 120 basis points higher at 26.8%, near their 2022 peak, on a stable $90 average hourly bill rate. "The net is that we are driving disproportionately better results than the macro industry readings would suggest and the forward momentum in the business is good," chief operating officer David Kelly told investors on the July 27 call.
ManpowerGroup is the volume mirror
ManpowerGroup, which places permanent, temporary and light-industrial labour through some 2,200 offices in 75 countries, has now grown revenue for four consecutive quarters — 2.3%, 7.1%, 10.3% and 7.5% — and swung to $53.5m of net income in the June quarter from a $67.1m loss a year earlier. Its gross margin is structurally mid-teens, 16.1%, and gross profit grew only 2.2% on that 7.5% revenue gain: volume is returning at a thinner spread. France, its largest country at $1.2bn of quarterly revenue, was flat in constant currency on an average-daily basis, and Southern Europe's unit profit margin slipped 10 basis points on what the company called competitive pricing dynamics. Northern Europe grew 2% organically and returned to profit.
So the group splits on estimates, not on narrative. Consensus has ManpowerGroup earning $3.63 a share this year and $4.88 next; its trailing earnings multiple of 25.5x compresses to 15.8x forward, and it trades at 0.87x trailing gross profit, 1.27x book and 9.0x trailing EV/EBITDA — with the shares, up 48.8% over twelve months, still marginally below their 2024 year-end close. Robert Half's forward figure of 30.9x has barely moved from 34.1x trailing precisely because the estimate is falling: consensus of $1.27 for 2026 sits below the $1.33 delivered in 2025. It trades at 2.06x trailing gross profit against Kforce's 2.48x.
What the September 8 selloff did not explain
On September 8 Robert Half closed down 7.9%, ManpowerGroup 7.7% and Kforce 5.8%, alongside TriNet, Insperity and Upwork, with no company-specific development discoverable at any of them and no earnings or guidance update from ManpowerGroup. The likelier reading is a sector-level repricing of the labour cycle rather than an issuer event.
The verdict: the hiring turn these shares have been pricing since March is real, and Kforce's job orders and the temporary-help payroll run are the evidence for it. But it is a shallow turn, and only two of the three businesses are levered to it cleanly. ManpowerGroup's advance is underwritten by earnings the market expects to more than recover; Robert Half's is multiple expansion against estimates still going backwards, because a third of the company is hostage to a regulatory cycle that has nothing to do with employment. Robert Half told investors that studies so far suggest artificial intelligence is having a negligible impact on its areas of employment — the threat everyone was watching is not the one that cost it the quarter.
Protiviti's compliance work comes back when Washington writes rules again. Robert Half's own timetable puts meaningful relief in the second quarter of 2027, which is a longer wait than any hiring recovery requires.