

PC Connection's Device Revenue Grew 19.5% on 3% More Units — Price Did the Rest
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
PC Connection posted the best quarter in its history — record gross profit of $157.5m and a record 5.2% operating margin — on almost no additional volume. Notebooks, mobility and desktops brought in 19.5% more revenue on 3% unit growth, and the extra dollars came from device prices inflating with memory costs upstream.
That matters now because the input is decelerating: TrendForce expects conventional DRAM contract prices up 13-18% quarter over quarter in the third quarter, a slowdown from earlier jumps. Connection is the most expensive of the three enterprise IT distributors on price-to-gross-profit at 3.74x trailing, with the slowest gross-profit growth of the group — up 6.4% on a trailing-four-quarter basis against Arrow's 25.3%. Its trailing free-cash-flow yield is 1.6%, against roughly 8% at both Arrow and Insight.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CNXN | PC Connection | Enterprise IT Solutions | 🌱 Emerging Bull | +0.1% | +33.3% |
ARW | Arrow Electronics | Enterprise IT Solutions | 🟢 Cont. Bull | +7.3% | +72.2% |
NSIT | Insight Enterprises | Enterprise IT Solutions | 🌱 Emerging Bull | +4.9% | +24.1% |
| Compared against · context, not the story | |||||
AVT | Avnet | Component & Specialty Distribution | 🟢 Cont. Bull | −3.1% | +78.2% |
SNX | TD Synnex | Broad IT Infrastructure | 🟢 Cont. Bull | +1.8% | +76.1% |
SCSC | ScanSource | Component & Specialty Distribution | 🌱 Emerging Bull | +6.1% | +34.0% |
CDW | CDW | IT Infrastructure & Operations | 🌱 Emerging Bull | +5.6% | −13.7% |
INGM | Ingram Micro | IT Infrastructure & Operations | 🟢 Cont. Bull | +1.0% | +40.8% |
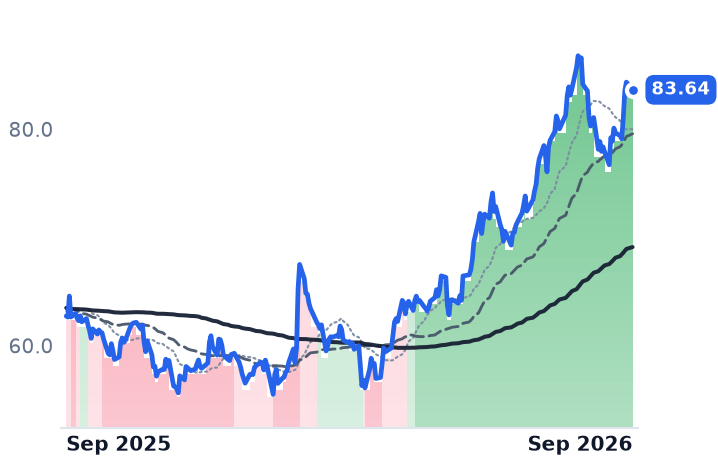
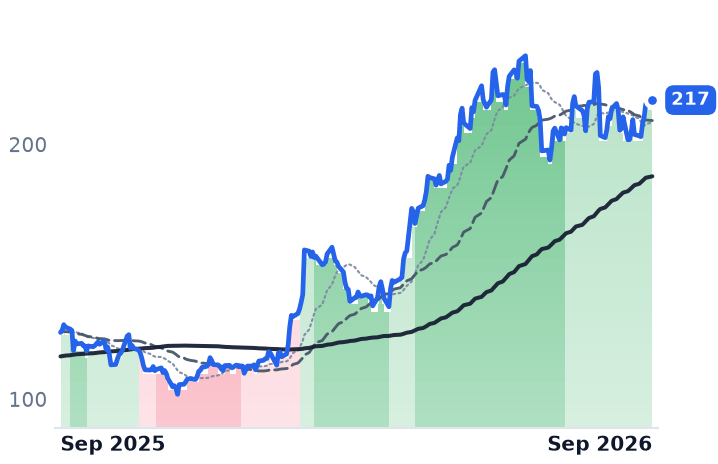
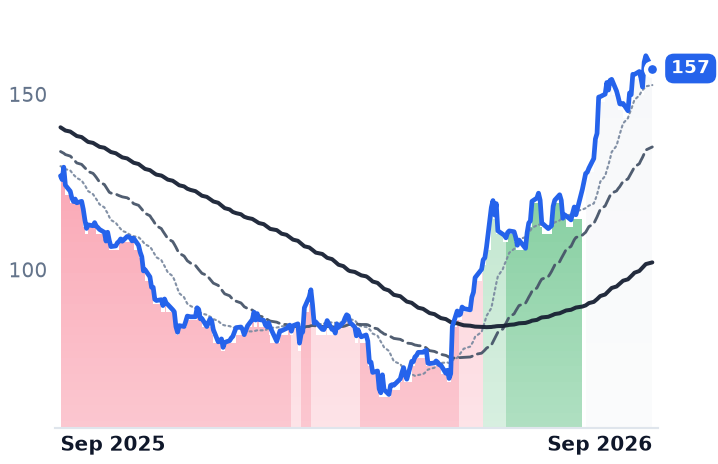
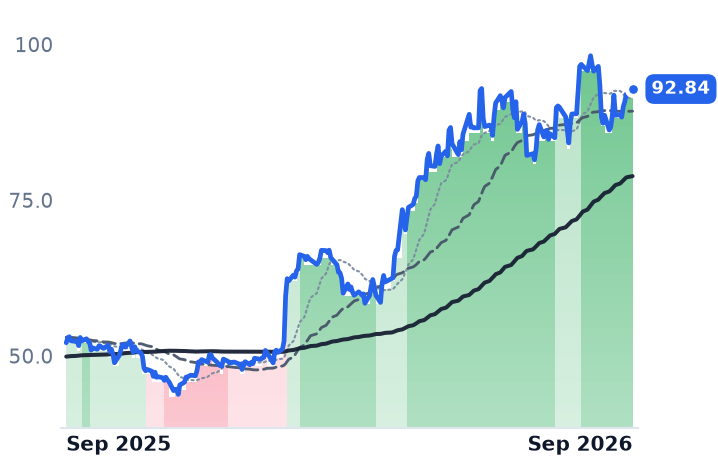
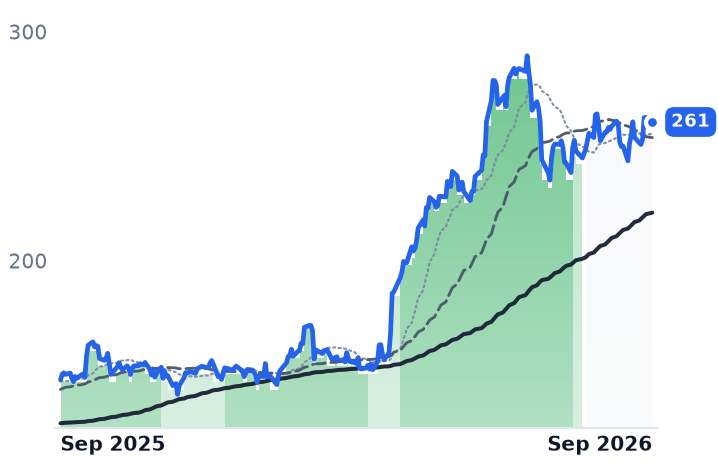
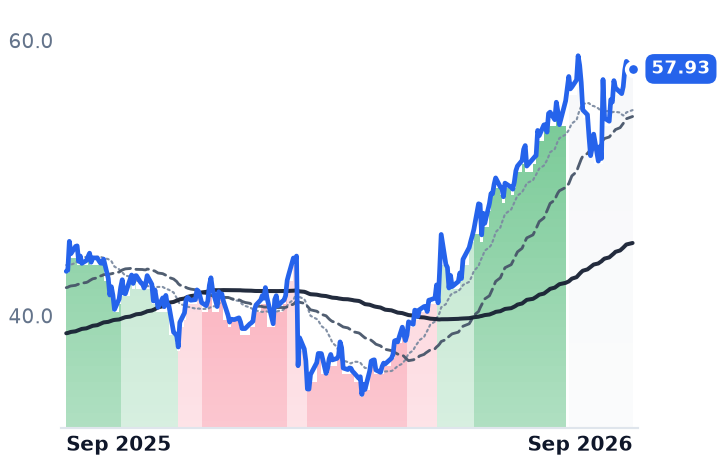
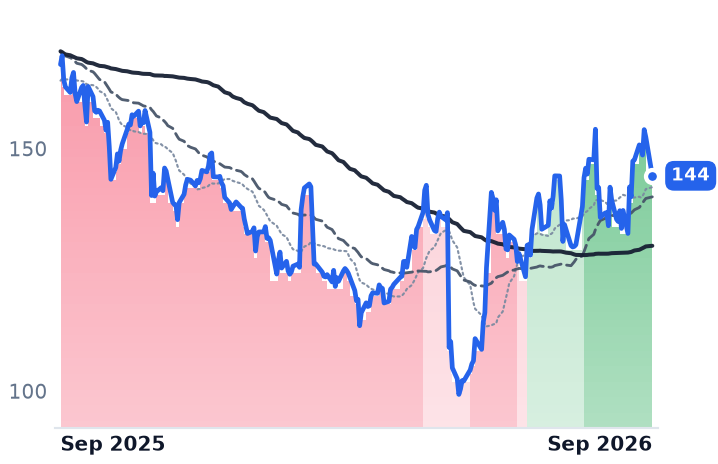
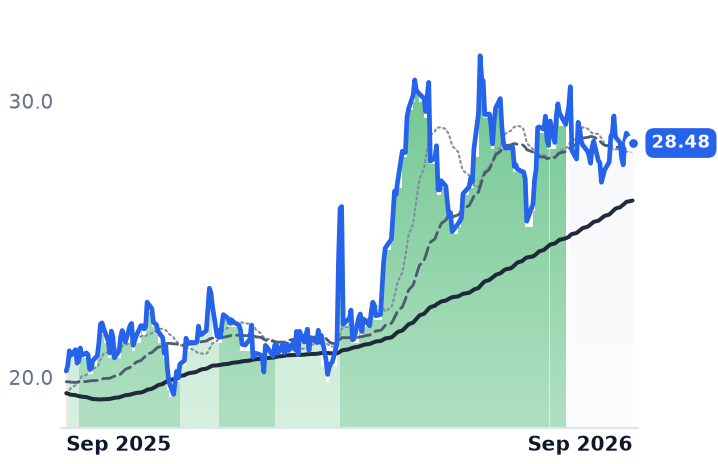
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CNXN | $2.1B | 22.1x | 20.0x | 0.7x | 0.7x | 3.7x | 3.6x | 13.9x | 1.6% |
ARW | $11.1B | 13.8x | 10.0x | 0.3x | 0.3x | 2.8x | 2.5x | 10.2x | 8.1% |
NSIT | $4.8B | 23.0x | 12.6x | 0.6x | 0.5x | 2.5x | 2.4x | 12.9x | 8.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AVT | $6.9B | 32.2x | 16.4x | 0.3x | 0.3x | 2.6x | 2.5x | 12.6x | 0.5% |
SNX | $20.0B | 17.8x | 13.2x | 0.3x | 0.3x | 4.2x | 3.9x | 10.6x | 1.9% |
SCSC | $855.9M | 12.2x | 10.7x | 0.3x | 0.3x | 2.1x | 2.1x | 5.8x | 14.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CDW | $18.9B | 17.7x | 13.5x | 0.8x | 0.8x | 3.8x | 3.6x | 13.4x | 5.9% |
INGM | $6.3B | 14.8x | 8.0x | 0.1x | 0.1x | 1.7x | 1.6x | 7.5x | -3.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CNXN | Revenue | +7.0% | +2.4% | — |
| EPS | +22.8% | +6.9% | — | |
ARW | Revenue | +32.1% | +7.6% | +7.9% |
| EPS | +109.8% | +12.5% | +10.8% | |
NSIT | Revenue | +6.7% | +3.8% | +6.2% |
| EPS | +28.5% | +6.0% | +16.6% | |
AVT | Revenue | +22.2% | +14.3% | +9.6% |
| EPS | +52.1% | +54.9% | +11.8% | |
SNX | Revenue | +20.5% | +7.0% | +8.9% |
| EPS | +44.9% | +12.9% | +15.9% | |
SCSC | Revenue | +2.6% | +3.9% | +3.8% |
| EPS | +12.9% | +13.9% | +20.3% | |
CDW | Revenue | +8.9% | +3.7% | +2.8% |
| EPS | +10.5% | +9.2% | +8.9% | |
INGM | Revenue | +11.6% | +3.5% | +4.3% |
| EPS | +19.9% | +10.6% | +11.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
PC Connection shipped roughly the same number of notebooks and desktops in the June quarter that it shipped a year earlier, and billed almost a fifth more for them. Endpoint device revenue — notebooks, mobility and desktops — rose 19.5% while units grew 3%. The gap is price, and the price is being set several links upstream, in the memory market.
That makes the company's best-ever quarter a bet on an input it does not control. On September 7, the memory researcher TrendForce had conventional DRAM contract prices rising 13-18% quarter over quarter in the third quarter, a deceleration from earlier quarters' far larger increases, with NAND up 10-15%. Several U.S. cloud providers have signed long-term agreements that cap what they pay, which concentrates the escalation on the channel's smaller buyers — the small and mid-sized businesses, schools and government agencies that Connection sells to.
A record quarter built on average selling prices
Connection, a Merrimack, New Hampshire reseller that sells hardware, software and networking gear plus design and deployment services through Business Solutions, Enterprise Solutions and Public Sector divisions, grew second-quarter net sales 12.4% to $854.0m. Gross profit set a record at $157.5m, up 14.3%, and operating income rose 44.3% to $44.6m for a record 5.22% operating margin. Underneath, Business Solutions gross margin contracted 50 basis points to 23% precisely because of the endpoint-device mix — the fast-growing line is the thinner one.
The cash statement is where the strain shows. The quarter absorbed $61.5m of inventory build and $80.6m of receivables build, the latter because 40% of quarterly revenue landed in June around Microsoft's fiscal year-end. Connection's trailing free-cash-flow yield is 1.61%. Management expects roughly $150m of that inventory to come down by year-end as it is deployed to customers, and quantified mid-single-digit customer pull-ins ahead of announced price increases. The balance sheet remains unlevered — $340.7m of cash and short-term investments, the dividend raised to $0.27 a share from $0.20, $81.2m of buyback authorization left. Enterprise Solutions ended the quarter with a record backlog, Business Solutions backlog at a three-year high, and Connection won Dell's 2026 North America Channel Partner of the Year.
What the other two are selling
Arrow Electronics, which distributes semiconductors and passive components to manufacturers and sells data-center infrastructure through a second arm, grew gross profit 32.6% in the June quarter with book-to-bill above 1 in all three regions and backlog building into the first half of 2027. Asked where the cycle stands, interim chief executive William F. Austen told investors on the August 6 call that "the starting pitcher is still in the game, they have not gone to the relief pitcher yet, and they are in the second inning, somewhere in that range." Arrow trades at 2.76x trailing gross profit and just under 10x forward earnings. Insight Enterprises, which builds and manages IT estates for corporate departments, grew gross profit 17.9% with cloud gross profit up 39% to $171m and core services up 21% — annuity-shaped dollars — and is the cheapest of the three at 2.51x trailing gross profit against 12.6x forward earnings. Connection is the most expensive on that meter, 3.74x trailing and 3.59x forward, with the narrowest trailing-to-forward earnings gap, 22.1x to 20.0x.
The part the business earns
Connection's shares have gone nowhere for a month, off 0.6% while Arrow rose 6.8% and Insight 5.4%, and it is now the only one of the three whose 50-day average still sits above its 200-day; Arrow's crossed down in mid-July and Insight's in late July. Over twelve months Connection is up 32.2%, and the decomposition is unflattering: trailing-four-quarter gross profit grew 6.4%, while price-to-gross-profit expanded from roughly 3.04x to 3.74x. Nearly all of the year's re-rating is multiple, on the weakest gross-profit growth in the group.
The operating discipline is real and earned — a record margin on a 14% gross-profit quarter is no accounting effect. What the business does not yet explain is the multiple, because the growth driving it is device price inflation that reverses when memory normalizes, while Arrow's rests on a components backlog and Insight's on recurring cloud and services. CDW, roughly three times Insight's size and chasing the same corporate wallet, fell 12% in August on record sales as memory inflation ate its margin. That squeeze has so far passed through Connection rather than into it.
Connection reports third-quarter results on October 28, and expects roughly $150m of inventory to leave the warehouse by year-end. Whether it leaves at the prices it was bought at is the memory market's decision, not Connection's.