

Michael Kors Raises Outlet Prices 5-10%; Coach Ran That Play and Won Gen Z
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Both American accessible-luxury houses are now running the same maneuver — pull handbags out of off-price channels so the full-price customer pays more — but one started years earlier and is winning on it. Coach lifted handbag average unit retail at a mid-teens rate in fiscal 2026 with units up low double digits alongside it, carrying Tapestry's gross margin to 77.8% from 75.4%. Capri is only now raising Michael Kors outlet prices, having shrunk June-quarter revenue to $769m, and has told investors to expect negative full-price comparable sales while it takes a final step back from clearance.
The market has repriced both regardless. Tapestry's fall has continued for a month after the news that caused it, in company with an apparel complex that dropped in near-unison; Capri's forward earnings recovery rests on cost cuts against consensus revenue that still falls.
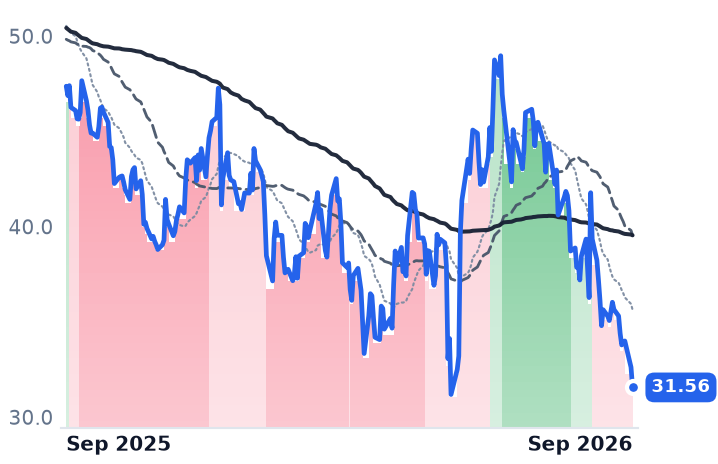
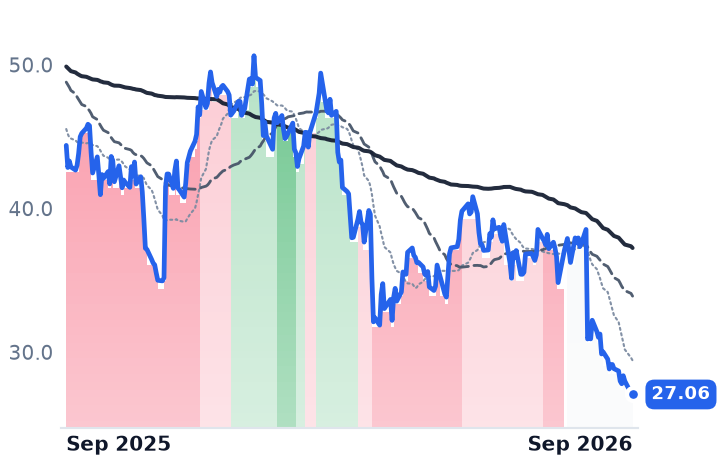
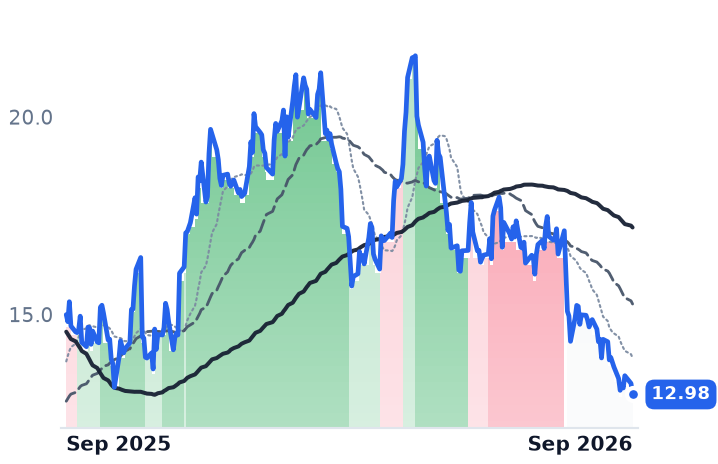
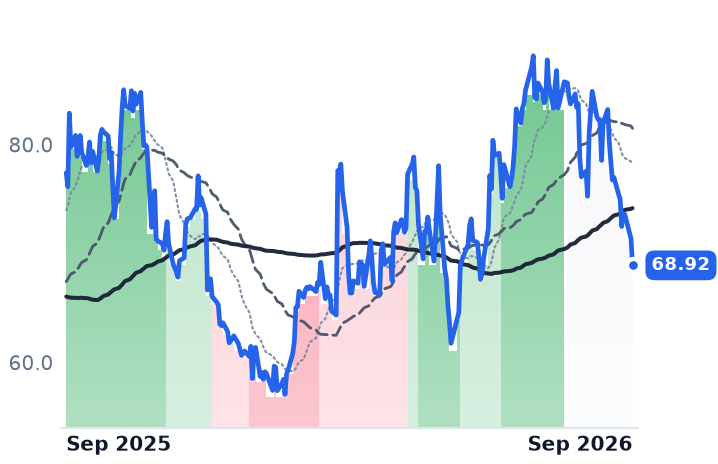
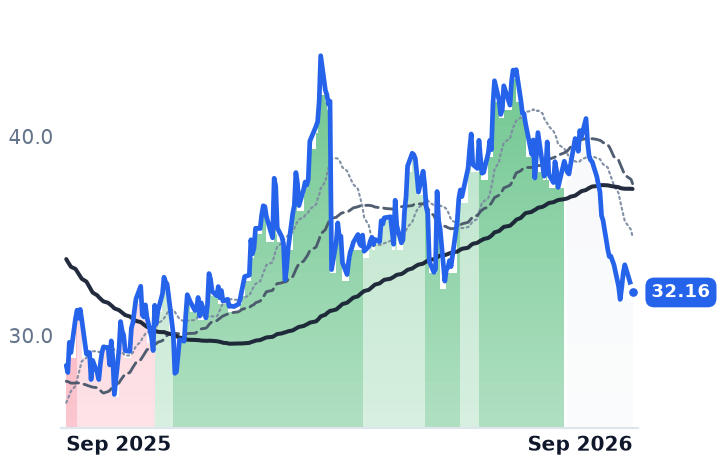
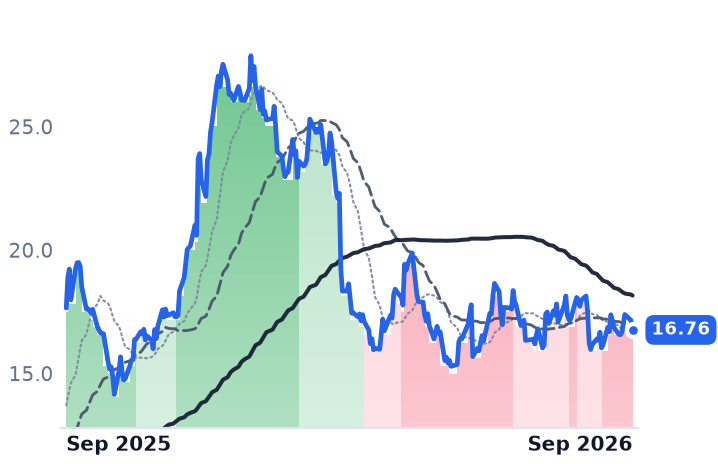
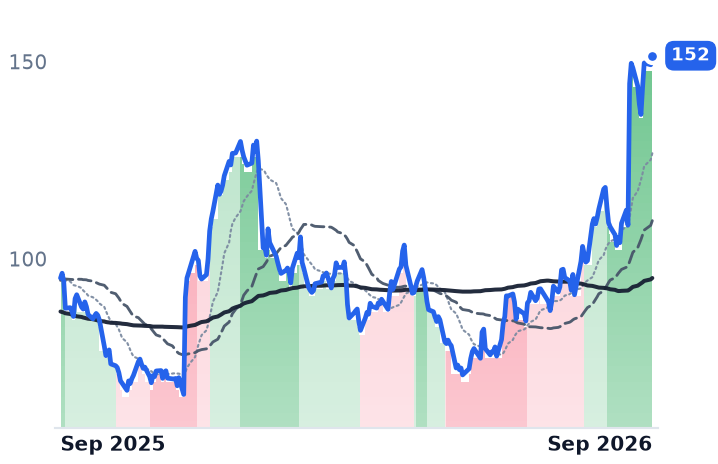
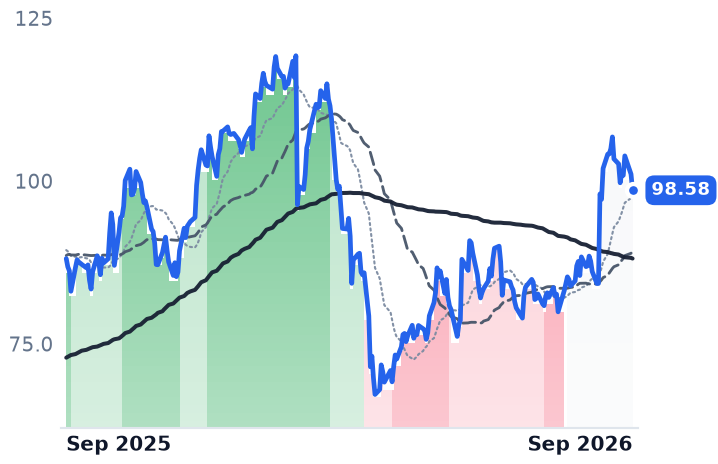
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
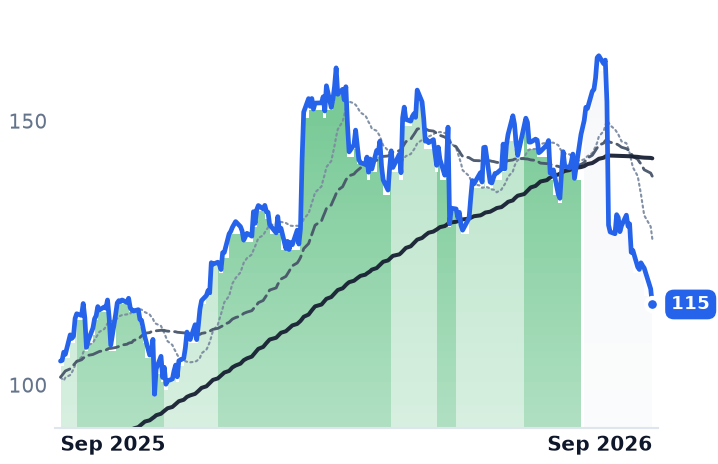
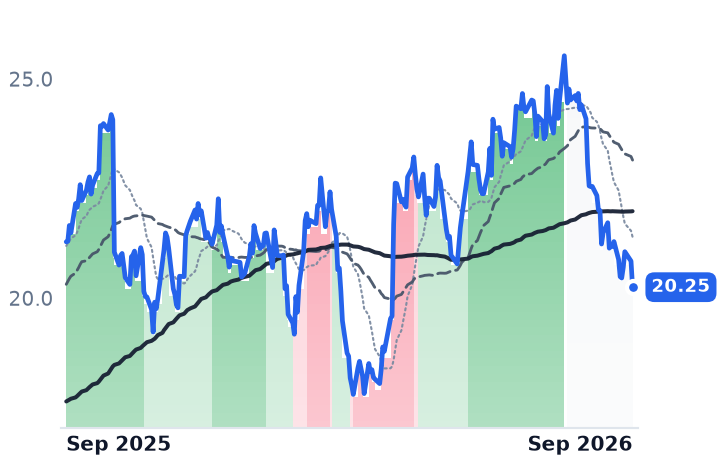
TPR | Tapestry | Handbags & Accessories | 🟢 Cont. Bull | −28.3% | +10.3% |
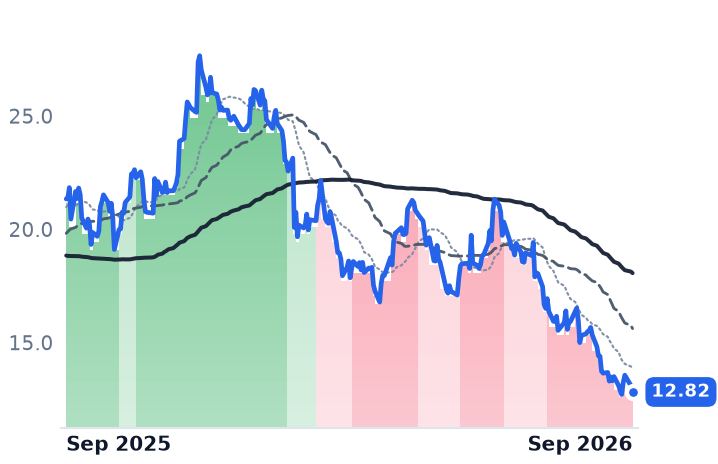
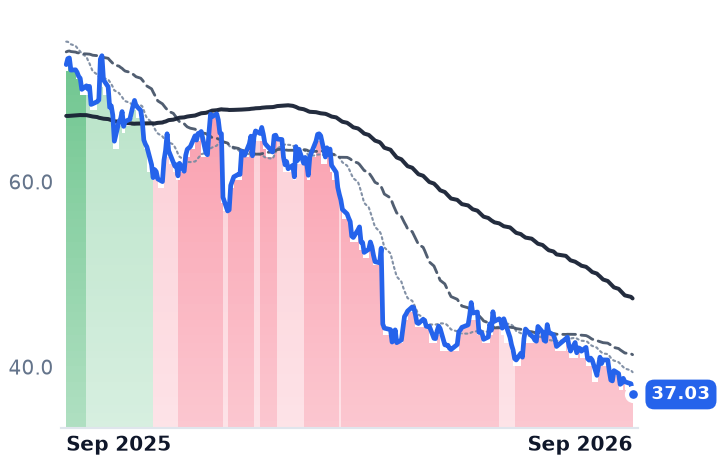
CPRI | Capri | Handbags & Accessories | ⚠️ Emerging Bear | −16.7% | −39.9% |
| Compared against · context, not the story | |||||
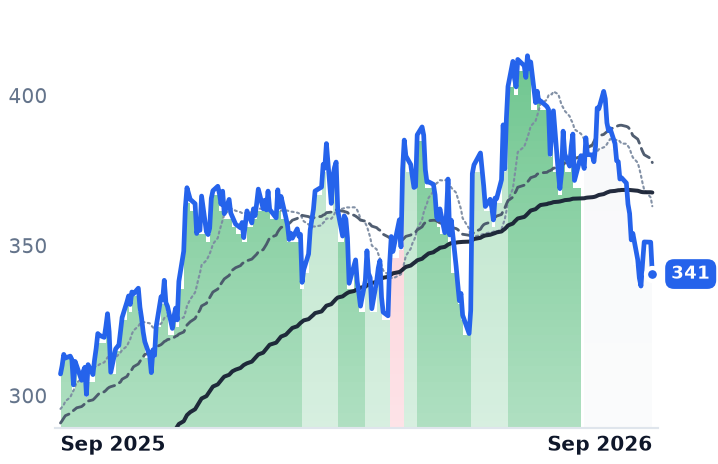
RL | Ralph Lauren | Premium Lifestyle | 🟢 Cont. Bull | −15.2% | +10.8% |
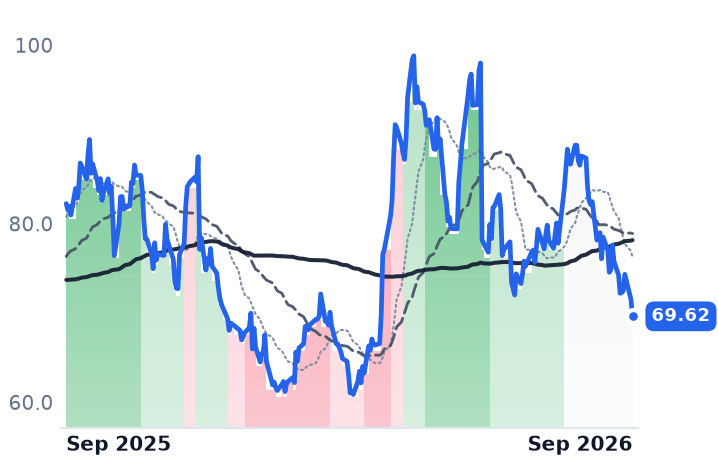
PVH | PVH | Premium Lifestyle | 🟢 Cont. Bull | −20.3% | −15.4% |
LEVI | Levi Strauss | Denim & Casual | 🟢 Cont. Bull | −15.9% | −4.9% |
NKE | NIKE | Athletic & Performance | 🔴 Cont. Bear | −12.1% | −49.0% |
LULU | Lululemon Athletica | Athletic & Activewear | 🔴 Cont. Bear | −21.8% | −40.0% |
DECK | Deckers Outdoor | Premium Lifestyle Footwear | 🌱 Emerging Bull | −16.6% | −30.5% |
BIRK | Birkenstock | Premium Lifestyle Footwear | 🔴 Cont. Bear | −19.8% | −33.4% |
ONON | On | Athletic & Activewear | 🔴 Cont. Bear | −29.8% | −39.1% |
VFC | V.F | Outdoor & Adventure | ⚠️ Emerging Bear | −13.4% | −13.5% |
KTB | Kontoor Brands | Denim & Casual | 🌱 Emerging Bull | −11.2% | −11.0% |
CRI | Carter's | Childrenswear | 🟢 Cont. Bull | −21.4% | +12.9% |
AEO | American Eagle Outfitters | Specialty Apparel | ⚠️ Emerging Bear | −7.6% | −5.0% |
ANF | Abercrombie & Fitch | Specialty Apparel | 🌱 Emerging Bull | +28.7% | +59.3% |
EL | The Estée Lauder Companies | Beauty & Personal Care | ⚠️ Emerging Bear | +13.5% | +11.9% |
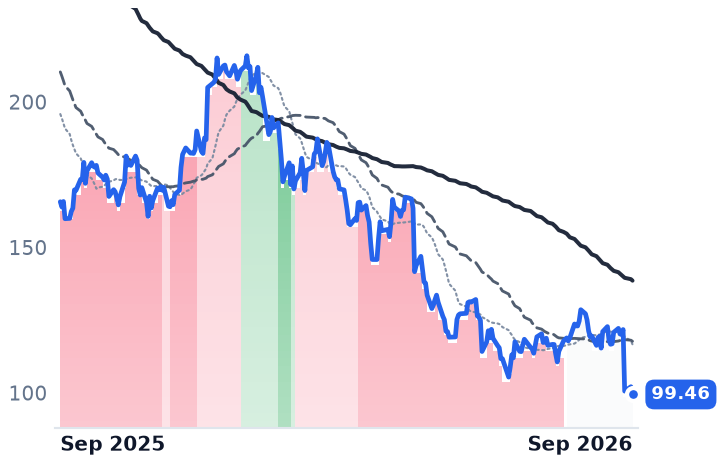
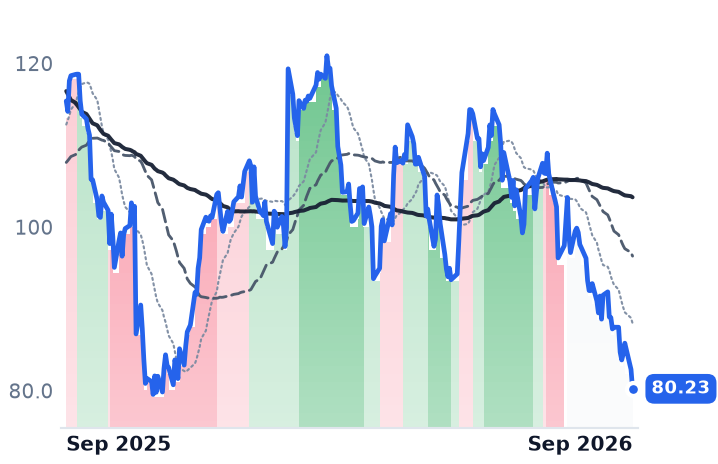
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TPR | $23.0B | 15.2x | 14.2x | 2.9x | 2.7x | 3.7x | 3.4x | 12.2x | 7.9% |
CPRI | $1.5B | 10.1x | 6.0x | 0.4x | 0.4x | 0.7x | 0.7x | 11.5x | 5.7% |
RL | $20.8B | 21.2x | 18.0x | 2.5x | 2.4x | 3.5x | 3.4x | 14.9x | 5.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PVH | $3.6B | 148.5x | 6.6x | 0.4x | 0.4x | 0.7x | 0.7x | 11.0x | 14.8% |
LEVI | $8.3B | 13.2x | 14.0x | 1.3x | 1.2x | 2.1x | 2.0x | 10.1x | 5.9% |
NKE | $61.9B | 27.5x | 28.1x | 1.3x | 1.3x | 3.3x | 3.3x | 19.9x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LULU | $14.0B | 9.0x | 9.7x | 1.3x | 1.2x | 2.2x | 2.2x | 5.1x | 6.6% |
DECK | $11.2B | 11.7x | 11.0x | 2.0x | 1.9x | 3.5x | 3.3x | 7.3x | 10.7% |
BIRK | $6.0B | 15.2x | 16.4x | 2.3x | 2.5x | 4.1x | 4.6x | 9.3x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ONON | $12.4B | 38.5x | 26.1x | 3.1x | 3.4x | 4.9x | 5.3x | 22.1x | 3.1% |
VFC | $5.2B | 18.8x | 12.3x | 0.5x | 0.5x | 1.0x | 1.0x | 11.7x | 11.2% |
KTB | $3.4B | 12.3x | 11.5x | 1.1x | 1.2x | 2.3x | 2.5x | 10.1x | 11.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRI | $1.2B | 13.1x | 10.4x | 0.4x | 0.4x | 0.9x | 0.9x | 7.0x | 10.3% |
AEO | $2.5B | 13.5x | 8.7x | 0.5x | 0.4x | 1.4x | 1.3x | 7.4x | 1.0% |
ANF | $3.2B | 6.4x | 6.6x | 0.6x | 0.6x | 1.0x | 1.0x | 4.1x | 11.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EL | $29.0B | n/m | 33.1x | 2.0x | 1.9x | 2.7x | 2.6x | 21.9x | 4.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TPR | Revenue | +14.7% | +7.1% | +5.4% |
| EPS | +37.4% | +14.1% | +11.7% | |
CPRI | Revenue | −20.8% | −2.2% | +2.5% |
| EPS | +38.9% | +51.2% | +18.4% | |
RL | Revenue | +13.6% | +8.8% | +5.3% |
| EPS | +35.1% | +15.9% | +11.0% | |
PVH | Revenue | +3.0% | +1.6% | +1.8% |
| EPS | −6.6% | +10.9% | +12.1% | |
LEVI | Revenue | +7.5% | +4.9% | +6.0% |
| EPS | +13.0% | +12.0% | +15.6% | |
NKE | Revenue | +0.7% | +0.6% | +4.4% |
| EPS | −30.5% | +22.1% | +28.6% | |
LULU | Revenue | +4.7% | +3.9% | +4.5% |
| EPS | −9.1% | −5.7% | +7.7% | |
DECK | Revenue | +9.4% | +8.2% | +7.4% |
| EPS | +16.1% | +9.3% | +10.9% | |
BIRK | Revenue | +13.7% | +14.0% | +13.1% |
| EPS | +15.9% | +23.4% | +18.5% | |
ONON | Revenue | +21.3% | +20.3% | +23.9% |
| EPS | +101.7% | +23.3% | +26.4% | |
VFC | Revenue | −2.4% | +1.9% | +3.1% |
| EPS | +12.1% | +29.2% | +24.3% | |
KTB | Revenue | +19.4% | −9.7% | +4.2% |
| EPS | +13.2% | −2.7% | +21.4% | |
CRI | Revenue | +2.6% | +4.4% | +1.3% |
| EPS | −37.8% | −2.7% | +12.1% | |
AEO | Revenue | +2.8% | +5.6% | +3.4% |
| EPS | −19.0% | +28.1% | +12.0% | |
ANF | Revenue | +6.8% | +3.9% | +3.8% |
| EPS | −7.7% | +8.9% | +9.6% | |
EL | Revenue | +4.5% | +4.1% | +4.4% |
| EPS | +63.1% | +30.8% | +21.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Two weeks ago Tapestry's fiscal 2027 guidance broke its stock in a single session. What has happened since is the part worth returning for: the shares kept falling for another month without new company news, and the last big American accessible-luxury brand still shipping heavily into off-price began copying the move that made Coach work.
Capri Holdings, which owns Michael Kors and Jimmy Choo after selling Versace to Prada for $1.375bn, is raising outlet prices 5 to 10% starting in August and September and taking what management calls a final step back from clearance and markdown inventory in the September quarter. That is the mechanism this corner of retail actually runs on. Handbags priced $250 to $500 have grown from 63% to 70% of global volume in three years, and inside that band earnings are not units sold but the price a full-price customer will pay — which only rises if the same bag stops appearing discounted somewhere else.
Coach proved it; the numbers are on the page
Tapestry, the Coach, Kate Spade and Stuart Weitzman owner run by chief executive Joanne Crevoiserat, spent years withdrawing product from outlets and wholesale doors. Fiscal 2026 revenue rose 14.2% to $8.00bn, gross margin reached 77.8% against 75.4%, and diluted earnings per share came in at $7.27 against $0.82 the year before. Coach handbag average unit retail rose at a mid-teens rate for the year on reduced promotion — and, against the usual objection that price is bought with volume, full-year units rose low double digits too. "You are going to continue to see AUR gains across the globe, and you will also see unit gains," Coach chief executive Todd Kahn said on the August 13 call, per transcript coverage. Bain's 2026 luxury report has Coach ranking first in brand preference among 18-to-27-year-olds; Michael Kors has slipped from first to fourth with that group since 2020.
The cost of the discipline is visible. Tapestry closed 64 directly operated stores in fiscal 2026, 40 of them Kate Spade, and guides Kate Spade to a high-single-digit revenue decline after a $27.2m adjusted operating loss. Its leather goods are made in Vietnam, Cambodia and India, so the guide also carries a mid-20% assumed tariff rate on US receipts — a line that is itself unsettled, since the Supreme Court struck down the emergency-powers tariffs in February.
Capri is attempting it from behind
Michael Kors revenue fell 7.1% to $590m in the June quarter, roughly $50m of that a deliberate reduction of markdown inventory; group inventory is down 20% year over year, Michael Kors down 25%, and gross margin improved to 65.0% from 59.2%. Jimmy Choo, at $179m, grew 10.5%. "There's been 3 years, 4 years of decline in that business, and we're finally starting to see that turn," chairman and chief executive John Idol said of the wholesale channel on the August 5 call. The balance sheet was fixed by the asset sale rather than by trading: "we ended the quarter with cash of $114 million and debt of $338 million, resulting in net debt of $224 million, down from approximately $1.5 billion last year," chief financial and operating officer Tyler Reddien told investors the same day.
What the shares did, and what it means
Tapestry has fallen 11.5% in the eighteen sessions since the earnings gap, to $115.25, a 29.0% drawdown from its August 7 high. But roughly half the month belongs to the group: over the same window On Holding fell 29.8%, Lululemon 21.8% after its early-September guidance cut, PVH 20.3% and Nike 12.1%, a median near 16%. Abercrombie & Fitch and Estée Lauder rose. Capri touched a 52-week low of $12.71 on September 2.
The first leg of Tapestry's fall was earned — a fiscal 2027 guide of $8.4bn to $8.5bn implies roughly 5.6% growth against 14.2% delivered, and a halved growth rate is worth a lower multiple. At 14.25x forward earnings against 15.18x trailing, versus about 20.6x forward in early August, that repricing has been done and then some, on a company retiring $3bn of stock — about 13% of its $23.0bn market value — through fiscal 2028. Capri, at 5.98x forward against 10.12x trailing, is cheap for a reason its own consensus states: earnings up 51% while revenue falls 2.2%. Because gross margins differ by 13 points, the comparison that travels is price against gross profit, where Capri trades at 0.69x and Tapestry at 3.69x. One of those discounts is a business shrinking into cost cuts; the other is a pricing engine that has not yet been shown to be broken.
Capri has already told investors to expect negative full-price comparable sales this quarter as the clearance inventory comes out. Coach absorbed exactly that cost for years before the price stuck — and it did the absorbing while it was still the brand teenagers wanted.