

Deckers and Birkenstock Raised Guidance; Lululemon Cut Its Outlook to a 5-7% Decline
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two footwear makers lifted their full-year forecasts this summer, and both stocks are worth about a third less than a year ago. Deckers reported its first billion-dollar quarter, expanded gross margin to 56.4% despite roughly 150 basis points of tariff cost, and raised fiscal 2027 earnings guidance to $7.35-$7.50 a share. Birkenstock grew 15% in constant currency and raised its targets again.
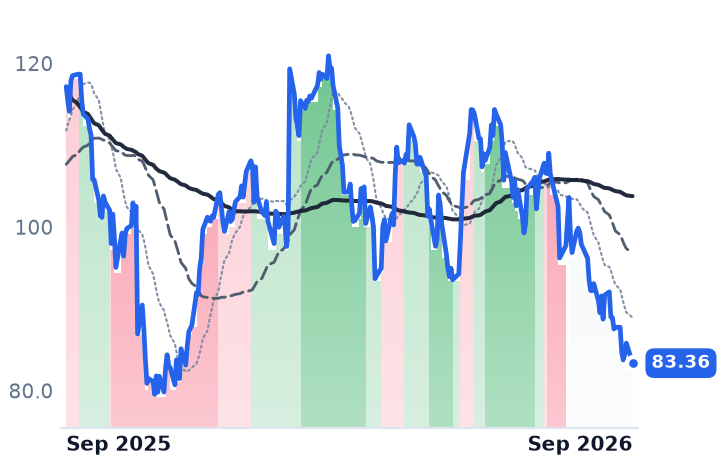
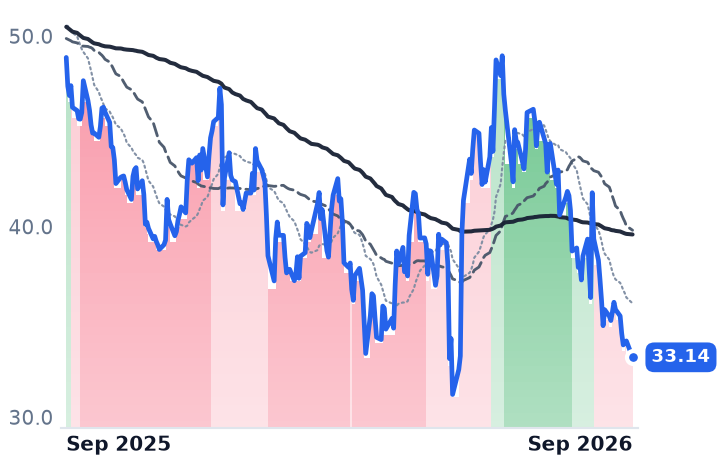
The declines have different causes. For Deckers, the entire twelve-month drop is a lower earnings multiple — 11.1 times forward earnings now against 17.0 times a year ago, on a forward estimate that rose 9.3%. For Birkenstock, the proximate event is dated: its controlling holder sold 25.5m shares on August 14. HOKA's growth halving to 7.7% is the one real business problem here, and it is not confined to Deckers.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
DECK | Deckers Outdoor | Premium Lifestyle Footwear | 🌱 Emerging Bull | −13.3% | −28.9% |
BIRK | Birkenstock | Premium Lifestyle Footwear | 🌱 Emerging Bull | −15.8% | −32.2% |
| Compared against · context, not the story | |||||
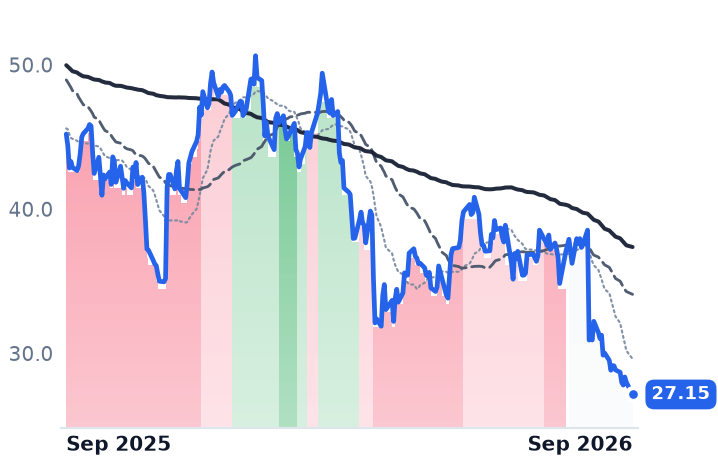
ONON | On | Athletic & Activewear | 🔴 Cont. Bear | −29.6% | −39.9% |
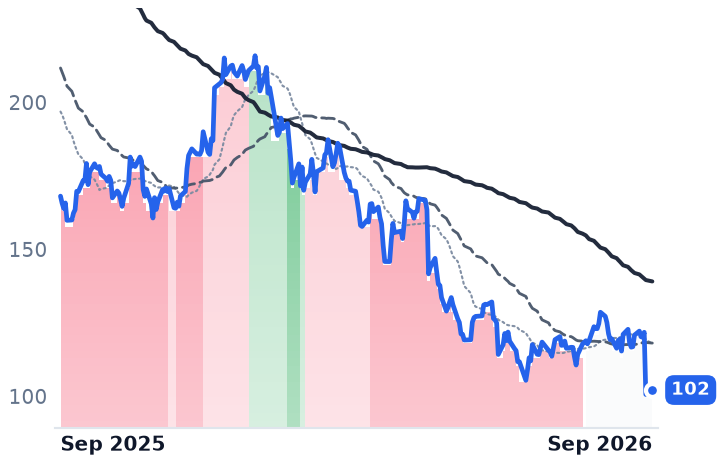
LULU | Lululemon Athletica | Athletic & Activewear | 🔴 Cont. Bear | −19.7% | −39.3% |
OXM | Oxford Industries | Premium Lifestyle | 🔴 Cont. Bear | −16.9% | −20.6% |
NKE | NIKE | Athletic & Performance | 🔴 Cont. Bear | −9.3% | −47.8% |
CROX | Crocs | Casual Lifestyle & Comfort | 🌱 Emerging Bull | −16.5% | +31.7% |
RL | Ralph Lauren | Premium Lifestyle | 🟢 Cont. Bull | −12.5% | +14.6% |
VFC | V.F | Outdoor & Adventure | ⚠️ Emerging Bear | −11.5% | −13.4% |
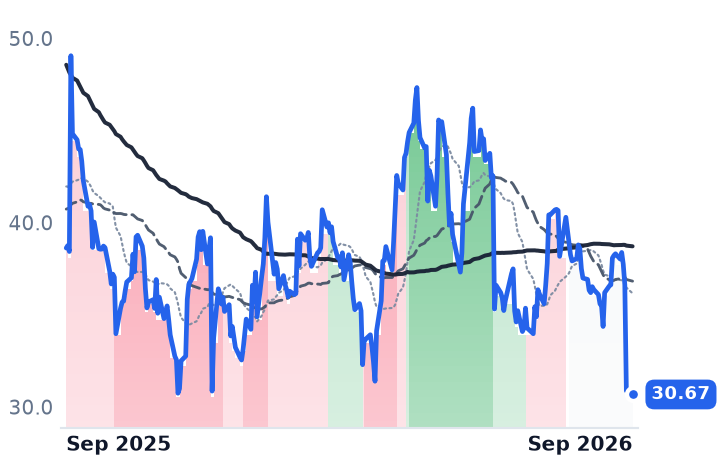
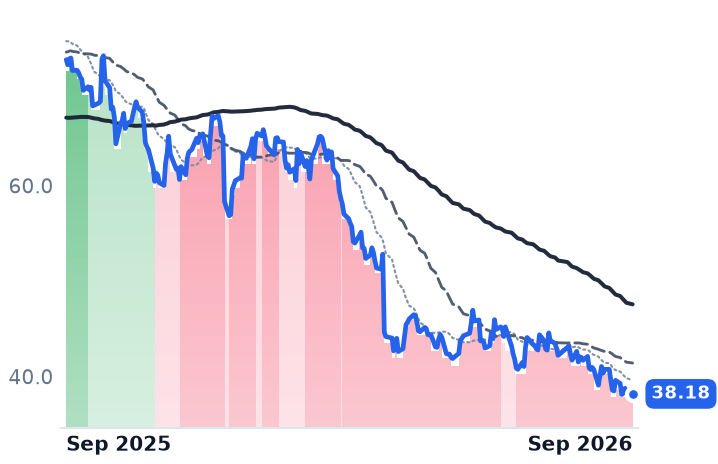
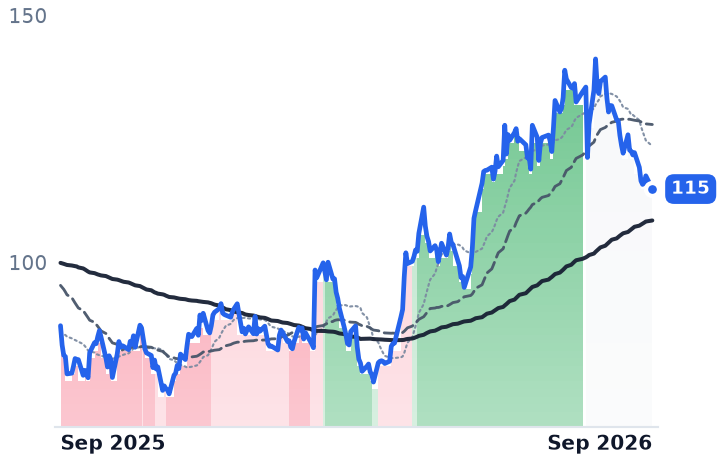
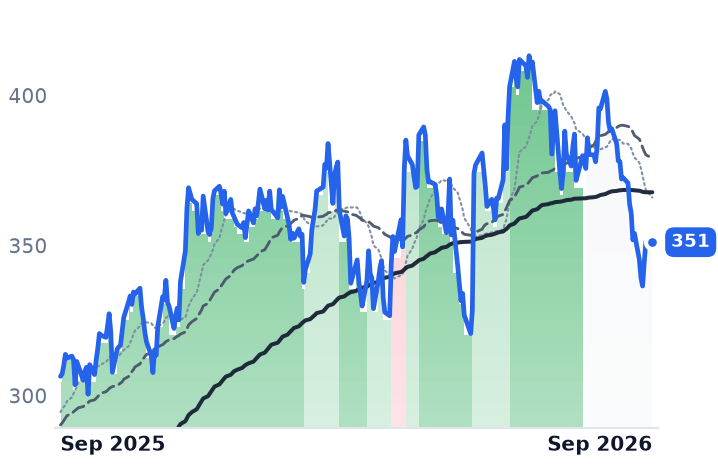
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DECK | $11.2B | 11.7x | 11.0x | 2.0x | 1.9x | 3.5x | 3.3x | 7.3x | 10.7% |
BIRK | $6.0B | 15.2x | 16.4x | 2.3x | 2.5x | 4.1x | 4.6x | 9.3x | 5.5% |
ONON | $12.4B | 38.5x | 26.1x | 3.1x | 3.4x | 4.9x | 5.3x | 22.1x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LULU | $14.0B | 9.0x | 9.7x | 1.3x | 1.2x | 2.2x | 2.2x | 5.1x | 6.6% |
OXM | $586.0M | n/m | 16.4x | 0.4x | 0.4x | 0.7x | 0.7x | 36.0x | 1.9% |
NKE | $61.9B | 27.5x | 28.1x | 1.3x | 1.3x | 3.3x | 3.3x | 19.9x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CROX | $4.7B | n/m | 7.0x | 1.2x | 1.2x | 2.0x | 2.0x | 6.7x | 14.2% |
RL | $20.8B | 21.2x | 18.0x | 2.5x | 2.4x | 3.5x | 3.4x | 14.9x | 5.0% |
VFC | $5.2B | 18.8x | 12.3x | 0.5x | 0.5x | 1.0x | 1.0x | 11.7x | 11.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DECK | Revenue | +9.4% | +8.2% | +7.4% |
| EPS | +16.1% | +9.3% | +10.9% | |
BIRK | Revenue | +13.7% | +14.0% | +13.1% |
| EPS | +15.9% | +23.4% | +18.5% | |
ONON | Revenue | +21.3% | +20.3% | +23.9% |
| EPS | +101.7% | +23.3% | +26.4% | |
LULU | Revenue | +4.7% | +3.9% | +4.5% |
| EPS | −9.1% | −5.7% | +7.7% | |
OXM | Revenue | −2.3% | +2.0% | +2.6% |
| EPS | −66.2% | +7.4% | +26.0% | |
NKE | Revenue | +0.7% | +0.6% | +4.4% |
| EPS | −30.5% | +22.1% | +28.6% | |
CROX | Revenue | +1.7% | +2.5% | −0.9% |
| EPS | +12.4% | +6.4% | +0.2% | |
RL | Revenue | +13.6% | +8.8% | +5.3% |
| EPS | +35.1% | +15.9% | +11.0% | |
VFC | Revenue | −2.4% | +1.9% | +3.1% |
| EPS | +12.1% | +29.2% | +24.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Two premium footwear makers raised their full-year forecasts this summer while the apparel companies around them were cutting. Deckers Outdoor, which sells UGG sheepskin boots and HOKA performance running shoes through wholesale doors and its own stores, lifted fiscal 2027 earnings guidance to $7.35-$7.50 a share on July 23. Three weeks later Birkenstock, the German sandal maker founded in 1774 that manufactures in its own plants, raised its revenue and profit targets for the year.
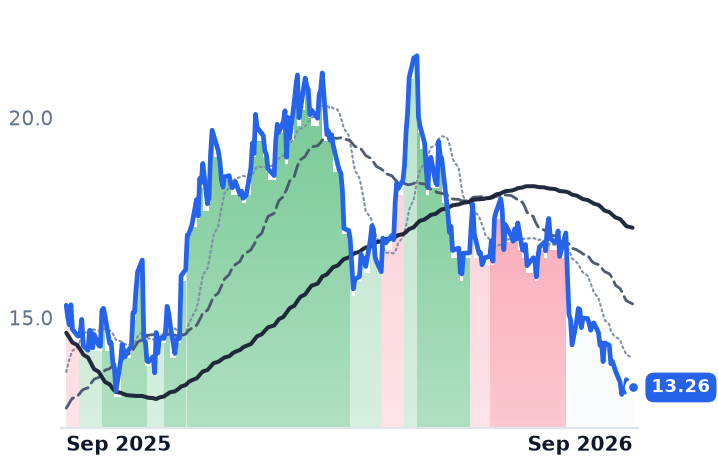
Since those reports Deckers has fallen 18.6% and Birkenstock 20.7% from its post-earnings close. Over twelve months the two are down 28.9% and 32.2%. The reason that is worth taking apart is that the two declines have almost nothing in common: one is a pure re-pricing of unchanged earnings, and the other traces to a single day when a private-equity owner sold a billion dollars of stock.
Deckers: better margins, cheaper stock
Deckers' June quarter took revenue above $1bn for the first time, up 5.7%, with HOKA at $704m and UGG at $278m. Direct-to-consumer revenue rose 13% while wholesale grew 2.2%, and inventories fell 5% to $807.6m — no build ahead of the holiday quarter that decides UGG's year. Gross margin expanded 64 basis points to 56.4% even though tariffs cost roughly 150 basis points and the company lifted its assumed duty rate to 12.5% from 10%. That rate is not hypothetical: Section 122 duties expired on July 24 and were replaced the same day by a two-tier Section 301 forced-labor tariff on top of a 12.5% base rate, and Vietnam alone shipped 274 million pairs to the United States in 2024.
"Both HOKA and UGG maintained solid momentum and continued to capture high level of full price consumer demand," chief executive Stefano Caroti said on the July 23 call.
The honest problem is HOKA: growth halved to 7.7% from 14.5% the prior quarter, and Bank of America cut its price target to $115 from $120 citing moderating HOKA sales and more discounting. But the nearest rival slowed in the same three months. On Holding, the Swiss running brand, missed on second-quarter sales and cut full-year growth guidance to the low-20% range from at least 23%, and its shares fell as much as 22% to a two-year low. Performance running decelerated; HOKA did not lose to On.
Against that, the arithmetic of Deckers' decline is stark. A year ago the shares were $117.17 against a next-year consensus of $6.89; today they are $83.37 against $7.53. Forward earnings estimates rose 9.3% and the multiple fell 35%, from 17.0 times to 11.1. Consensus still sits above the company's own guidance range.
Birkenstock: the seller, not the business
Birkenstock's June quarter grew 15% in constant currency to EUR 720m, direct-to-consumer sales outgrew wholesale for the first time in two years, and own retail rose 50% as store count reached 124. Growth is roughly one-third price and two-thirds pairs sold, in line with management's stated target mix, with closed-toe styles gaining 500 basis points of penetration. Adjusted gross margin of 59.2% was down 130 basis points, all of it FX and US tariffs. Capital spending of EUR 110-130m is going into production at Wittichenau, Arouca and Görlitz; net leverage is 1.8x and falling.
The shares jumped 15.2% to $41.78 on the August 13 guidance raise. "Given our currently undervalued shares, we will look for opportunities to continue our buybacks," chief executive Oliver Reichert told investors that day. The next morning, an affiliate of L Catterton priced 25,523,226 shares at $39.35, about 4% below the prior close, with an option on 3.8m more; Birkenstock received nothing and simultaneously repurchased 12.8m shares. Volume that day ran near five times normal. At $33.14 the stock is 15.8% below where the seller cleared.
What the apparel comparison shows
Lululemon, whose second-quarter revenue fell 4% to $2.4bn on comparable sales down 9%, cut full-year revenue guidance to a 5-7% decline and earnings to $9.48-$9.73 a share; the stock lost 17.4% in one session on September 4. Oxford Industries, owner of Tommy Bahama, also lowered its outlook. Footwear fell in the same week — Deckers 5.0%, Birkenstock 6.1% — but on forecasts moving the other way.
So: the market is treating raised guidance and cut guidance identically. Part of Deckers' de-rating is earned — a brand growing 8% against a low-double-digit full-year promise is worth less than one growing 15% — but a 35% cut to the multiple against a rising estimate is more than that gap explains. Birkenstock's is harder to defend on fundamentals at all; an accelerating, de-levering manufacturer priced at 9.3 times trailing enterprise value to earnings before interest, tax, depreciation and amortization and 1.82 times book looks like the residue of a supply event the tape has not worked through.
Deckers has told investors HOKA will grow low double digits this fiscal year, and delivered 8% in the first quarter. The holiday quarter settles both that promise and UGG's, and it is the only evidence that will change either argument.