

Hawaiian Electric Owes Three More $479m Wildfire Payments Against $238m of Cash
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Hawaiian Electric's equity is now a residual claim sitting behind a dated liability, and the market prices it at 1.09 times book value while the company's own credit rating improves. Its $1.99bn share of the $4bn Maui settlement is payable in four annual installments of $479m; the first went out in April 2026, funded from stock sold in 2024, and three more fall due each April through 2029.
The business underneath is not filling the gap. The utility earned a 6.1% return on equity against an authorized 9.5%, June-quarter core earnings fell to $0.13 a share from $0.20, and the dividend has been suspended since August 2023. A pending rate case would add $170m of base revenue phased over two years, with an interim decision expected in December.
Credit holders took the wins — two ratings upgrades, roughly $350m of approved wildfire cost recovery, insurers shut out of the settlement. Shareholders got the schedule.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
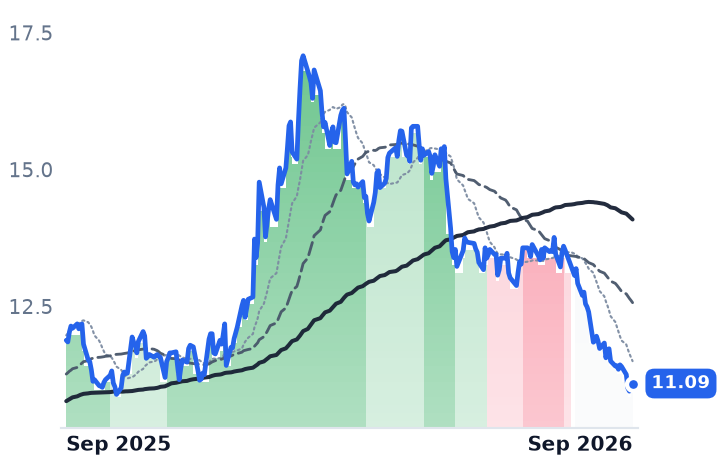
HE | Hawaiian Electric Industries | Regional/Municipal Utilities | ⚠️ Emerging Bear | −6.4% | −6.6% |
| Compared against · context, not the story | |||||
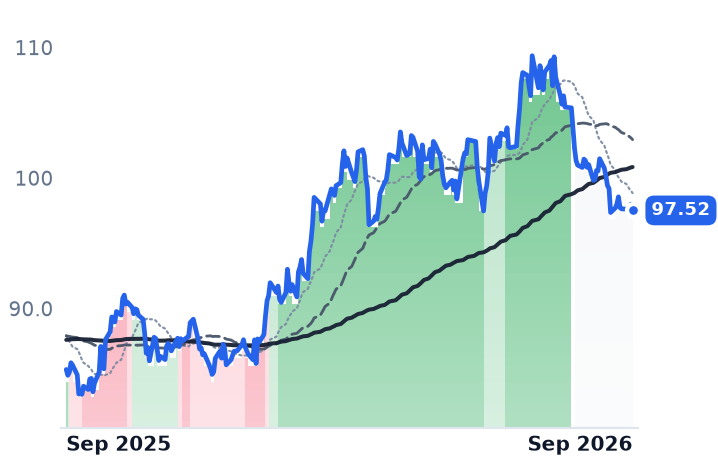
PNW | Pinnacle West Capital | Vertically Integrated Utilities | 🟢 Cont. Bull | −2.3% | +14.3% |
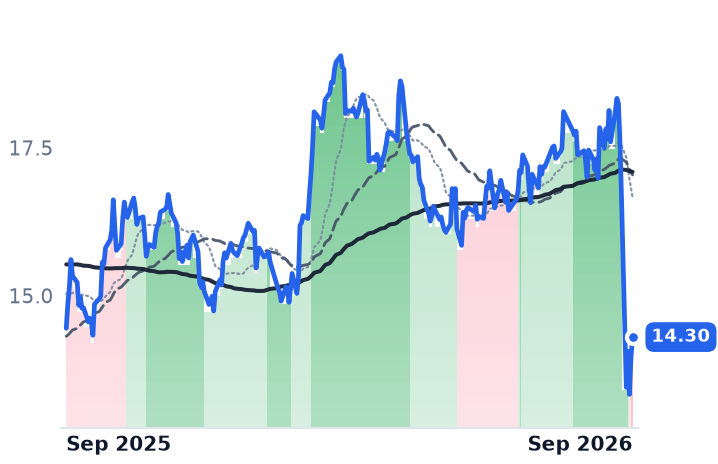
PCG | PG&E | Vertically Integrated Utilities | ⚠️ Emerging Bear | −17.3% | −1.0% |
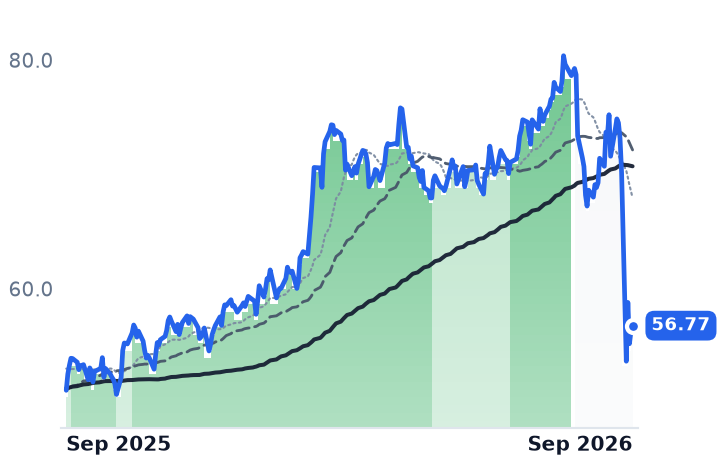
EIX | Edison International | Regional/International Utilities | 🟢 Cont. Bull | −16.5% | +11.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HE | $1.9B | 8.5x | 13.2x | 0.6x | 0.6x | 5.1x | 5.3x | 4.5x | -29.5% |
PNW | $11.9B | 18.3x | 20.8x | 2.1x | 2.2x | 3.8x | 3.9x | 10.6x | -7.4% |
PCG | $37.7B | 10.2x | 8.5x | 1.5x | 1.4x | 2.6x | 2.6x | 9.6x | -11.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EIX | $22.6B | 6.0x | 9.6x | 1.2x | 1.2x | 2.9x | 3.0x | 8.4x | -1.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
HE | Revenue | −15.6% | +6.4% | +2.4% |
| EPS | −6.9% | +30.3% | −3.0% | |
PNW | Revenue | +3.1% | +7.3% | +5.5% |
| EPS | −5.4% | +17.5% | +10.5% | |
PCG | Revenue | +2.8% | +3.9% | +3.9% |
| EPS | +10.1% | +9.0% | +9.2% | |
EIX | Revenue | +1.9% | +3.4% | +3.3% |
| EPS | +0.8% | +6.2% | +5.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
On April 10, 2026, the last condition under Hawaiian Electric Industries' Maui wildfire settlement fell away — a judgment on insurers' subrogation claims became final after every carrier stipulated to dismiss its appeal — and the Honolulu utility authorized the first of four annual payments of $479m. The money did not come from the bank it sold. It came from stock it had sold eighteen months earlier and parked in a special-purpose vehicle built to hold exactly that payment.
That distinction is the whole story of what Hawaiian Electric's shares now represent. The company generates and distributes power across Oahu, Maui, Hawaii Island, Lanai and Molokai on a grid connected to nothing else, earning a regulated return on a small island rate base. Sitting in front of that return are three more $479m installments, due each April through 2029.
The funding stack, in order
Hawaiian Electric priced 54,054,054 shares at $9.25 in September 2024, raising roughly $575m of new common stock expressly to fund its settlement contribution. Diluted shares have gone from 109.8m in 2022 to 173.2m in the June 2026 quarter, a 58% increase. Consensus has earnings per share at $0.84 this year and $1.09 next — against the $2.20 to $2.25 the company earned in 2021 and 2022, because the same rate-base earnings are now divided among far more shares.
The sale of 90.1% of American Savings Bank brought $405m of cash at the end of 2024 — less than one installment — and went to reducing holding-company debt. It also removed the non-utility earnings leg that used to smooth the utility's results. As of June 30 the discounted settlement liability stood at $1.30bn, while unrestricted cash was $52m at the holding company and $186m at the utility, $238m in all. The $1.3bn of consolidated liquidity management cites is almost entirely undrawn at-the-market equity capacity and revolving credit — the next installment gets funded by issuing something.
The engine that has to refill it
June-quarter core net income was $22.5m, or $0.13 a share, down from $0.20 a year earlier; utility core income fell to $32.6m from $42.5m. Reported profit of $123.2m is not comparable — it includes a $153.9m pre-tax non-cash gain from remeasuring the settlement liability, which is why a trailing price/earnings ratio of 8.5x means nothing here. The utility's trailing-twelve-month earned return on equity is 6.1% against an authorized 9.5%, and 2026 carries $28m of wildfire insurance premiums that lost deferral treatment, flood response, and the August 16-17 damage from Tropical Storm Lala, which cut power to more than 197,000 customers.
The repair is a rate case. "Our total $170 million proposed base rate increase is phased in over 2 years, with $125 million of the increase proposed to take effect beginning in 2027," chief executive Scott Seu told investors on August 7. An interim decision is expected by December 18, with a final order in April 2027 — after which, regulatory affairs head Joe Viola said on the same call, "we're going to rebase rates right now for the next five-year multi-year rate plan."
Bondholders won; the equity waited
Every favorable development of the past year accrued mostly to creditors. Moody's upgraded in April; "in July, S&P upgraded HEI and Hawaiian Electric one notch to double B-minus," chief financial officer Paul Ito said, after the commission approved roughly $350m of wildfire-mitigation cost recovery in June. Hawaii's Act 258 permits securitizing those costs, with a financing order expected late this year. In February the state Supreme Court held that subrogating insurers "do not have a protectable interest that allows them to intervene" in the settlement. The company still owes $1.44bn of undiscounted installments, pays no dividend, and cannot chase the load growth lifting mainland utilities — data-center demand does not reach an island with no interstate transmission.
The shares are down 10.3% over twelve months, the worst in a regulated-electric group in which most names rose, and they barely moved on August 31 when California's wildfire legislation knocked 23% off Edison International. This is company-specific. At 1.09x book value against Pinnacle West's 1.68x, the discount is real but modest; PG&E trades at 0.91x. The market is not pricing insolvency. It is pricing a business whose allowed return is fixed, whose share count already rose, and whose cash goes out every April.
The rate plan being set this winter binds through roughly 2032. The last settlement installment is due in 2029 — meaning the terms decided in December will govern what shareholders earn across every remaining payment, and for three years after the last one clears.