

Booking and Expedia Fell in Step on September 8; Only Expedia's Growth Is Accelerating
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two travel businesses whose June quarters point in opposite directions were sold at almost exactly the same rate in one session, which means the market was pricing the distribution channel rather than the companies.
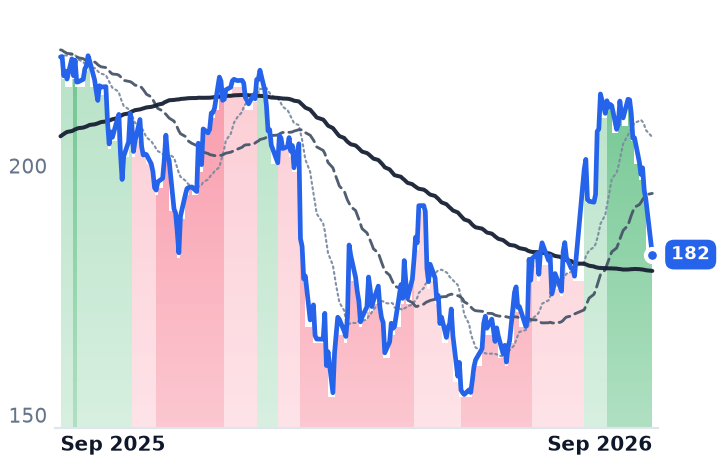
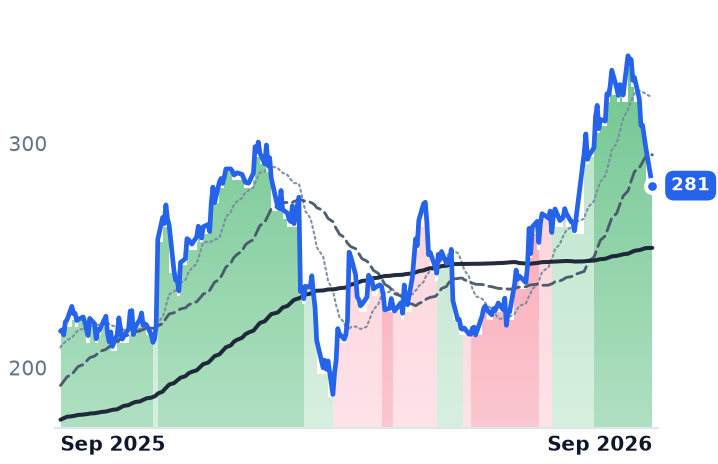
Booking Holdings' revenue growth halved to 8.1% from 16.2% the prior quarter, room nights grew 5%, and marketing spend rose 11% against gross bookings up 9%. Expedia went the other way: revenue up 14.0%, operating margin of 23.9% against 14.0% a year earlier, business-to-business bookings up 21%, and raised full-year guidance.
Booking's fall is largely earned by decelerating, more expensively bought growth. Expedia's is not explained by anything in its own results; on forward earnings it trades roughly a quarter below Booking. The shared worry is Google's agentic hotel booking, which Booking's own traffic data does not yet show.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
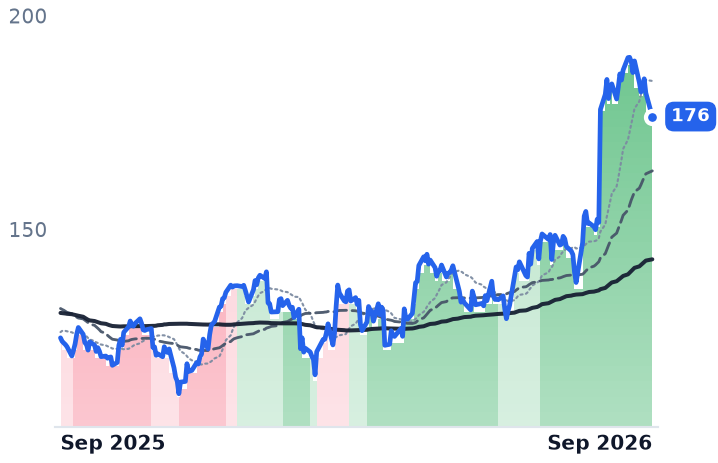
BKNG | Booking | Online Travel Agencies | 🌱 Emerging Bull | −13.5% | −17.9% |
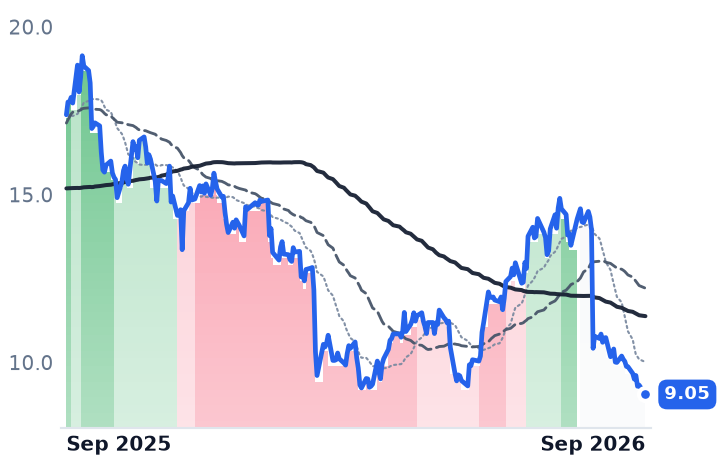
EXPE | Expedia | Online Travel Agencies | 🟢 Cont. Bull | −9.3% | +30.0% |
| Compared against · context, not the story | |||||
MMYT | MakeMyTrip | Online Travel Agencies | 🌱 Emerging Bull | −13.2% | −46.8% |
TCOM | Trip.com | Online Travel Agencies | ⚠️ Emerging Bear | −13.4% | −44.5% |
ABNB | Airbnb | Alternative Accommodations | 🟢 Cont. Bull | −2.9% | +41.6% |
TRIP | Tripadvisor | Marketplace & Local Services | 🔴 Cont. Bear | −15.6% | −48.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BKNG | $139.7B | 19.9x | 17.2x | 4.9x | 4.8x | 4.9x | 4.8x | 13.3x | 6.8% |
EXPE | $31.4B | 16.5x | 13.2x | 2.0x | 1.9x | 2.2x | 2.1x | 7.8x | 16.0% |
MMYT | $5.2B | 157.5x | 106.3x | 4.9x | 4.4x | 7.1x | 6.3x | 30.7x | 1.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TCOM | $26.7B | 5.8x | — | 2.7x | — | 3.4x | — | 4.1x | 7.8% |
ABNB | $78.8B | 31.6x | 25.9x | 6.2x | 5.7x | 7.5x | 6.8x | 28.9x | 5.8% |
TRIP | $1.1B | 58.7x | 7.2x | 0.6x | 0.6x | 0.8x | 0.8x | 5.6x | 16.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BKNG | Revenue | +9.6% | +9.4% | +8.2% |
| EPS | +14.9% | +18.4% | +15.7% | |
EXPE | Revenue | +10.9% | +7.2% | +7.7% |
| EPS | +35.9% | +17.2% | +14.6% | |
MMYT | Revenue | +12.6% | +7.4% | +17.3% |
| EPS | −48.0% | +19.8% | +97.7% | |
TCOM | Revenue | +9.9% | +10.9% | +10.5% |
| EPS | −48.0% | +16.8% | +10.3% | |
ABNB | Revenue | +14.6% | +10.5% | +10.6% |
| EPS | +24.2% | +18.1% | +18.2% | |
TRIP | Revenue | −0.6% | +4.4% | +5.4% |
| EPS | −3.1% | +20.3% | +30.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
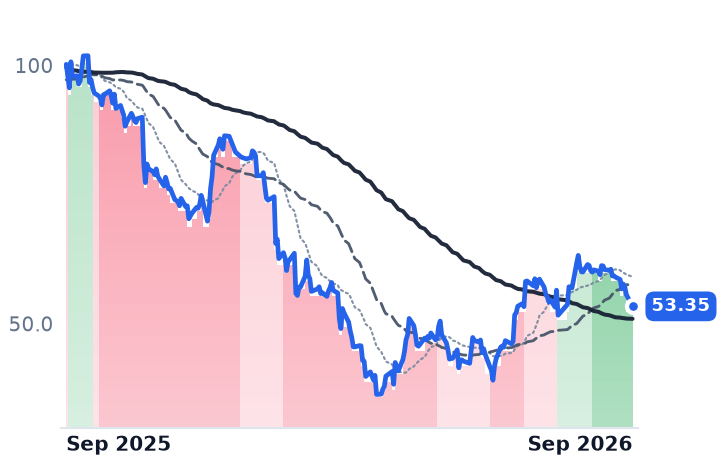
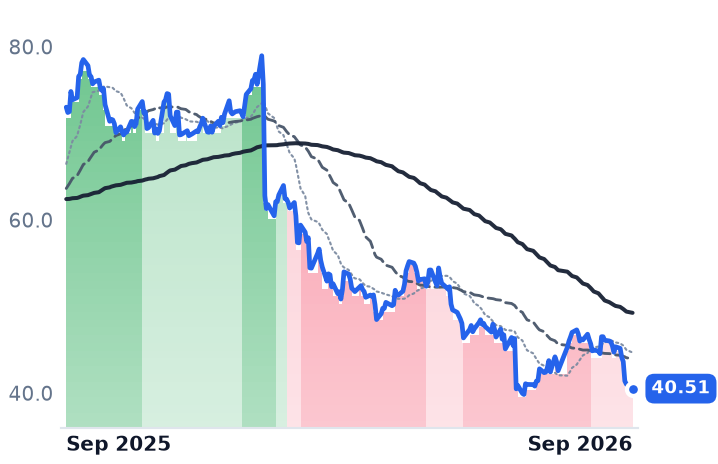
No news came out of Booking Holdings on 8 September, and the owner of Booking.com, Agoda, Priceline, KAYAK and OpenTable closed 5.7% lower at $182.20 — with every other listed online travel agency falling alongside it. Expedia Group, which runs Brand Expedia, Hotels.com, Vrbo and the business-to-business unit Expedia Partner Solutions, fell 5.6%. Airbnb and Tripadvisor each lost about 3%, MakeMyTrip 4.1% and Trip.com 1.3%. Trade coverage described a broad selloff that swept across travel services companies with no company-specific catalyst; intraday, Booking was quoted down 7.0% at $179.76 before recovering into the close. The macro backdrop was Brent crude near $99 a barrel intraday on renewed Middle East fighting, roughly 60% market-implied odds of a Federal Reserve rate increase on 15-16 September, and consumer discretionary among the least-wanted sectors.
That matters because the two largest names in the group reported June quarters that moved in opposite directions, and were sold within a tenth of a percentage point of each other regardless. What the session priced was the channel both companies rent — paid search — not the profit and loss statements underneath.
Booking earned its de-rating
Booking's revenue of $7,352m grew 8.1% year on year, against 16.2% in the March quarter and 16.0% in December. Room nights grew 5% while gross bookings grew 9%, so the dollar growth came more from price and mix than from travellers. Marketing expense rose 11% to $2,371m, or 4.7% of gross bookings, the company citing traffic-mix changes and incremental paid marketing — traffic got more expensive as volume growth slowed. Operating margin still improved, to 34.0% from 33.1%, and diluted earnings per share of $2.53 was flattered by a share count down to 770m from 815m after a record $3.7bn of second-quarter repurchases. Chief financial officer Ewout Steenbergen framed the year as intact: full-year guidance is "at a high single-digit level for gross bookings and revenues and at mid-teens level for EPS at the high end," he told investors on the 4 August call, with seven of twelve months carrying Middle East war impact.
Expedia did not
Expedia's revenue accelerated to 14.0% growth, its fourth straight quarterly improvement, and operating margin reached 23.9% from 14.0% — operating income nearly doubled. Gross bookings of $33.9bn rose 12%, with the business-to-business arm, which white-labels Expedia's hotel supply to airlines, banks and offline agents, up 21% and consumer bookings up 8%. "We exceeded the high end of both our top and bottom-line expectations for the fifth quarter in a row, growing bookings 12%, revenue 14%, and adjusted EBITDA 23%," chief executive Ariane Gorin said on 5 August. Chief financial officer Derek Andersen raised full-year margin guidance the same day. Expedia's take rate, 12.7% of bookings against Booking's 14.4%, is lower precisely because wholesale distribution is its fastest-growing channel — and it bought back only $200m of stock in the quarter, so the earnings growth came from operations.
Booking trades at 17.2x forward earnings against 19.9x trailing, 13.3x trailing enterprise value to EBITDA, on a 6.8% free-cash-flow yield; years of debt-funded buybacks have left book equity negative. Expedia trades at 13.2x forward against 16.5x trailing and 7.8x EBITDA, a roughly 24% forward-earnings discount to a slower-growing peer. In July, value investor Scott Black of Delphi argued Booking's then-17.5x multiple was not warranted by the size of its advantages and preferred Expedia; the price has come to him, but so have the estimates, which is why Booking's multiple has barely compressed.
The verdict
Booking's 15% slide from its 7 August close is mostly a business fact: growth halved, units grew half as fast as dollars, and acquisition cost rose. Expedia's 9.5% one-month decline has no such explanation — guidance went up, margin went up almost ten points, and share count did nothing. The residual on both is the same fear, and it is a repeat: Booking fell 25% in February 2026, its worst month since April 2010, and Expedia 32%, on the identical worry. Booking's own data does not corroborate it yet — Steenbergen said large-language-model referrals, paid and unpaid, are under 1% of total room nights and have not moved much. BTIG's Jake Fuller, on the launch: "We get the market's reaction but see the risk as overstated."
The detail worth holding is in the plumbing of Google's agentic hotel booking, live in AI Mode since 27 August with Booking.com, Expedia and Hotels.com as launch partners. The agencies remain merchant of record, so the commission survives the first cut. What they lose is the chat context ahead of it — the inspiration signals that tell them what a traveller wanted before they asked for a room.