

Centrus's Russian Enrichment Supply Ends in 2027 and Its Own Plant Starts in 2029
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The only American-owned uranium enricher buys most of what it sells from Russia's TENEX and France's Orano, and the Russian half of that arrangement has a legal end date fifteen months out. Centrus's own centrifuge plant at Piketon does not produce commercially until 2029, leaving a gap its $4.5bn order book cannot cover.
The second half of the business is an appropriations line: the government contract that actually paid revenue expired on June 30, 2026, and Technical Solutions sales fell 21% to $22.7m. Its $900m replacement asks for one metric ton of high-assay fuel by March 2032. Consensus has earnings falling from $3.90 in 2025 to $2.54 this year, which is why the shares trade at 73.1x forward earnings against 73.9x trailing — no growth priced at all.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
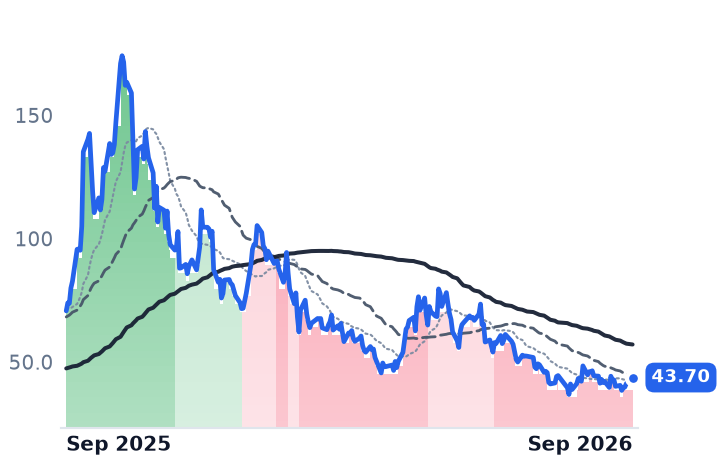
LEU | Centrus Energy | Uranium | ⚠️ Emerging Bear | −2.3% | −9.4% |
| Compared against · context, not the story | |||||
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | +5.7% | +33.6% |
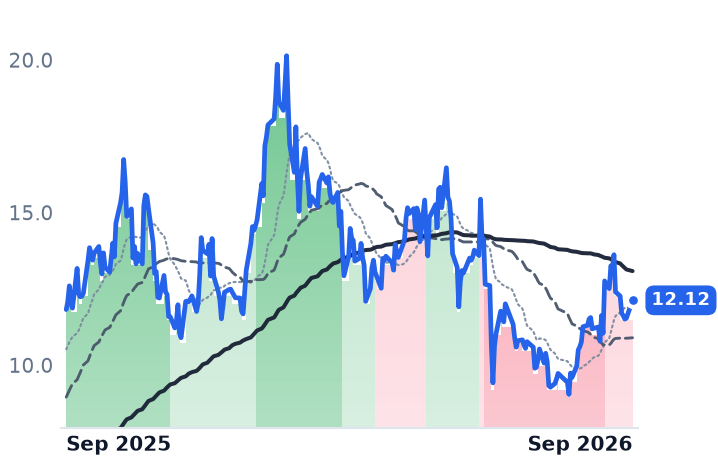
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −10.1% | −44.2% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | +20.7% | −67.1% |
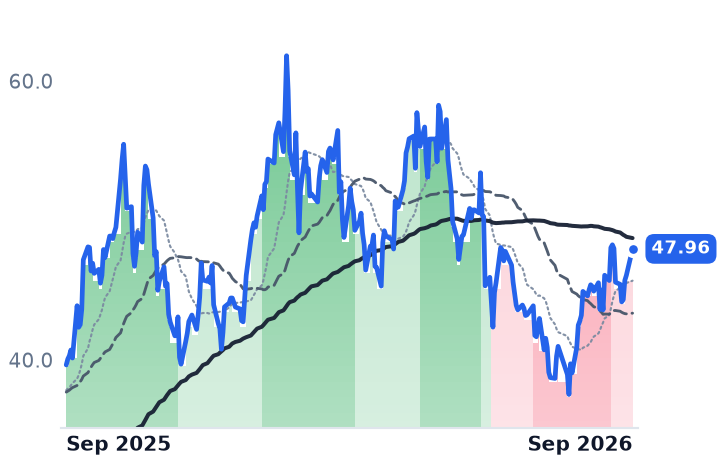
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −2.5% | −38.2% |
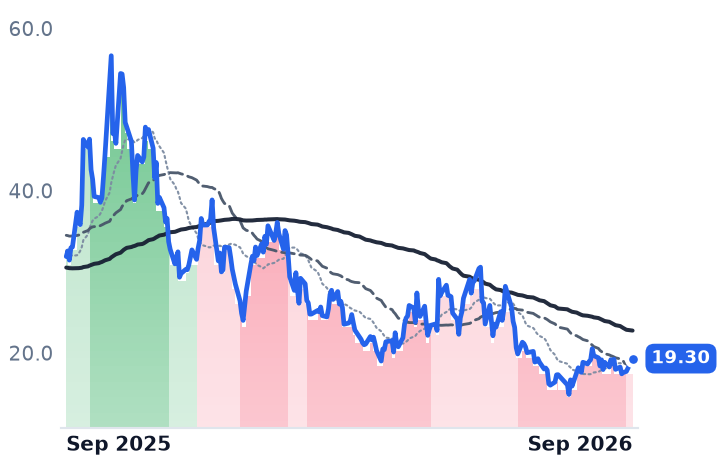
UEC | Uranium Energy | Uranium | ⚠️ Emerging Bear | +7.3% | +2.6% |
URA | Global X - Uranium ETF | Asset Management | ⚠️ Emerging Bear | +7.6% | +21.0% |
NNE | Nano Nuclear Energy | Power & Propulsion Systems | 🔴 Cont. Bear | +3.5% | −39.5% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.8% | +19.3% |
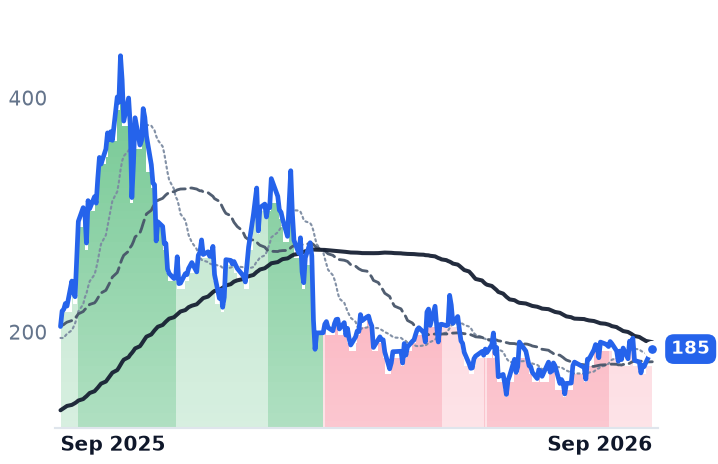
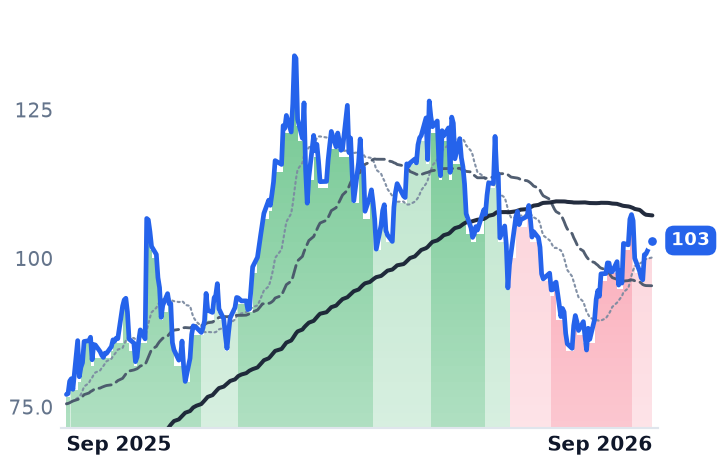
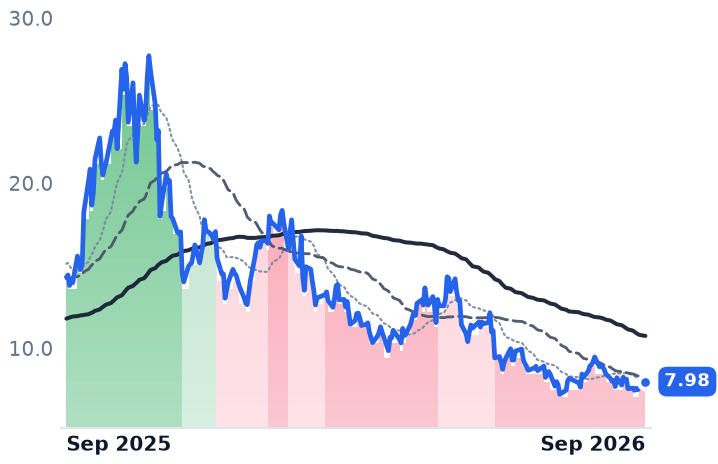
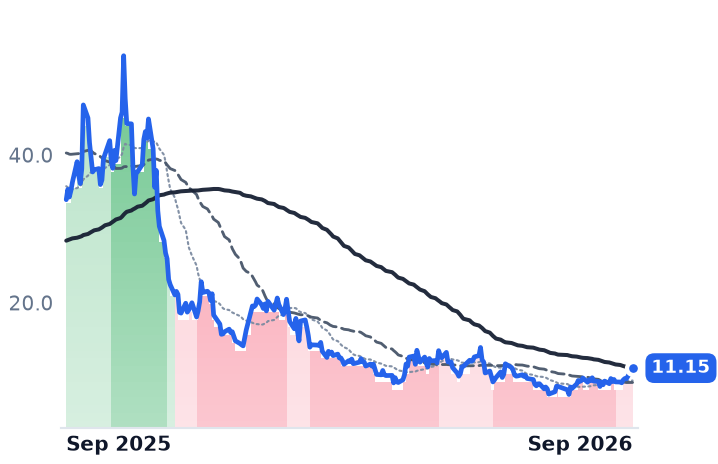
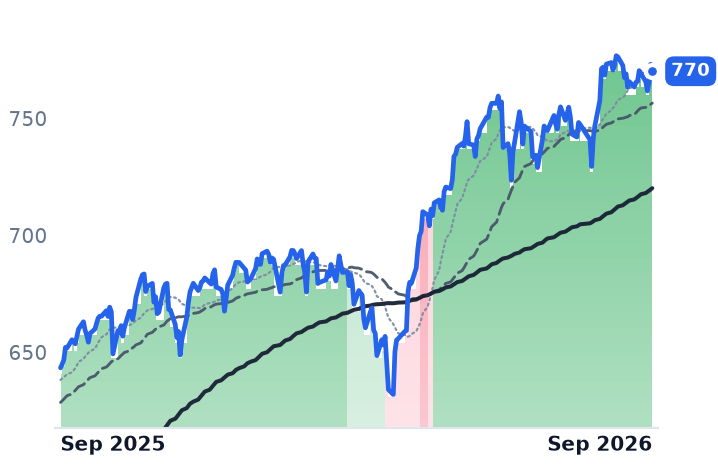
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $3.5B | 73.9x | 73.1x | 7.4x | 7.5x | 31.9x | 32.1x | 38.9x | -6.3% |
CCJ | $44.4B | 172.2x | 65.7x | 17.6x | 12.4x | 64.0x | 45.0x | 71.0x | 0.8% |
LTBR | $277.3M | n/m | — | n/m | — | — | — | n/m | -6.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SMR | $2.8B | n/m | — | 261.9x | 91.1x | — | 432.7x | n/m | -27.7% |
OKLO | $7.3B | n/m | — | — | — | — | — | n/m | -3.8% |
UEC | $6.5B | n/m | — | 321.7x | 64.7x | 760.1x | 152.9x | n/m | -1.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
URA | $3.9B | — | — | — | — | — | — | — | — |
NNE | $1.1B | n/m | — | — | 887.7x | — | — | n/m | -3.7% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.4% | +12.2% | −22.3% | |
CCJ | Revenue | +4.4% | +12.1% | +8.6% |
| EPS | +8.1% | +69.5% | +26.2% | |
SMR | Revenue | −26.7% | +434.9% | +101.2% |
| EPS | −74.7% | +33.4% | −18.3% | |
OKLO | Revenue | — | +241.0% | +577.4% |
| EPS | +50.0% | +10.3% | +16.5% | |
UEC | Revenue | −59.3% | +272.6% | +157.9% |
| EPS | +56.8% | −79.8% | −647.6% | |
NNE | Revenue | +1684.0% | +356.5% | +39.0% |
| EPS | −23.4% | +55.2% | +34.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Centrus Energy sells enrichment it does not make. The Bethesda, Maryland company supplies low-enriched uranium to utilities in the United States, Japan and Belgium, and buys most of the separative work units it resells under long-term contracts with Russia's TENEX and France's Orano — two of the three largest Western-market enrichers it also competes against. Its filings run the TENEX supply term through December 31, 2027.
The day after that, the last waivers under the Prohibiting Russian Uranium Imports Act lapse; the Department of Energy sets the outside date at January 1, 2028, after which no Russian enriched uranium may enter the country. Centrus's own centrifuge plant at Piketon, Ohio is guided to commercial production in 2029. Between the two dates sits the question the order book does not answer. American reactor operators bought roughly 3.28 million separative work units of Russian enrichment in 2025, close to 26% of their purchases — volume that must be re-sourced from Western capacity on the same calendar.
A delivery schedule, not a price signal
Enrichment prices are at records and Centrus barely feels them. UxC put spot separative work at $215 at the end of August, against $200 in January, with long-term values around $181. Centrus realized a 3% increase in enrichment pricing in the June quarter, because deliveries bill out under multi-year contracts struck years earlier. Revenue rose 14% to $176.1m only because uranium resale replaced enrichment: volumes of separative work fell 23%, gross margin compressed from 34.9% to 28.3%, and operating income fell 69% to $10.4m.
The other half of the company is an appropriations line. Technical Solutions revenue fell 21% to $22.7m on a $5.9m decline in high-assay low-enriched uranium operations, as the demonstration contract wound down. The Department of Energy had split its three-year option into a one-year extension worth $108.2m and a two-year follow-on, exercising only the first; it expired June 30, 2026. The replacement, signed the same day, is a $900m fixed-price contract with options taking it to $1.07bn, requiring one metric ton of high-assay fuel by March 2032. It is excluded from backlog.
What the order book buys
Backlog reached $4.5bn extending to 2040, and financial contingencies came off more than $3bn of customer contracts in the quarter. "Importantly, all financial contingencies in our contingent LEU enrichment backlog have now been removed," chief executive Amir Vexler told investors on the August 6 call, adding that "we are seeing strong demand signals across all three of our addressable markets: commercial LEU, national security, and HALEU." Management also said utilities are waiting to see centrifuges delivered and installed before committing further, and declined to guide beyond this year.
The machines are being paid for with equity. Diluted shares rose a third over eight quarters to 21.89m, including $53.9m raised through the at-the-market program in the June quarter against $71.6m of capital expenditure; full-year capital deployment guidance is $350m to $500m, funded from $1.9bn of cash. Urenco's competing American expansion at Eunice, New Mexico adds 2.1 million separative work units with first cascades expected in 2032.
The de-rating is earned; the bottom is not
Consensus earnings fall from $3.90 reported in 2025 to $2.54 this year and $1.47 by 2029. That is why the shares carry 73.1x forward earnings against 73.9x trailing — the multiple expanded from roughly 64x forward in May as estimates were cut faster than the price. Cameco, the fuel-cycle anchor that mines and converts uranium but sells no enrichment, shows the opposite shape: 172.2x trailing falling to 65.7x forward.
The shares closed at $185.38, about 60% below the $464.25 high of the past year, with JPMorgan cutting its target to $178 from $236. Monday's 6.6% gain came with NuScale up 15.0% and Oklo up 5.9% while the market fell, on no fresh catalyst and no company announcement; the likelier reading is sector rotation.
The income statement and the estimate path earn the year's decline. The order book argues the other way, and it is real — but it converts when cascades spin, not when contracts are signed, and the contracts that supply today's margin die before the cascades run. Between the last legal shipment of Russian material and the first commercial pound out of Piketon lies a hole in the calendar, and the government contract meant to close it asks for a single metric ton by 2032.