

Okta's Seat-Priced Half Grew 11%, Its Usage-Billed Half 13%, and the Mix Did Not Move
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Okta's shares have more than doubled since March on a story about identity for AI agents, and the company's own finance chief calls that revenue "still immaterial." What the quarter actually showed was two very different meters running at almost the same speed: the employee-seat Workforce book and the usage-billed Auth0 book, with the split between them stuck at 59/41 for a second straight quarter.
The growth that does exist is in bookings rather than billings. Obligations due within a year rose 14% against reported revenue growth of 10.6% — a third consecutive quarterly deceleration — and Okta guides that bookings figure back down to 11–12%. Against that, the price has roughly doubled relative to gross profit since May. SailPoint, the governance specialist, is growing at about twice Okta's rate and reports on September 9.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
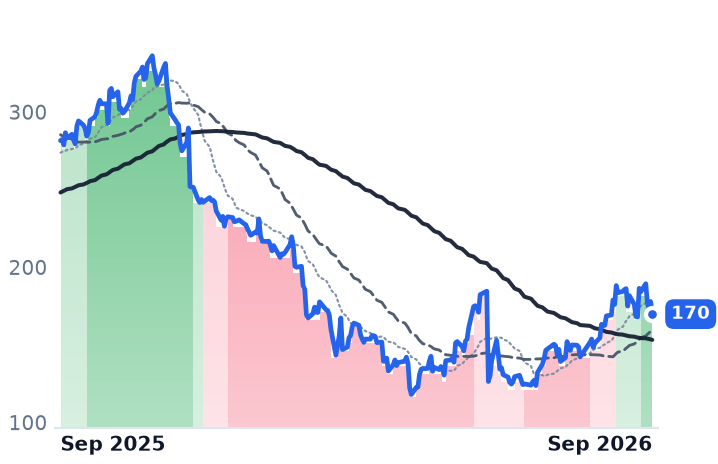
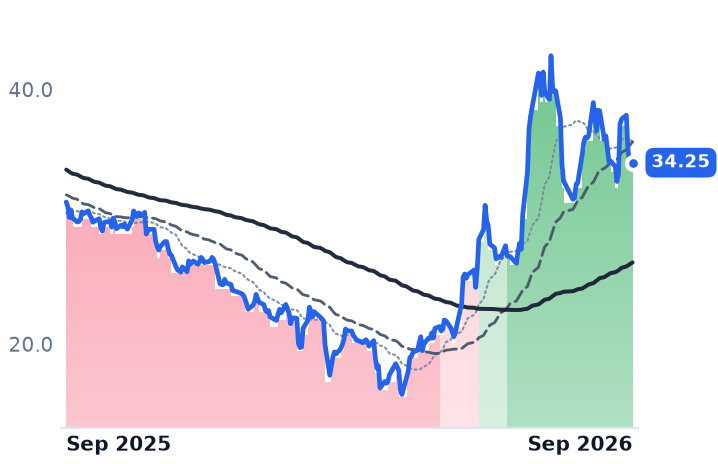
OKTA | Okta | Identity & Access Management | 🌱 Emerging Bull | +14.3% | +84.1% |
| Compared against · context, not the story | |||||
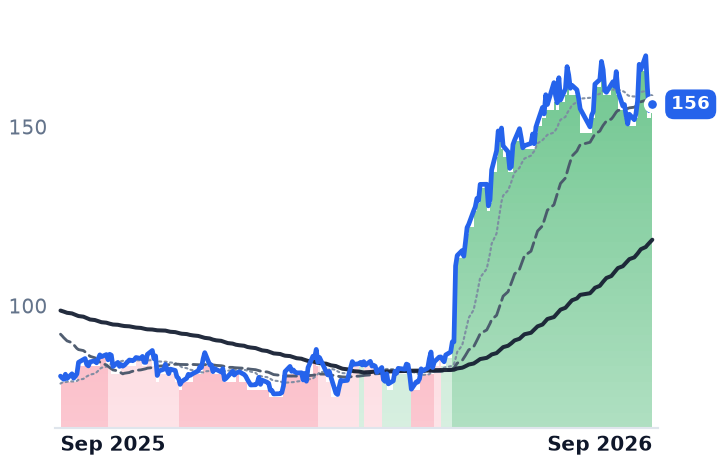
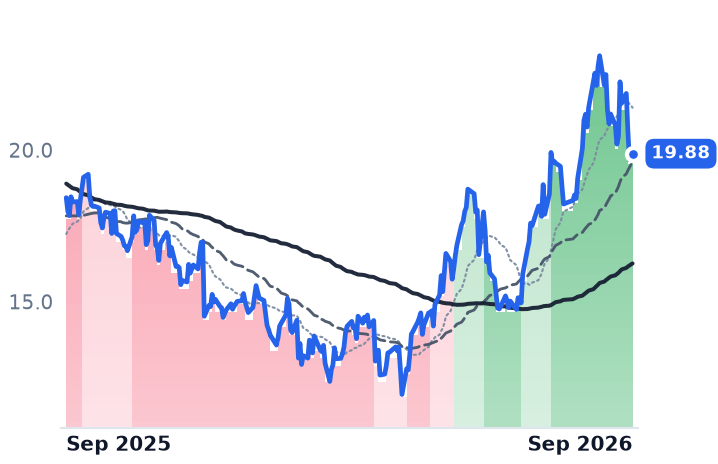
SAIL | SailPoint | Identity & Access Management | 🌱 Emerging Bull | +0.3% | −15.9% |
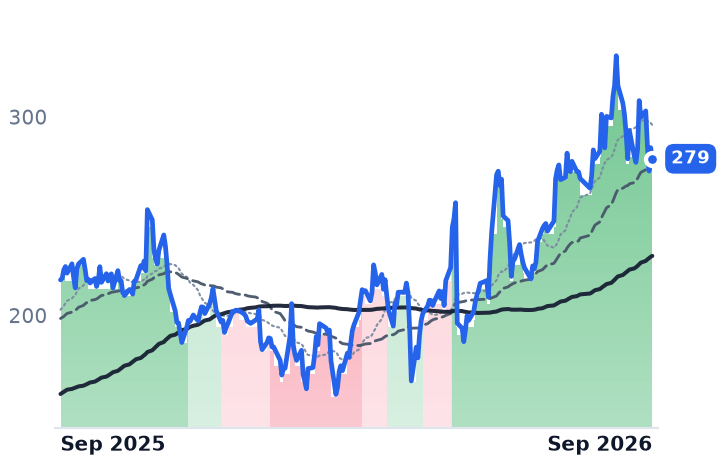
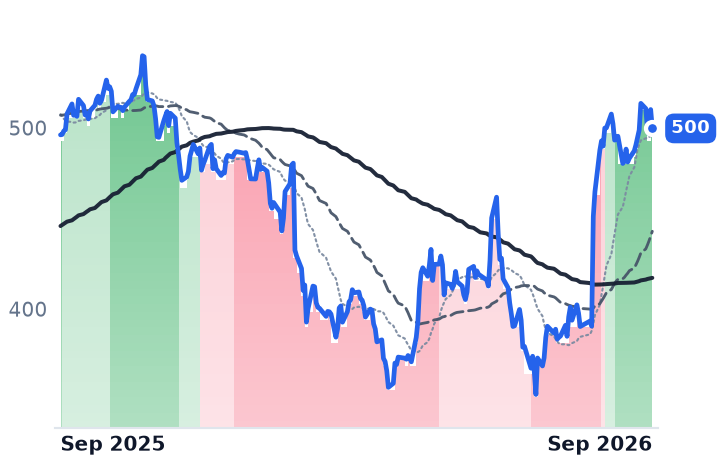
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🌱 Emerging Bull | −9.6% | +68.8% |
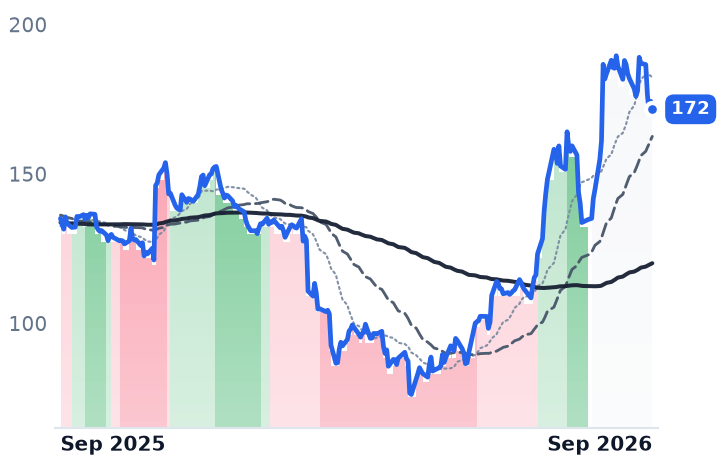
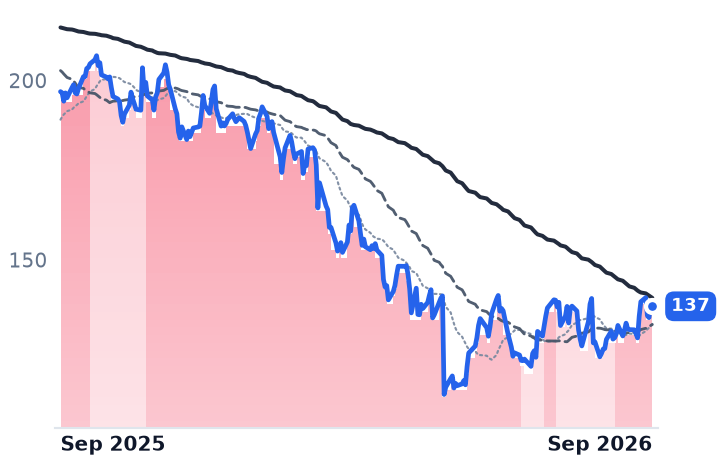
CRWD | CrowdStrike | Cybersecurity & Threat Protection | 🔴 Cont. Bear | −1.7% | −50.2% |
ZS | Zscaler | AI & Data Intelligence | 🔴 Cont. Bear | +0.3% | −39.7% |
FTNT | Fortinet | Network Security Appliances | 🌱 Emerging Bull | −3.4% | +94.5% |
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | −6.9% | +28.0% |
QLYS | Qualys | Cybersecurity & Threat Protection | 🌱 Emerging Bull | −8.7% | +27.0% |
TENB | Tenable | Cybersecurity & Threat Protection | 🌱 Emerging Bull | −12.1% | +9.9% |
S | SentinelOne | Cybersecurity & Threat Protection | 🌱 Emerging Bull | −10.7% | +7.9% |
CHKP | Check Point Software Technologies | Cybersecurity & Threat Protection | 🔴 Cont. Bear | +5.3% | −30.4% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🌱 Emerging Bull | −1.6% | +0.7% |
RBRK | Rubrik | Other | 🌱 Emerging Bull | −4.3% | −2.0% |
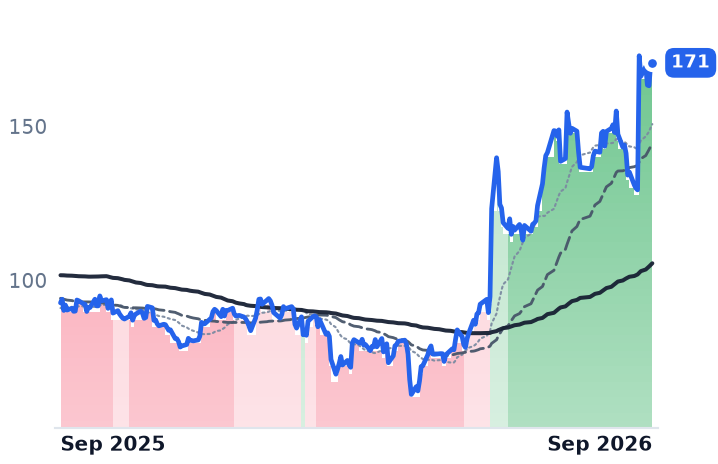
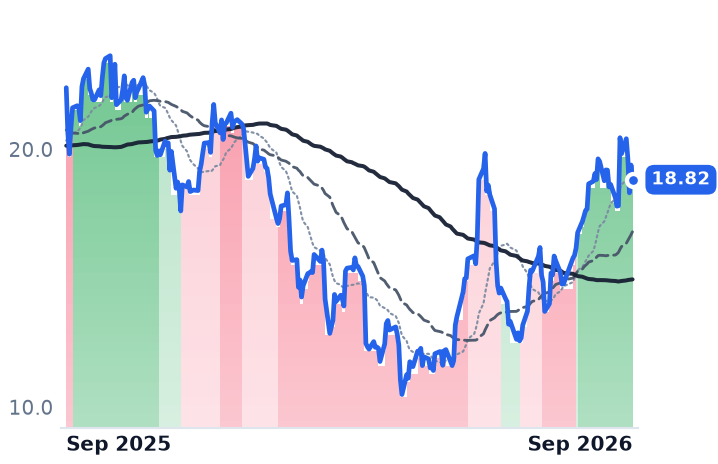
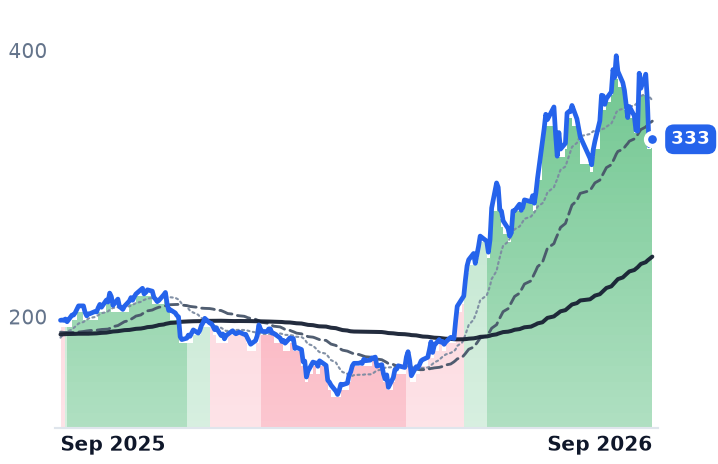
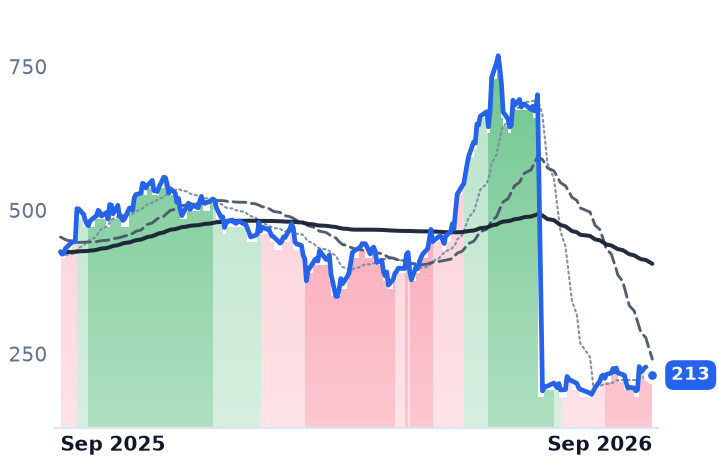
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKTA | $28.3B | 100.9x | 43.4x | 9.2x | 8.8x | 11.8x | 11.3x | 70.1x | 3.4% |
SAIL | $11.1B | n/m | — | 9.9x | — | 15.0x | — | 853.3x | 1.7% |
PANW | $271.6B | 724.5x | 79.6x | 23.7x | 19.2x | 33.6x | 27.3x | 506.7x | 1.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRWD | $217.0B | — | 170.1x | 40.2x | 36.2x | 53.4x | 48.0x | 487.1x | 0.7% |
ZS | $27.5B | n/m | 35.0x | 8.2x | 7.0x | 10.7x | 9.1x | 152.2x | 3.1% |
FTNT | $114.7B | 54.6x | 45.3x | 15.2x | 14.1x | 19.0x | 17.6x | 38.8x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NET | $99.0B | n/m | 221.1x | 39.4x | 34.5x | 54.3x | 47.6x | — | 0.4% |
QLYS | $3.2B | 15.9x | 11.9x | 4.6x | 4.4x | 5.6x | 5.3x | 11.4x | 9.2% |
TENB | $2.4B | n/m | 11.0x | 2.3x | 2.2x | 3.0x | 2.8x | 23.3x | 11.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
S | $7.2B | n/m | 61.3x | 6.9x | 6.0x | 9.3x | 8.1x | n/m | 0.6% |
CHKP | $12.9B | 12.3x | 11.9x | 4.7x | 4.6x | 5.5x | 5.4x | 14.3x | 10.1% |
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RBRK | $19.3B | n/m | 189.1x | 12.5x | 11.4x | 15.6x | 14.2x | n/m | 1.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
OKTA | Revenue | +12.0% | +10.9% | +9.9% |
| EPS | +24.3% | +14.1% | +10.6% | |
PANW | Revenue | +24.3% | +23.8% | +14.3% |
| EPS | +15.5% | +10.7% | +16.7% | |
CRWD | Revenue | +22.2% | +24.9% | +22.6% |
| EPS | −1.2% | +34.9% | +27.4% | |
ZS | Revenue | +25.2% | +17.8% | +16.4% |
| EPS | +29.2% | +17.6% | +15.5% | |
FTNT | Revenue | +20.1% | +11.4% | +11.1% |
| EPS | +28.0% | +9.4% | +13.1% | |
NET | Revenue | +33.7% | +28.4% | +27.1% |
| EPS | +38.0% | +32.6% | +35.1% | |
QLYS | Revenue | +8.6% | +7.0% | +6.6% |
| EPS | +8.6% | +9.2% | +5.3% | |
TENB | Revenue | +8.4% | +7.1% | +6.9% |
| EPS | +27.0% | +10.5% | +10.1% | |
S | Revenue | +22.4% | +19.9% | +17.6% |
| EPS | +723.4% | +83.7% | +43.0% | |
CHKP | Revenue | +3.2% | +6.0% | +5.6% |
| EPS | −7.5% | +9.6% | +9.1% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% | |
RBRK | Revenue | +48.7% | +31.9% | +21.4% |
| EPS | −90.5% | −384.9% | +54.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Two meters, one speed
Okta bills enterprises for every employee who logs in, and bills developers using its Auth0 product for the monthly active users of their apps. In the quarter ended July 31, reported August 26, those two books grew 11% and 13% in annual contract value — and the split between them, 59% workforce and 41% customer identity, was identical to the prior quarter, when the same lines grew 10% and 12%. Both halves accelerated by exactly one point. The mix did not budge.
That is the fact the last six months of share price does not obviously accommodate. Okta, the largest independent identity vendor and the one company whose front door most large enterprises pass through, has been re-rated on the premise that AI agents will multiply the number of identities it charges for, breaking the link between its revenue and its customers' headcount. Chief financial officer Brett Tighe, asked on the August 26 call what agents contribute today: "Still immaterial. Still very small. We're very early innings… for FY '27, we don't think it's going to be material. But '28 and beyond, we do think that there is a real possibility for this to be material for the business in the long run."
What is actually expanding
The expansion Okta can document is module attach at its biggest accounts. Identity Governance, Privileged Access and Identity Threat Protection made up 30% of bookings in the quarter, at an average uplift of roughly 40% to deal value. Customers above $1m of annual contract value grew 22%, past 600. But customers above $100,000 grew only 6%, to 5,255. This is large-enterprise consolidation — existing whales buying more shelf — rather than a proliferation of new identities being metered.
The bookings are genuinely better than the revenue. Current remaining performance obligations rose 14% to $2.585bn and total obligations 17% to $4.858bn, against reported revenue growth of 10.6% to $805m — the third straight quarter of decelerating revenue, from 11.6% two quarters ago. Net retention held at 107%. Free cash flow was $227m, a 28% margin against 22% a year earlier. Gross margin widened almost three points to 79.6%. The seven-point jump in reported operating margin, to 13.3%, is mostly stock compensation and acquisition amortization rolling off: on a non-GAAP basis, operating margin improved about half a point, to 28.2%. And Okta's own third-quarter guidance takes that 14% bookings growth back to 11–12%.
The re-rating was three days
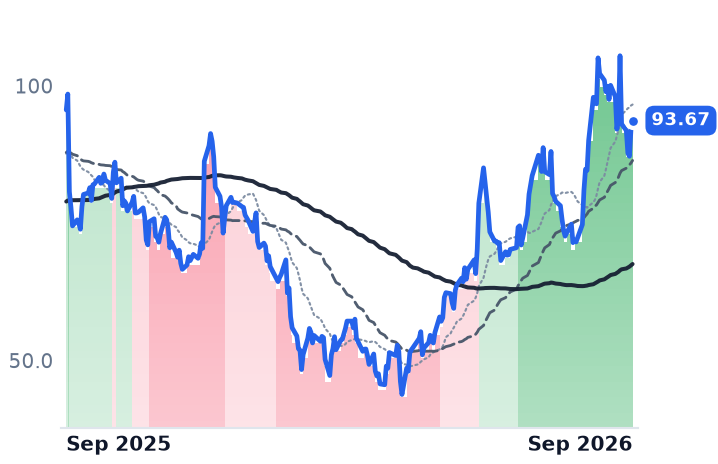
The six-month gain of 111% was not a grind. Three earnings sessions — May 29, June 1 and August 27 — supply roughly nine-tenths of it; the August 27 session alone ran $129.35 to $172.91, a 33.7% close-to-close move, after CNBC reported a 20% gain in extended trading the evening before. The 50-day average has sat above the 200-day since June 8.
What the shares now pay for that is roughly double what they paid in spring. Price to trailing gross profit is 11.80x, against 5.97x on May 3 and 10.29x on July 29, on gross profit that grew 14.5%; forward earnings are 43.4x against consensus revenue growth of 10.9% this year and 9.9% next. The mean analyst target, near $172, is level with the price. Okta led a broad security re-rating rather than standing alone — Palo Alto Networks rose 101.9% and Fortinet 86.8% over the same window, while CrowdStrike fell 50.3%.
SailPoint, the identity-governance specialist and the only live independent comparable since Palo Alto closed its $21.1bn purchase of CyberArk in February, grew revenue 21.6% to $280.1m last quarter — about twice Okta's rate — but at a 64.7% gross margin and a 28.5% operating loss, and at 14.96x trailing gross profit. It rose 14.8% on August 27 having disclosed nothing of its own.
The verdict
The business earns part of this. Bookings running three and a half points ahead of revenue, retention off its trough, and cash conversion at 28% are real, and the governance and privilege modules are being bought. What nothing in the disclosure yet earns is the doubling of the multiple, because the specific thing that doubling assumes — a usage-metered book pulling away from a seat-metered one — has not started. Okta's two halves are growing at the same pace, in the same proportion, and its own guidance says the bookings figure steps back next quarter.
Okta's cross-app access protocol went generally available with Anthropic, and agent single sign-on now ships inside the standard edition with a consumption cap built in but not enforced. Chief executive Todd McKinnon said on the call that agent identity "could be the biggest category of cyber" in the fullness of time. The pricing today is still a per-user uplift — the plumbing for a per-agent meter is installed, and the meter is not yet switched on.