

SolarEdge Turned Its First Operating Profit in Three Years, Then Guided Margin to 22-26%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
SolarEdge's business is accelerating while its shares are priced as though it were shrinking. June-quarter revenue was $346.2m, up 19.6% from a year earlier, with a sixth consecutive quarter of gross margin expansion and no safe-harbour orders flattering the number.
Then management guided September revenue to $310-340m, below the June quarter, and the shares lost more than a quarter of their value in one session. The pair splits cleanly: Enphase's reported revenue carries equipment for systems not built until 2028 while its US installations fell 34%; SolarEdge's does not. Both now trade near seven times trailing gross profit, against roughly sixteen times in May. Thursday's investor day is where the missing safe-harbour number is supposed to appear.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
SEDG | SolarEdge Technologies | Inverters & Power Electronics | ⚠️ Emerging Bear | +6.2% | +2.3% |
ENPH | Enphase Energy | Inverters & Power Electronics | 🔴 Cont. Bear | −11.1% | −6.3% |
| Compared against · context, not the story | |||||
RUN | Sunrun | Residential Solar Installers | ⚠️ Emerging Bear | −11.1% | −47.5% |
FSLR | First Solar | Solar Module Manufacturers | 🟢 Cont. Bull | −13.2% | +0.6% |
NXT | Nextpower | Other | 🟢 Cont. Bull | −17.2% | +21.1% |
ARRY | Array Technologies | Solar Tracking Systems | ⚠️ Emerging Bear | −14.3% | −47.4% |
SHLS | Shoals Technologies | Solar System Components | 🟢 Cont. Bull | −16.8% | −0.1% |
CSIQ | Canadian Solar | Solar Module Manufacturers | ⚠️ Emerging Bear | −14.7% | +21.1% |
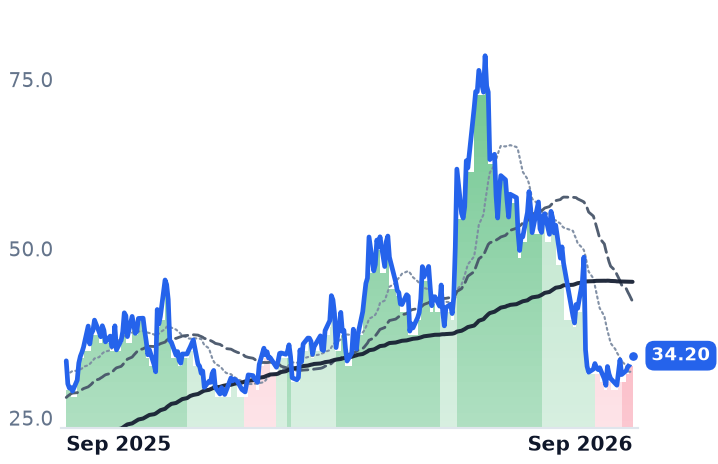
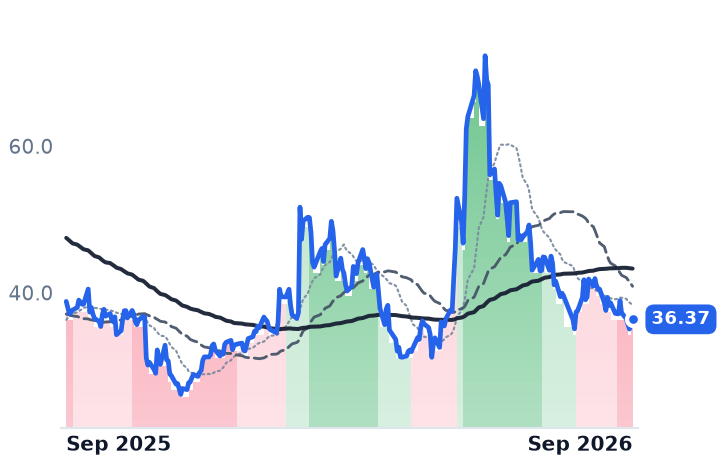
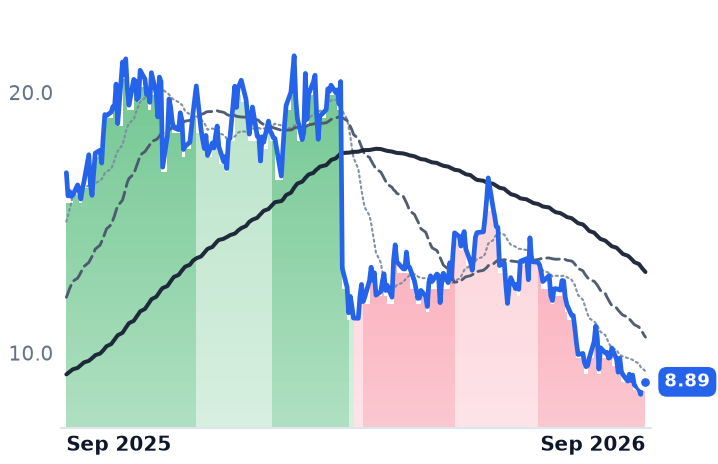
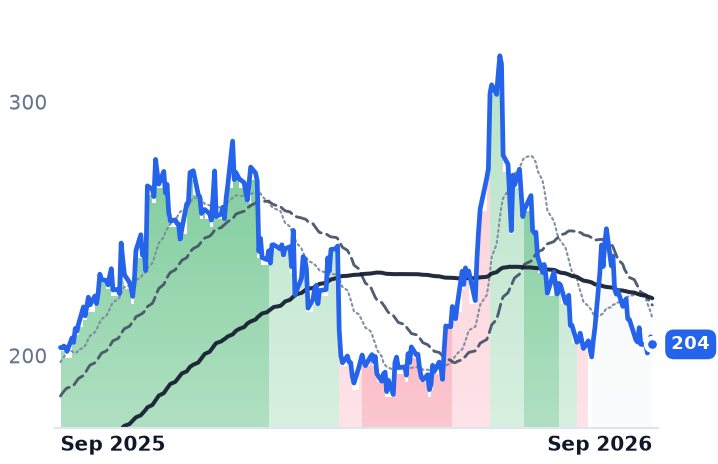
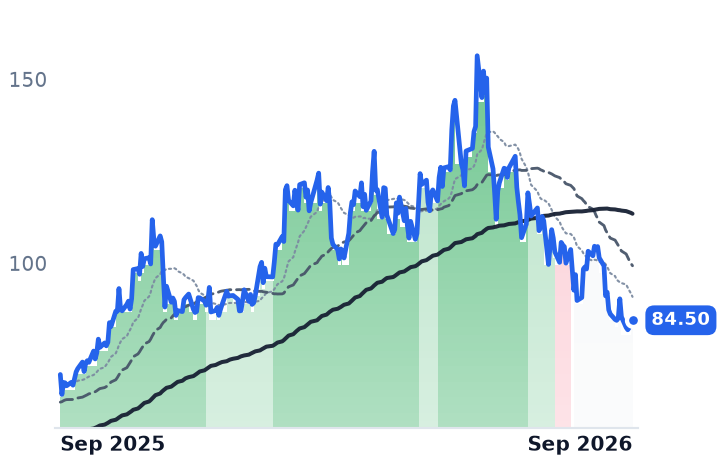
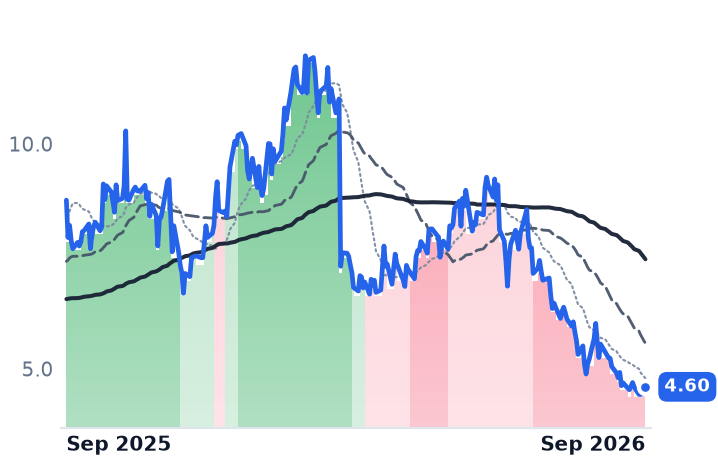
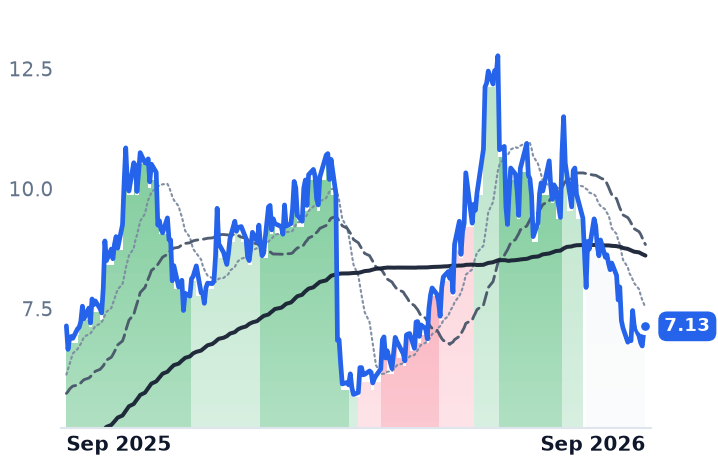
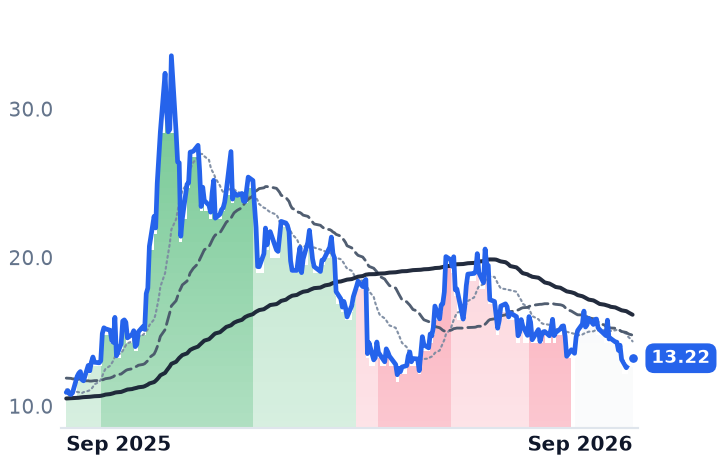
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SEDG | $2.1B | n/m | — | 1.6x | 1.6x | 7.0x | 7.1x | n/m | 4.3% |
ENPH | $4.8B | 35.7x | 18.2x | 3.6x | 4.0x | 7.7x | 8.6x | 27.5x | 3.2% |
RUN | $2.1B | 5.2x | 7.0x | 0.6x | 0.7x | 1.8x | 2.0x | 23.4x | -64.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLR | $22.7B | 13.0x | 11.9x | 4.2x | 4.5x | 9.6x | 10.2x | 8.6x | 5.1% |
NXT | $14.9B | 24.7x | 21.2x | 4.1x | 3.5x | 12.3x | 10.4x | 18.3x | 3.7% |
ARRY | $807.6M | n/m | 7.2x | 0.7x | 0.6x | 2.8x | 2.3x | 301.0x | 12.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SHLS | $1.4B | 45.8x | 21.0x | 2.5x | 2.3x | 7.7x | 7.2x | 23.5x | -3.6% |
CSIQ | $1.2B | n/m | — | 0.2x | 0.2x | 1.2x | 1.1x | 24.7x | -136.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SEDG | Revenue | +12.0% | +11.1% | +11.4% |
| EPS | −86.2% | −370.0% | +91.7% | |
ENPH | Revenue | −19.1% | +6.2% | +10.8% |
| EPS | −28.8% | +14.0% | +18.9% | |
RUN | Revenue | +29.7% | +3.5% | +12.9% |
| EPS | −8.2% | −65.9% | −38.3% | |
FSLR | Revenue | −1.1% | +17.0% | +11.0% |
| EPS | +21.1% | +34.6% | +22.8% | |
NXT | Revenue | +22.3% | +22.3% | +18.0% |
| EPS | +13.8% | +6.1% | +21.9% | |
ARRY | Revenue | +14.9% | +9.8% | +5.6% |
| EPS | +9.8% | +23.8% | +13.9% | |
SHLS | Revenue | +32.7% | +9.1% | +11.0% |
| EPS | +5.1% | +27.4% | +16.3% | |
CSIQ | Revenue | +9.9% | +17.4% | +6.5% |
| EPS | −38.6% | −236.1% | +107.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
SolarEdge Technologies, which sells string inverters paired with per-panel power optimizers, plus batteries and monitoring software, to installers and electrical wholesalers, told investors on August 5 that its September quarter would bring in less revenue than its June quarter. The shares fell 28.1% that day, from $48.76 to $35.08, on 13.3m shares against a normal two to four million. The results underneath that guidance were the best the company had printed since 2023.
The gap between the quarter and the guide is the whole argument on this stock, and it gets its next test on Thursday, when the company webcasts a 2026 investor day at 10:00 EDT at which management has said it will detail safe-harbour transactions in residential and commercial solar and how it thinks about revenue from its solid-state transformer work.
The quarter behind the guide
June-quarter revenue was $346.2m, up 19.6% year on year and 11.5% sequentially — a fourth consecutive sequential gain off the $170.7m trough of December 2024. Reported gross margin reached 27.5%, against 11.1% a year earlier and deeply negative at the trough. Non-GAAP gross margin of 28.6% marked a sixth straight quarter of expansion, and non-GAAP operating income of $10.2m was the first quarterly profit in nearly three years. Free cash flow was $3.1m, against $601.6m of cash.
Two things sit inside that margin. The first is $13.3m of tariff refunds, roughly four points, the same kind of non-demand credit that flatters inverter income statements across the industry. The second is what is absent: management said there was no material safe-harbour pull-forward in the quarter, so the growth reflects equipment installers actually needed.
The September guide of $310-340m assumes about $15m of European seasonality, continued US residential weakness and no repeat of the refunds — though $11.5m arrived in July. That is how a 28.6% margin becomes a 22-26% guide.
Why the US half is stuck
US residential revenue of $154.9m fell 2% sequentially, blamed on slow tax-equity funding and unresolved foreign-entity rules squeezing installer cash flow. The mechanism is federal. The Section 25D credit that paid homeowners 30% of system cost expired outright on December 31, 2025, while the commercial 48E credit survives for leases and power purchase agreements, so federal money now flows only to systems somebody else owns. Wood Mackenzie and the Solar Energy Industries Association see US residential installations falling 21% this year, with third-party-owned share rising to 65% from 44%. The financiers who now buy the hardware cannot close until they know the content rules: Treasury's interim guidance in Notice 2026-15 requires at least 40% of project value from non-prohibited foreign sources, with fuller regulations still pending.
Europe is carrying the company in the meantime: revenue of $154.4m rose 36% sequentially and more than doubled year on year, and the new Nexis three-phase platform shipped more than $60m there in the quarter, with a single-phase version due in the first quarter of 2027.
The mirror
Enphase, whose microinverters convert power at each individual panel, is the opposite case. Its June revenue fell 19.6%, US sell-through fell 34%, and $84.3m of the quarter — 29% — was safe-harbour equipment for projects whose revenue is not recognized until 2028. "We are not stopping and waiting. We are not waiting for things to improve," chief executive Badri Kothandaraman told investors on July 28. The shrinking company still carries the richer multiple: Enphase at 7.71x trailing gross profit and 8.63x forward — the forward reading above the trailing one, meaning gross profit is priced to fall further — against 7.04x trailing and 7.11x forward for SolarEdge. Both stood near 16x in mid-May. The duopoly they once split is also gone: Wood Mackenzie's 2025 review put Enphase at 31.7% of US residential inverters, SolarEdge at 31.3% and Tesla Energy at 29.6%.
What the derating earns
SolarEdge earns part of its fall on the guide itself. A business whose September quarter shrinks sequentially after four gains is not compounding yet, and its margin promise leans on refunds it declines to forecast. The rest it does not earn alone: measured from June 5 to September 4, eight of eight listed solar names fell between 23% and 46%, so most of what happened to this multiple happened to everything wearing the label. The likelier reading is broad compression laid on top of a real, policy-driven hole in US demand. What keeps the recovery case fragile is leverage — $337m of 2.25% notes due 2029, whose conversion conditions were satisfied during the June quarter, leaving them convertible at holders' option through September 30.
Enphase has already put a number on its safe-harbour book: roughly $1.1bn of agreements, most of the revenue arriving in 2028. SolarEdge has said only that it had none in the June quarter. Thursday is the day it says what it has instead.