

BWXT Raised All Four 2026 Guidance Lines; Centrus's Operating Income Fell 69%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two companies sit inside the same "nuclear fuel cycle" label and are moving for opposite reasons, and neither is paid by the AI data-center buildout the label invokes. BWX Technologies builds naval reactors and fuel for the US Navy; it ended the June quarter with $8.4bn of backlog, up 40%, and raised every 2026 guidance line — yet its reported operating income has now fallen year over year for four straight quarters and its gross margin slipped to 22.4% from 25.1%. Centrus Energy resells enrichment it does not yet make: revenue grew, but separative-work volumes fell 23% and diluted shares rose 20.8% to fund a plant that starts in 2029.
The judgment splits. Centrus's share decline is matched by its earnings — consensus 2026 earnings of $2.54 a share against $3.90 delivered in 2025. BWXT's is not: estimates went up while the multiple came down.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
BWXT | BWX Technologies | Naval & Shipbuilding | ⚠️ Emerging Bear | −6.7% | −3.5% |
LEU | Centrus Energy | Uranium | ⚠️ Emerging Bear | −8.4% | −15.0% |
| Compared against · context, not the story | |||||
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | +3.4% | +30.7% |
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −7.9% | −41.6% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | +4.9% | −71.4% |
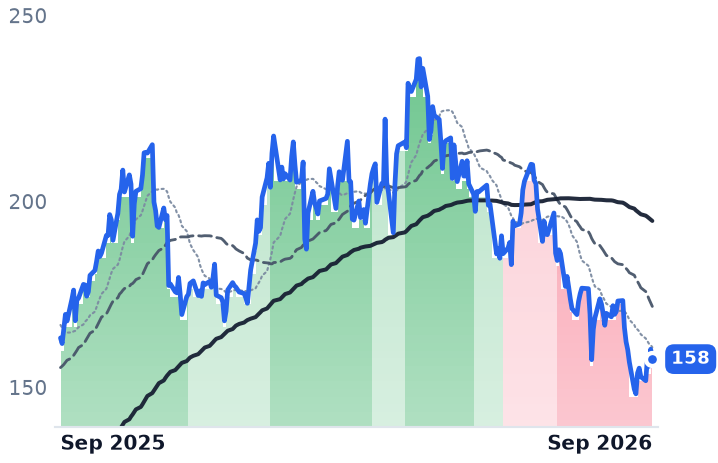
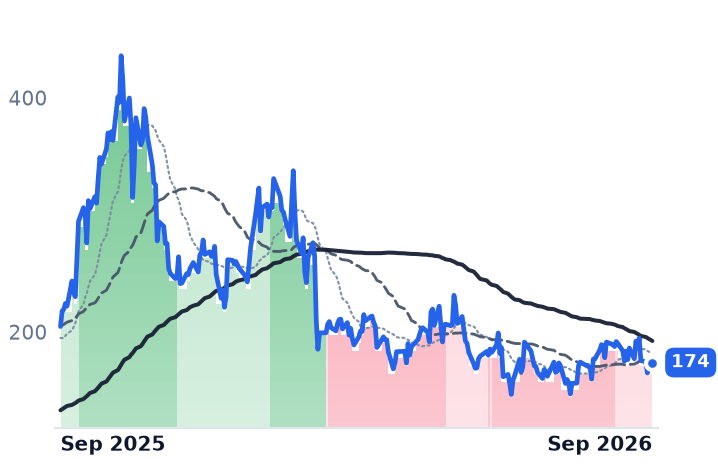
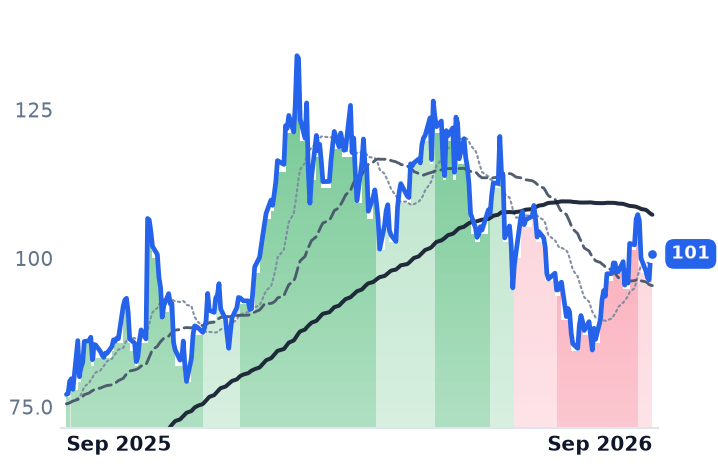
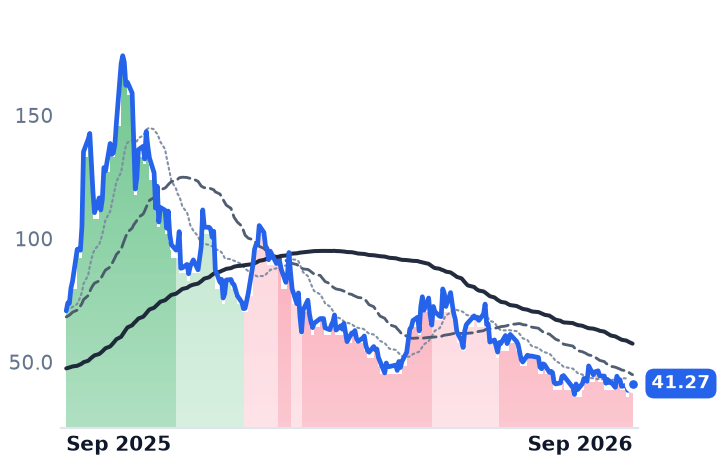
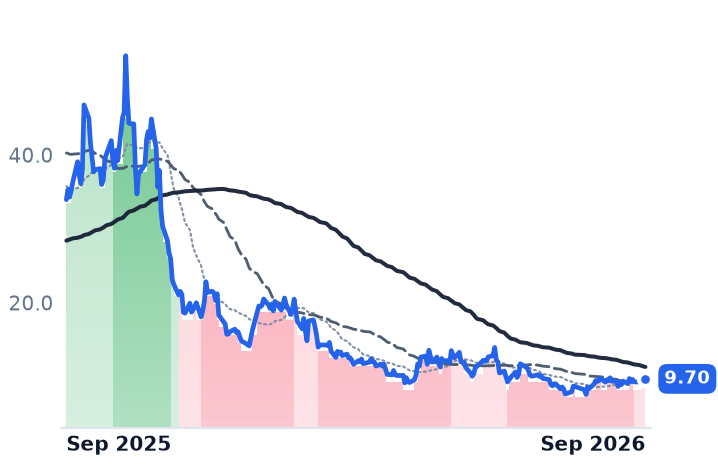
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $14.4B | 40.6x | 33.2x | 4.1x | 3.8x | 18.6x | 17.2x | 28.6x | 2.2% |
LEU | $3.3B | 69.3x | 68.5x | 7.0x | 7.0x | 29.9x | 30.1x | 35.8x | -6.7% |
CCJ | $42.0B | 163.2x | 62.6x | 16.7x | 11.8x | 60.7x | 42.9x | 67.3x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKLO | $7.3B | n/m | — | — | — | — | — | n/m | -3.8% |
SMR | $2.8B | n/m | — | 261.9x | 91.1x | — | 432.7x | n/m | -27.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWXT | Revenue | +20.6% | +9.6% | +7.0% |
| EPS | +24.1% | +11.6% | +11.7% | |
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.4% | +12.2% | −22.3% | |
CCJ | Revenue | +3.6% | +10.9% | +7.7% |
| EPS | +7.3% | +69.4% | +25.2% | |
OKLO | Revenue | — | +241.0% | +577.4% |
| EPS | +50.0% | +10.3% | +16.5% | |
SMR | Revenue | −26.7% | +434.9% | +101.2% |
| EPS | −74.7% | +33.4% | −18.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
BWX Technologies is taking orders faster than it is converting them into profit. The company that makes the reactors and fuel for every US Navy submarine and carrier closed the June quarter with $8.4bn of backlog, up 40% year over year on a trailing book-to-bill of 1.7 times, and on 3 August raised its full-year revenue, adjusted profit, earnings and cash flow guidance. In the same quarter its reported operating income fell 12.2%, the fourth consecutive year-over-year decline.
That gap is the story in the corner of the nuclear complex that the market has been marking down hardest. Two names carry it — BWXT and Centrus Energy, the only US-owned commercial uranium enricher — and neither sells fuel to a data center. One is paid by the Pentagon, the other by the Department of Energy and a handful of utilities. What separates them is whether the falling share price is describing the income statement or ignoring it.
The defense manufacturer with a margin problem
BWXT's June-quarter revenue reached $901.6m, up 18%, but the growth is not where the label suggests. Government Operations — naval reactors, nuclear fuel, special materials — grew 2% and still supplied roughly two-thirds of revenue and about 78% of segment operating profit. Commercial Operations grew 72%, only a third of that organically; the rest came from the Kinectrics and Precision Components acquisitions. Gross margin compressed to 22.4% from 25.1%, and consolidated operating margin to 10.0% from 13.4%. The pattern predates the deals: 2025 operating income fell 15.1% on revenue up 18.3%.
Management's own guidance explains part of it. The 2026 Commercial Operations profit-margin guide was cut to about 13% from about 14% on capacity expansion and hiring, with recovery pushed to 2027 — the segment carrying the growth is absorbing the capital spending. Meanwhile the demand side keeps arriving: the Defense Department awarded $76.6bn on 30 July for five Columbia-class and nine Virginia-class boats, and on 26 August the Army picked BWXT's BANR design for its Janus microreactor program, a 20-megawatt unit at Fort Campbell targeting groundbreaking in late 2028. "Demand for nuclear solution continues to build across the national security and global commercial power markets," chief executive Rex Geveden told investors on the August call.
The shares have gone the other way, grinding down through every trend stage since May and closing at $157.59 on 4 September, a third below April's high. Consensus 2026 earnings were revised up to $4.74 a share from the $4.05 carried in early May. Forward earnings multiple: 33.2 times, against roughly 46 times in mid-May, with price to gross profit at 18.6 times trailing against 24.7 times then.
The enricher whose earnings fell with the price
Centrus is the mirror. June-quarter revenue rose 14% to $176.1m, but gross margin fell to 28.3% from 34.9% and operating income dropped 69% to $10.4m. The enrichment segment grew 22% only because it resold $53.4m of natural uranium; separative-work volumes fell 23% and realized enrichment pricing rose 3%, against a US market where the average price paid rose 11% in 2025 to $108.70 per separative work unit. The cost-reimbursed DOE line shrank 21%.
"We are seeing strong demand signals across all 3 of our addressable markets, commercial LEU, national security and HALEU," chief executive Amir Vexler said on the August 6 call, describing utilities as still waiting on centrifuge delivery. Backlog is $4.5bn stretching to 2040; commercial production starts in 2029. Funding it has cost shareholders 20.8% dilution year over year, with $53.9m drawn in the quarter under an at-the-market program authorized for up to $1bn. Consensus sees 2026 earnings of $2.54 a share against $3.90 delivered last year. The stock is 60% below its October 2025 high and its forward earnings multiple, 68.5 times, is indistinguishable from trailing.
What the split means
Cameco, the uranium miner sitting in the same grouping, is the counterexample that isolates the effect: its June-quarter net income fell 92% to $25.2m and its shares are up 32% over twelve months at 62.6 times forward earnings. Commodity price beats income statement there. For BWXT and Centrus, the meter that matters is a contract schedule.
Centrus's de-rating is earned — profit is falling roughly as fast as the price, and the share count is rising underneath both. BWXT's is not explained by anything in its order book; a growing backlog and rising estimates coexist with four quarters of shrinking operating income, and a 30-year Treasury yield at 5.27% on 1 September does more to explain the timing than any company disclosure, since the AP1000 content and the Fort Campbell reactor both pay out in the 2030s.
The question BWXT has not yet answered is whether the margin compression is the cost of building capacity for that decade or the price of winning work at thinner terms. Backlog does not settle it. The next income statement might.