

UGI's Propane Gallons Fell 10%, and Twelve Days Later KKR Bid $9bn for the Company
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
KKR has offered to buy a company whose earnings are going the wrong way. Its unsolicited approach values UGI at $42.50 a share, and the stock still trades below that — the market's price on a deal that may never close. UGI's year-to-date adjusted earnings are $3.17 a share against $3.55 a year ago, and its own fiscal 2026 guidance implies a down year.
Underneath, the propane arithmetic splits the two big operators. Suburban Propane's retail gallons slipped less than 2% and its cents-per-gallon margin held; UGI's AmeriGas sold 10% fewer gallons and widened its segment loss. What a buyer would mostly be paying for sits outside the propane truck fleet — a Pennsylvania rate base with an approved $65m two-step increase, a midstream desk, and a European liquefied petroleum gas platform.
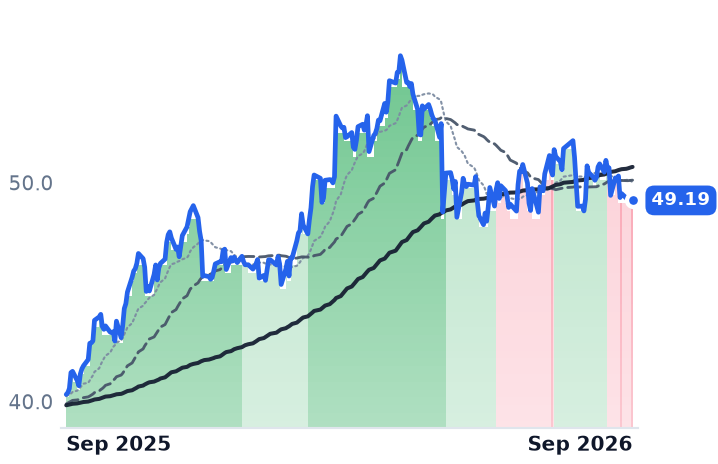
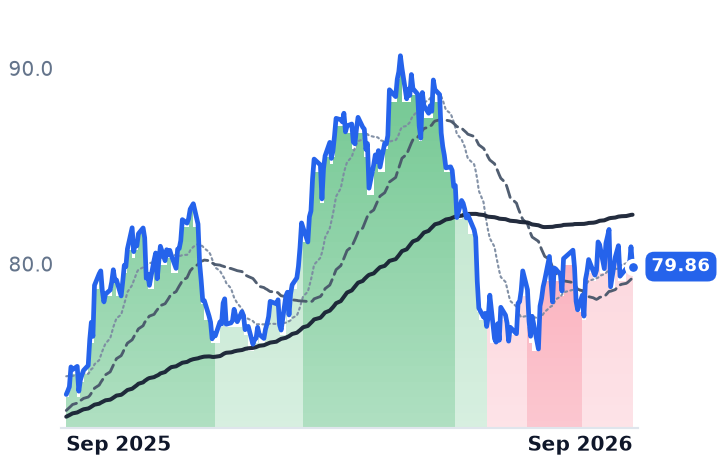
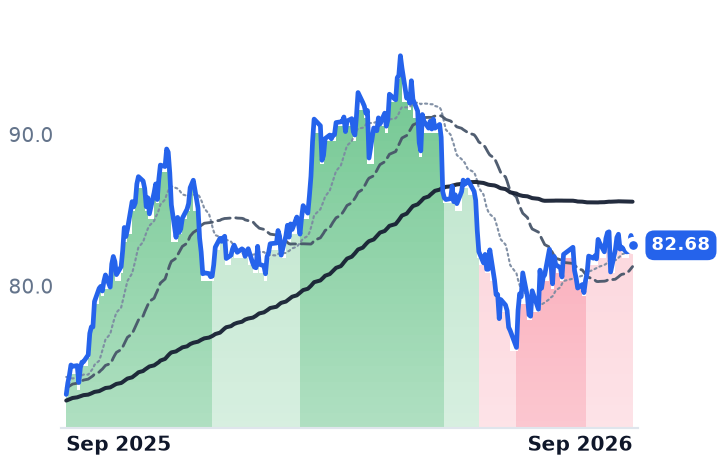
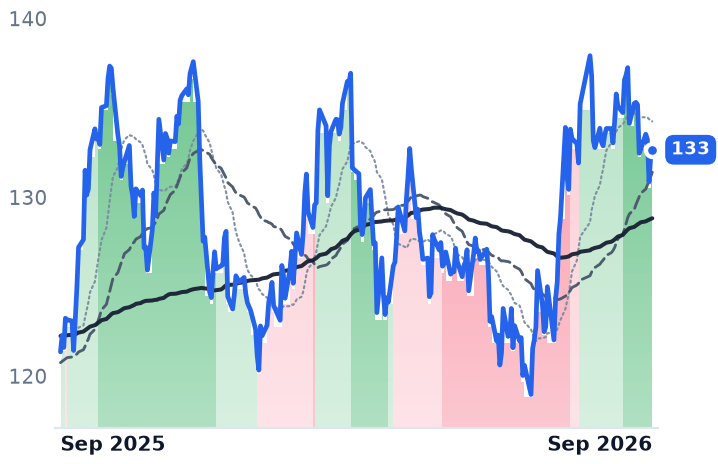
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
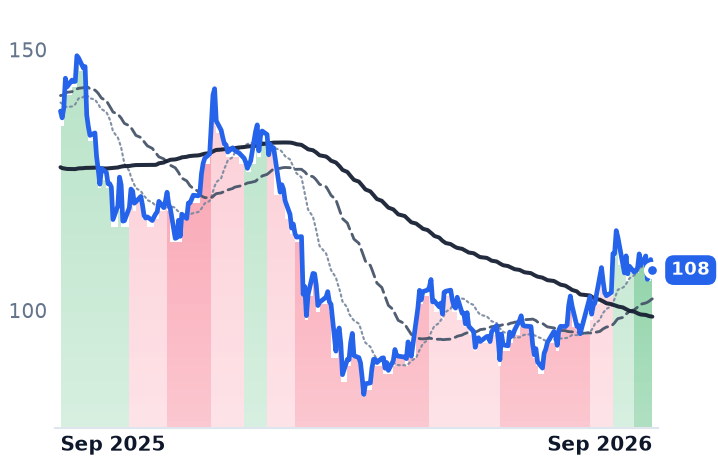
UGI | UGI | Propane & Liquid Fuels | ⚠️ Emerging Bear | +11.0% | +14.1% |
SPH | Suburban Propane Partners | Propane & Liquid Fuels | ⚠️ Emerging Bear | −1.1% | +0.5% |
| Compared against · context, not the story | |||||
ATO | Atmos Energy | Natural Gas Distribution | ⚠️ Emerging Bear | −1.5% | +3.4% |
NJR | New Jersey Resources | Natural Gas Distribution | 🟢 Cont. Bull | −2.9% | +18.9% |
NWN | Northwest Natural | Natural Gas Distribution | ⚠️ Emerging Bear | −2.5% | +22.0% |
OGS | ONE Gas | Natural Gas Distribution | ⚠️ Emerging Bear | −0.4% | +8.9% |
SR | Spire | Natural Gas Distribution | ⚠️ Emerging Bear | +0.9% | +13.5% |
CPK | Chesapeake Utilities | Natural Gas Distribution | 🟢 Cont. Bull | −0.9% | +9.3% |
KKR | KKR | Alternative & Private Capital | 🔴 Cont. Bear | +4.8% | −22.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UGI | $8.1B | 12.2x | 13.6x | 1.1x | 1.1x | 2.4x | 2.4x | 9.3x | 2.3% |
SPH | $1.2B | 8.9x | 8.8x | 0.8x | 0.8x | 2.1x | 2.1x | 9.0x | 10.8% |
ATO | $28.0B | 19.8x | 19.8x | 5.7x | 5.4x | 9.3x | 8.9x | 14.1x | -7.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NJR | $5.4B | 14.7x | 14.9x | 2.4x | 2.4x | 8.5x | 8.6x | 11.7x | 1.4% |
NWN | $2.1B | 16.4x | 16.3x | 1.6x | 1.5x | 3.6x | 3.4x | 9.9x | -12.6% |
OGS | $5.0B | 17.2x | 16.3x | 2.2x | 2.0x | 2.9x | 2.7x | 10.7x | -3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SR | $4.8B | 9.1x | 20.3x | 1.9x | 1.9x | 5.8x | 5.7x | 5.6x | -4.2% |
CPK | $3.2B | 21.3x | 20.9x | 3.2x | 3.2x | 6.5x | 6.3x | 13.6x | -8.7% |
KKR | $102.4B | 33.9x | 18.4x | 4.8x | 9.7x | 10.4x | 20.8x | 15.1x | 8.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
UGI | Revenue | −1.5% | +5.7% | +1.9% |
| EPS | −12.0% | +16.4% | +8.1% | |
SPH | Revenue | −3.3% | +3.8% | +1.0% |
| EPS | +13.7% | +2.5% | +3.4% | |
ATO | Revenue | +6.8% | +7.7% | +8.7% |
| EPS | +14.2% | +6.8% | +8.4% | |
NJR | Revenue | +12.2% | −2.8% | +4.5% |
| EPS | +10.1% | −5.1% | +8.2% | |
NWN | Revenue | +5.0% | +6.9% | +3.6% |
| EPS | +5.3% | +5.0% | +5.8% | |
OGS | Revenue | −3.2% | +3.5% | +2.9% |
| EPS | +11.8% | +3.3% | +8.4% | |
SR | Revenue | +1.8% | +12.4% | +4.9% |
| EPS | −11.0% | +36.6% | +12.3% | |
CPK | Revenue | +16.5% | +5.1% | +3.6% |
| EPS | +6.7% | +14.3% | +7.4% | |
KKR | Revenue | +33.9% | +17.8% | +32.9% |
| EPS | +26.0% | +18.0% | +15.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
AmeriGas sold 10% fewer gallons of propane in the June quarter than a year earlier, and the segment's loss at the earnings line nearly doubled. Twelve days after its parent, UGI Corporation, laid that out on an August 6 call, the Wall Street Journal reported that KKR had made an unsolicited proposal to buy the whole company for roughly $9bn, or $42.50 a share. KKR declined to comment; UGI did not immediately respond.
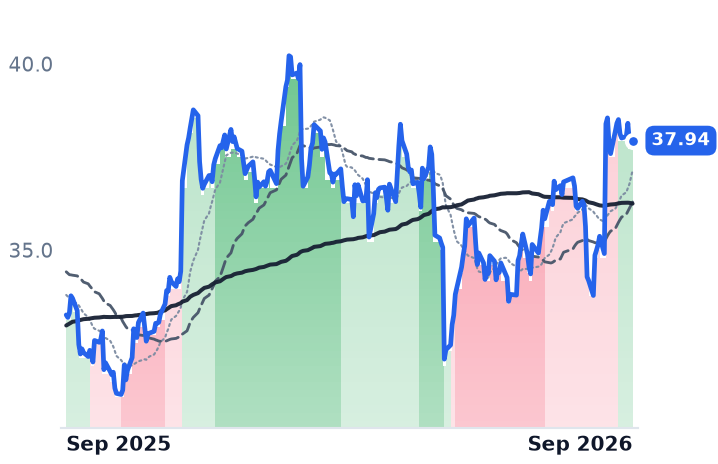
That is the stake. UGI closed at $37.94 on September 4, 12% below the reported offer, which is the market's honest statement that a deal at that price is not assured. It also raises the question of what a buyer is actually buying, because the segment the company is best known for is the one shrinking.
Gallons times cents
A propane distributor does not make money on propane. The molecule is bought wholesale and passed through; the income statement is retail gallons multiplied by a cents-per-gallon unit margin set locally. Gallons are weather times a customer base, and this year the weather was hostile — April was near-record warm, and Suburban Propane's territories ran 17% warmer than normal in the quarter. The commodity, meanwhile, was abundant: US propane and propylene inventories sat 32% above their five-year average in late August, the configuration that lets a distributor hold its retail spread while its acquisition cost falls.
The two operators diverged on the second term. Suburban Propane, a master limited partnership serving about a million customers from roughly 700 locations in 42 states, sold 70.6 million retail gallons, down 1.8%, and reported total gross margin flat at $160.3m — down 2.4% excluding derivative swings, because "propane unit margins remained steady". AmeriGas, the largest US retail propane marketer by gallons sold, moved 124 million gallons and swung to a $53m segment loss. Its underlying customer book is better than the headline: attrition ran about 2% year-to-date, which management called the lowest in a very long time and which compares with the 4.2% base-business attrition Star Group reported for the twelve months to March. Neither company bought gallons to replace the leakage: no tracked retail acquisitions by the national operators in the 2025-26 year, with AmeriGas a net seller after divesting Hawaii.
What KKR would be buying
Inside UGI, the growth is regulated. The Pennsylvania utility, which delivers gas to some 672,000 customers, added more than 8,500 new heating customers year-to-date and has an approved rate settlement worth $65m in two steps — $40m from October 2026, $25m from October 2027, with a stay-out through January 2029. Utilities segment earnings rose $10m in the quarter and midstream and marketing $3m, partially offsetting propane. UGI International earned $41m on flat revenue. Three-quarters of year-to-date capital expenditure went to the natural gas businesses.
AmeriGas itself is being fixed rather than grown: net debt down roughly $270m in the quarter, a refinancing that cut a coupon to 6.875% from 9.375%, segment leverage at 4.3x. "We're very confident the leverage is going to be sub 4," chief financial officer Sean O'Brien told investors on August 6. "We think by the end of the year, we have a shot to be sub 4." Chief executive Robert Flexon added that the company plans "meaningful cash distributions to the parent in 2027, which is something that hasn't been done for some time."
None of that makes fiscal 2026 a good year. Year-to-date adjusted earnings are $3.17 a share against $3.55, guidance of $2.75 to $2.90 implies a decline, and consensus of $2.798 is 12% below last year. The shares carry 13.6x forward earnings against 12.2x trailing — the spread runs the wrong way because the earnings are falling. That is still the cheapest reading in the regulated gas group, against Atmos Energy at 19.8x forward and New Jersey Resources at 14.9x. KKR's $42.50 works out to 15.2x this year's consensus: an infrastructure price, below where the group's premium names trade.
The other propane book
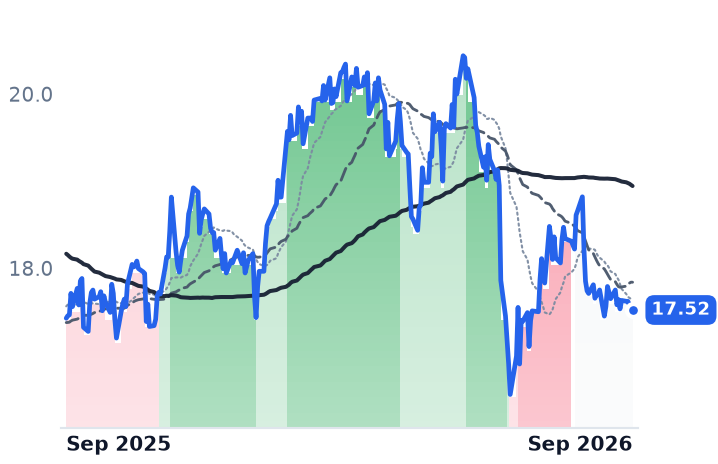
Suburban Propane has no bid and has been marked down for it, its units off about a tenth over three months while every other regulated-gas name UGI is measured against was flat to lower over the past month. The partnership's fiscal third-quarter adjusted earnings before interest, tax, depreciation and amortization fell to $18.0m from $27.0m — but that is the seasonally smallest quarter, and the heating-season half produced $258.7m, up 3.4%. Chief executive Michael Stivala attributed the quarter to "near-record warm temperatures during the month of April" and said volumes "benefited from continued strength and growth in our counter-seasonal customer base." The $0.325 quarterly distribution, a 7.4% annualized yield at $17.52, was covered 2.07 times on a trailing basis, and leverage of 4.35x is unchanged from a year ago. The renewable natural gas business injected flat volumes; two more digesters bring the count to three entering fiscal 2027, and the 38% stake in Oberon Fuels remains a venture holding rather than an earnings line.
The verdict
UGI's move this summer is a takeover re-rating, not an operating one: the business is guiding to lower earnings while the shares sit near a twelve-month high, and the 12% gap to the offer is the market pricing the chance the approach goes nowhere. What the business itself has earned is narrower and real — a rate case locked through 2029, a propane arm whose leverage and attrition are both improving faster than its gallons are falling. Suburban Propane is the same mechanism without the bid, and its unit margin, not its volume, is what has held its gross profit together.
Both companies close their books on September 30. The fiscal fourth quarter is the one where propane earns almost nothing, which makes it the cleanest look yet at whether cents per gallon can carry a business whose customers keep leaving.