

Southwest Gas and New Jersey Resources Found Their Growth Outside the Rate Base
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Both companies are filed as regulated gas distributors, and at both the marginal growth now comes from somewhere else. Southwest Gas is building a $2.3bn interstate line toward Reno with about 1 billion cubic feet a day already contracted and $270-300m of guided annual margin — none of it in the long-term guidance investors are pricing. New Jersey Resources guides 38-41% of net financial earnings to businesses outside its utility, including an unregulated wholesale gas-marketing desk whose fiscal 2026 result came from price volatility it does not control.
That difference shows up in the estimates. Consensus has New Jersey Resources earning $3.40 a share in fiscal 2027 against $3.59 in fiscal 2026, a 5.1% step down; Southwest Gas is modeled up 15.6% over the same span. The de-rating at one is earned; the premium at the other rests on a pipeline that has not yet been filed with federal regulators.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
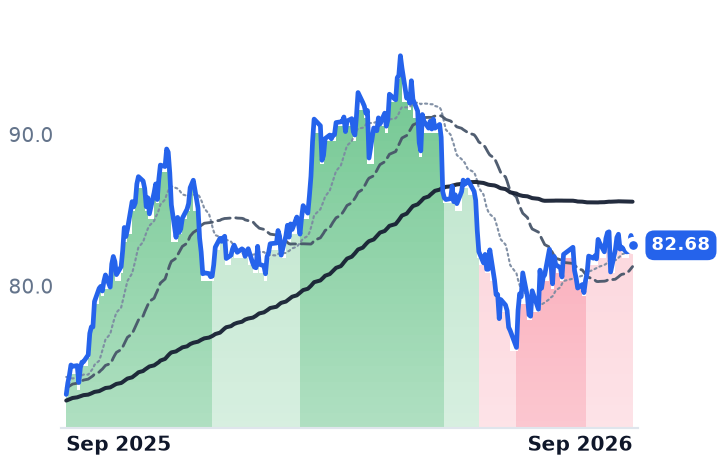
SWX | Southwest Gas | Natural Gas Distribution | 🟢 Cont. Bull | −4.4% | +15.3% |
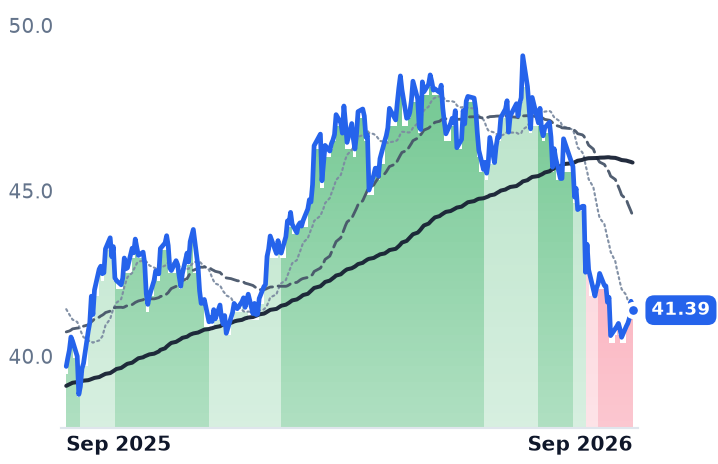
NJR | New Jersey Resources | Natural Gas Distribution | 🟢 Cont. Bull | −2.9% | +18.9% |
| Compared against · context, not the story | |||||
OGS | ONE Gas | Natural Gas Distribution | ⚠️ Emerging Bear | −0.4% | +8.9% |
ATO | Atmos Energy | Natural Gas Distribution | ⚠️ Emerging Bear | −1.5% | +3.4% |
NI | NiSource | Natural Gas Distribution | ⚠️ Emerging Bear | −2.9% | +4.3% |
SR | Spire | Natural Gas Distribution | ⚠️ Emerging Bear | +0.9% | +13.5% |
NWN | Northwest Natural | Natural Gas Distribution | ⚠️ Emerging Bear | −2.5% | +22.0% |
NFG | National Fuel Gas | Midstream Transportation & Storage | ⚠️ Emerging Bear | +3.5% | −0.6% |
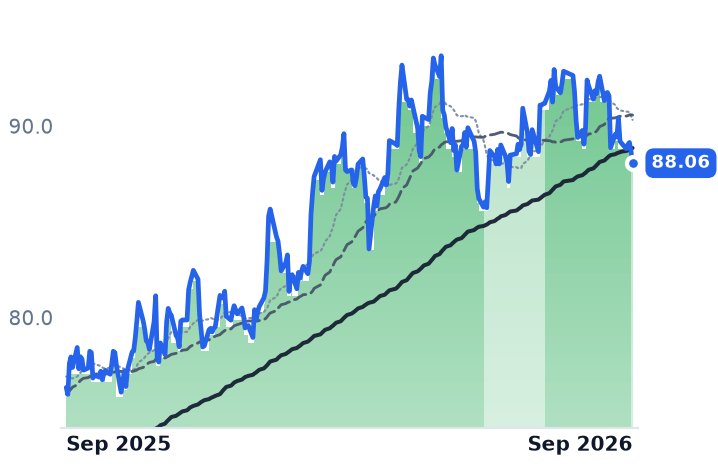
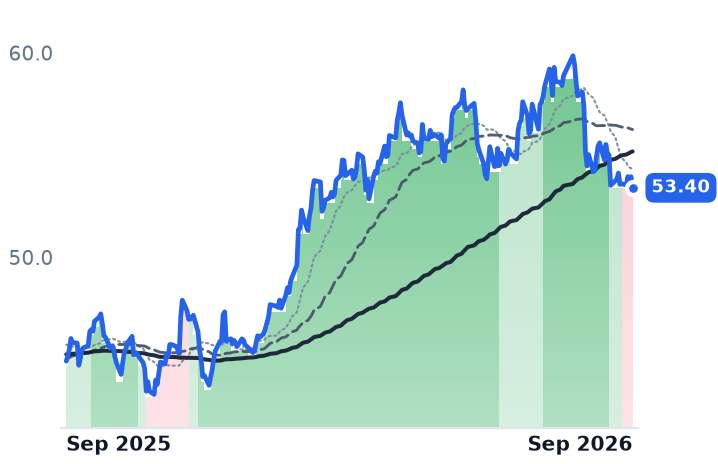
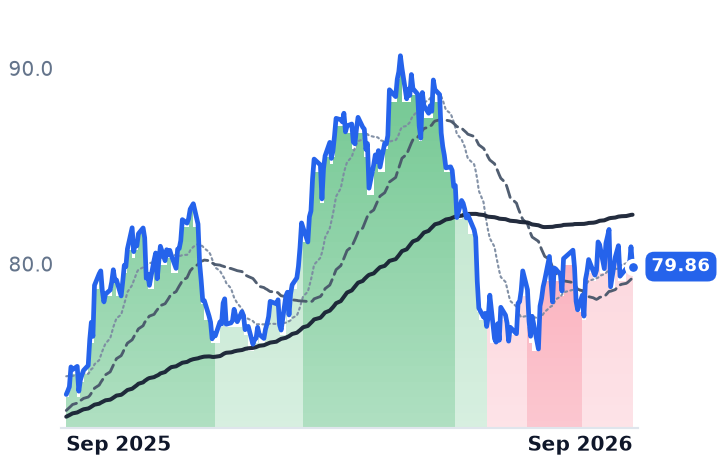
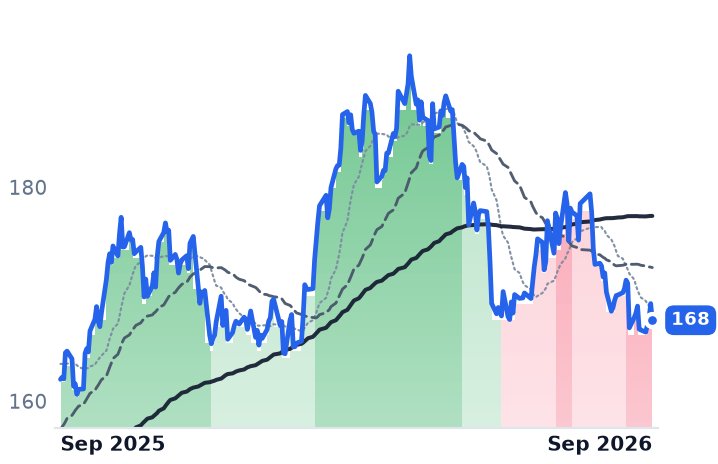
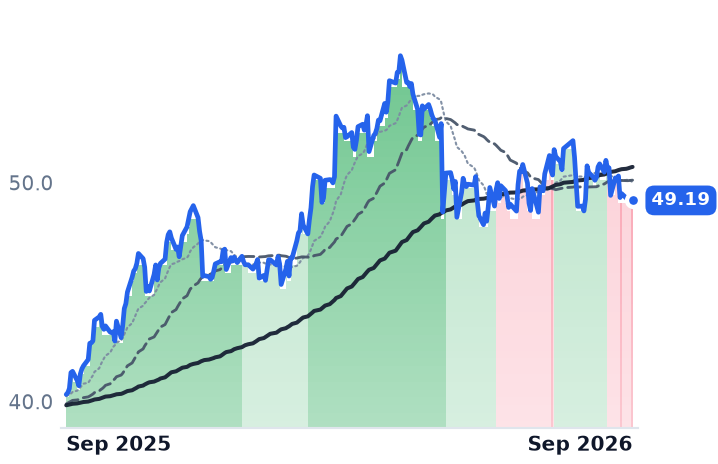
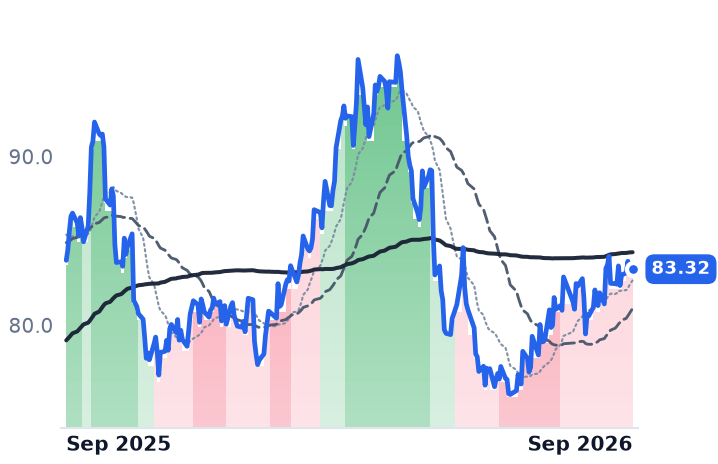
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SWX | $6.4B | 12.3x | 20.7x | 3.7x | 3.3x | 6.5x | 5.8x | 11.0x | -13.0% |
NJR | $5.4B | 14.7x | 14.9x | 2.4x | 2.4x | 8.5x | 8.6x | 11.7x | 1.4% |
OGS | $5.0B | 17.2x | 16.3x | 2.2x | 2.0x | 2.9x | 2.7x | 10.7x | -3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ATO | $28.0B | 19.8x | 19.8x | 5.7x | 5.4x | 9.3x | 8.9x | 14.1x | -7.2% |
NI | $19.7B | 21.7x | 20.0x | 2.9x | 2.8x | 5.6x | 5.5x | 11.6x | -5.5% |
SR | $4.8B | 9.1x | 20.3x | 1.9x | 1.9x | 5.8x | 5.7x | 5.6x | -4.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NWN | $2.1B | 16.4x | 16.3x | 1.6x | 1.5x | 3.6x | 3.4x | 9.9x | -12.6% |
NFG | $7.7B | 11.2x | 10.8x | 3.1x | 3.0x | 6.2x | 5.9x | 6.6x | 4.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SWX | Revenue | −46.4% | +5.8% | +6.2% |
| EPS | −22.1% | +15.6% | +19.4% | |
NJR | Revenue | +12.2% | −2.8% | +4.5% |
| EPS | +10.1% | −5.1% | +8.2% | |
OGS | Revenue | −3.2% | +3.5% | +2.9% |
| EPS | +11.8% | +3.3% | +8.4% | |
ATO | Revenue | +6.8% | +7.7% | +8.7% |
| EPS | +14.2% | +6.8% | +8.4% | |
NI | Revenue | +15.3% | +5.6% | +6.3% |
| EPS | +9.0% | +9.7% | +10.2% | |
SR | Revenue | +1.8% | +12.4% | +4.9% |
| EPS | −11.0% | +36.6% | +12.3% | |
NWN | Revenue | +5.0% | +6.9% | +3.6% |
| EPS | +5.3% | +5.0% | +5.8% | |
NFG | Revenue | +8.2% | +18.9% | −2.3% |
| EPS | +9.9% | +0.7% | +7.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Southwest Gas is building a 181-mile pipeline toward Reno, and it has deliberately kept the earnings out of the growth plan it shows investors. The Great Basin 2028 expansion runs from the Opal interconnect with the Ruby Pipeline into northern Nevada, carries roughly 1 billion cubic feet a day of contracted demand, and now carries a capital estimate raised to about $2.3bn after a switch to 48-inch pipe. Management guides it to $270-300m of annual margin from a Q4 2028 in-service date, and it is excluded from current long-term guidance.
That matters beyond one project, because the arithmetic everyone applies to a gas distributor — rate base multiplied by an allowed return on equity — no longer describes either of the segment's two best-performing names. At Southwest Gas the biggest new asset is a federally regulated interstate line serving data-center load, not distribution pipe. At New Jersey Resources, by the company's own segment guidance, 38-41% of net financial earnings sit outside the utility altogether.
The distributor that behaves like one
Southwest Gas delivers gas to about 2.16 million customers across Arizona, Nevada and California, and its June quarter was a textbook regulated result: adjusted earnings of $0.45 a share against $0.37, with operating margin up $12.7m — $6.7m of it rate relief, $4.9m recovery mechanisms and $1.4m customer growth — while operating and maintenance spending fell 3%. Net customer additions ran 1% and contributed $4.5m of margin over twelve months. The Sun Belt population story is real and small; the regulatory story is bigger.
The balance sheet that once complicated this is clear. Southwest Gas sold its last 27.4 million Centuri shares in September 2025 for roughly $525m, and lower holding-company interest added $8.6m to the June quarter. The company reaffirmed 2026 adjusted earnings of $4.17-$4.32 and 12-14% annual growth through 2030 off a $6.3bn five-year capital plan, with rate base guided to compound 9.5-11.5% a year. The February 2027 plan refresh is where the expanded pipeline scope gets added.
The distributor that behaves like a trading desk
New Jersey Resources delivers gas to roughly 564,000 customers in six New Jersey counties, and also owns a solar developer, a midstream book and an unregulated wholesale gas-marketing arm. Its fiscal third quarter swung to net financial earnings of $0.11 a share from $0.06, helped by solar projects entering service and "continued uplift at Storage and Transportation, driven by favorable recontracting activity". Storage and transportation earnings are guided to double from fiscal 2025 to fiscal 2027 after Leaf River's expansion won its federal certificate early. Guidance was narrowed upward in August to $3.52-$3.62.
And consensus still has fiscal 2027 earnings falling 5.1%, to $3.40 from $3.59, with revenue down 2.8% before growth resumes in fiscal 2028. The reason is the marketing desk: the company attributes its stepped-up contribution to higher gas-price volatility, an input with no franchise protection and no reason to repeat. On the August 4 call management called the June rate filing "plain vanilla," designed to leave bills "nearly flat" — the utility is doing exactly what utilities do. The clean-energy arm faces a harder arithmetic: the federal residential clean-energy credit lapsed on January 1, and New Jersey's incentive for newly registered systems fell to $76.50 per megawatt-hour from $85.
What the market did to both
The September pullback is not a verdict on either. Five of the seven pure-play distributors sat in downtrends on September 4, the 10-year Treasury yield reached 4.79%, and S&P 500 utilities have gone from up more than 11% through February to roughly flat, second-worst of the index's eleven industries. Over six months these two fell least — NiSource, Atmos, Spire and ONE Gas each dropped between 8% and 12%.
The multiples have already moved. New Jersey Resources trades at 14.7x trailing earnings against 17.4x in May, a compression the fiscal 2027 estimate justifies. Southwest Gas is at 20.7x forward against 28.2x in May, still the richest in the group — ONE Gas near 16x, Atmos near 20x — and what that premium buys is consensus earnings rising 15.6% next year on rate relief, then a pipeline whose margin nobody has yet been asked to model.
Great Basin's application to the Federal Energy Regulatory Commission is due before this year ends. Until it is filed, the largest growth asset at a gas distributor is a line drawn on a map of Nevada.