

CMS and DTE Are Building $60bn of Plant While Their Operating Income Shrinks
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
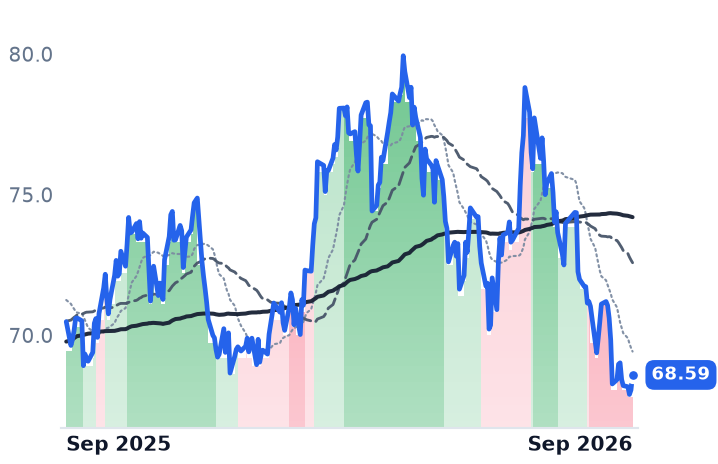
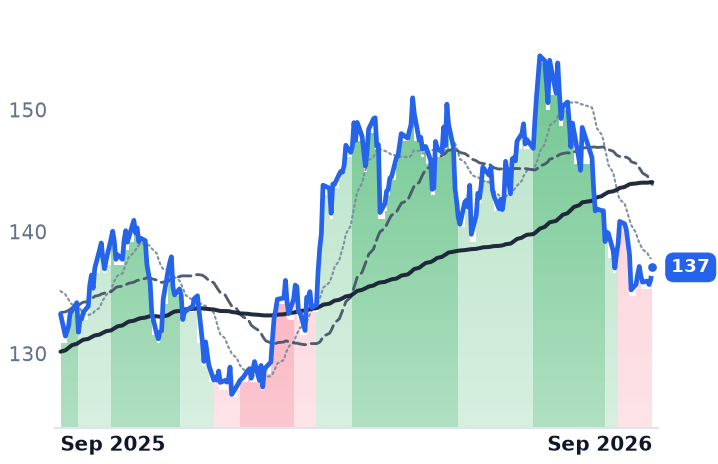
Michigan's two big regulated utilities have signed the load growth everyone wants — 2.4 gigawatts of data-center contracts at DTE, a large tariff deal at CMS — and their reported earnings are going backwards while they build for it. CMS Energy's second-quarter operating income fell 16.7% to $264m on revenue down 0.5%; DTE Energy's fell 7.3%. Both reaffirmed a 6-8% long-term growth algorithm on July 28.
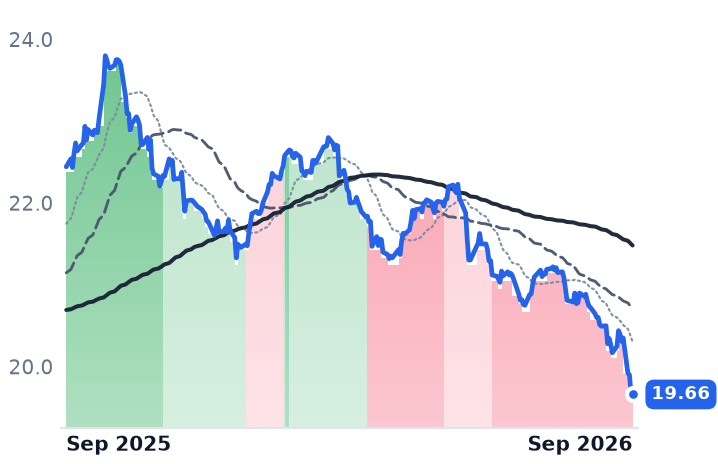
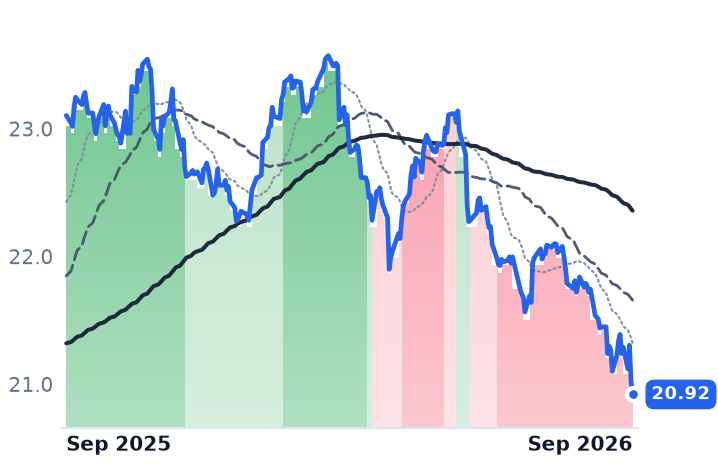
The gap is regulatory lag compounded by the cost of new money: depreciation and interest on new plant land before rate relief, and DTE issued $1bn of 6.200% junior subordinated debentures in June against outstanding retail notes struck at 4.375%. Those older notes now yield above 7% and have lost 11-15% of their price in a year. So far neither the common shares nor the paper beneath them has been paid for the capital plan.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
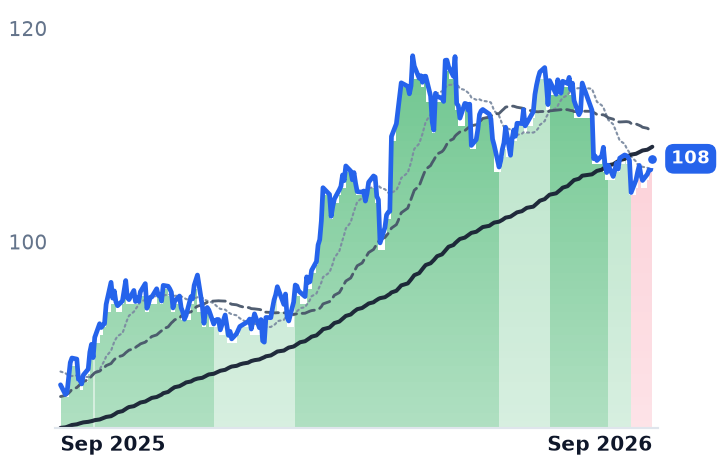
CMS | CMS Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −3.7% | −2.7% |
DTE | DTE Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −2.1% | +2.9% |
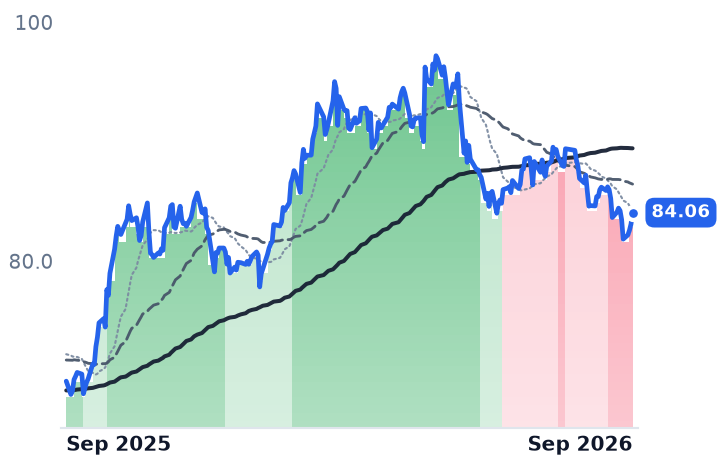
CMSA | CMS Energy Corporation 5.6% JRSUB NT 78 | Debt Securities & Instruments | ⚠️ Emerging Bear | −5.2% | −12.4% |
CMSC | CMS Energy Corporation 5.875% J | Debt Securities & Instruments | ⚠️ Emerging Bear | −3.7% | −9.5% |
CMSD | CMS Energy Corporation 5.875% Junior Subordinated Notes due 2079 | Debt Securities & Instruments | ⚠️ Emerging Bear | −5.6% | −11.1% |
DTB | DTE Energy Company 2020 Series | Debt Securities & Instruments | ⚠️ Emerging Bear | −3.8% | −11.2% |
DTG | DTE Energy Company 2021 Series | Debt Securities & Instruments | 🟢 Cont. Bull | −4.9% | −9.5% |
DTW | DTE Energy Company JR SUB DB 2017 E | Debt Securities & Instruments | ⚠️ Emerging Bear | −3.2% | −11.5% |
DUKB | Duke Energy Corporation 5.625% | Debt Securities & Instruments | ⚠️ Emerging Bear | −2.8% | −8.4% |
EAI | Entergy Arkansas, Inc. 1M BD 4.875%66 | Debt Securities & Instruments | ⚠️ Emerging Bear | −2.2% | −6.8% |
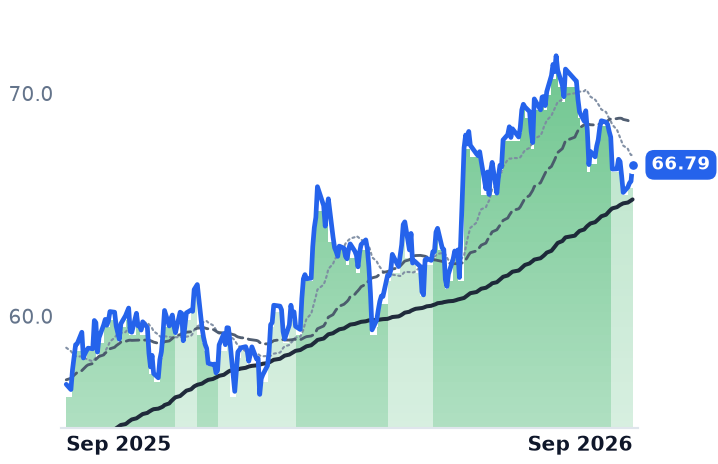
DUK | Duke Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −2.0% | +2.4% |
AEP | American Electric Power | Vertically Integrated Utilities | 🟢 Cont. Bull | −0.4% | +17.2% |
ETR | Entergy | Vertically Integrated Utilities | 🟢 Cont. Bull | +1.2% | +24.5% |
NEE | NextEra Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −0.6% | +20.2% |
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −0.0% | +17.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CMS | $21.5B | 20.3x | 17.7x | 2.4x | 2.4x | 3.5x | 3.4x | 13.0x | -8.9% |
DTE | $28.3B | 21.4x | 17.6x | 1.7x | 1.8x | 4.7x | 4.8x | 13.2x | -6.8% |
CMSA | $6.2B | 19.5x | — | 2.5x | — | 3.9x | — | 12.7x | -9.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CMSC | $7.0B | 19.5x | — | 2.5x | — | 3.9x | — | 12.7x | -9.2% |
CMSD | $7.1B | 19.5x | — | 2.5x | — | 3.9x | — | 12.7x | -9.2% |
DTB | $3.5B | 22.9x | — | 1.8x | — | 4.5x | — | 13.7x | -5.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DTG | $3.5B | 22.9x | — | 1.8x | — | 4.5x | — | 13.7x | -5.1% |
DTW | $3.8B | 22.9x | — | 1.8x | — | 4.5x | — | 13.7x | -5.1% |
DUKB | $18.5B | 18.3x | — | 2.8x | — | 4.8x | — | 11.5x | 7.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EAI | $961.4M | 5.2x | — | 0.1x | — | 0.1x | — | 0.8x | 555.4% |
DUK | $93.7B | 18.1x | 17.9x | 2.8x | 2.8x | 4.1x | 4.1x | 11.4x | 1.6% |
AEP | $67.8B | 21.4x | 19.5x | 3.0x | 2.9x | 6.1x | 5.9x | 14.1x | 13.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETR | $48.8B | 26.4x | 23.8x | 3.6x | 3.5x | 9.3x | 9.0x | 14.2x | -6.4% |
NEE | $175.3B | 18.8x | 20.9x | 6.0x | 5.7x | 8.4x | 7.9x | 16.0x | -5.8% |
D | $58.6B | 23.0x | 18.6x | 3.2x | 3.2x | 6.5x | 6.5x | 15.2x | -11.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CMS | Revenue | +10.8% | +3.9% | +4.7% |
| EPS | +7.8% | +7.4% | +7.8% | |
DTE | Revenue | +14.8% | +3.1% | +3.7% |
| EPS | +6.6% | +8.2% | +7.9% | |
CMSA | Revenue | +6.3% | +4.5% | +3.6% |
| EPS | +7.8% | +7.8% | +7.8% | |
CMSC | Revenue | +6.3% | +4.5% | +3.6% |
| EPS | +7.8% | +7.8% | +7.8% | |
CMSD | Revenue | +6.3% | +4.5% | +3.6% |
| EPS | +7.8% | +7.8% | +7.8% | |
DTB | Revenue | +8.0% | +4.8% | +1.8% |
| EPS | +6.7% | +7.2% | +8.3% | |
DTG | Revenue | +8.0% | +4.8% | +1.8% |
| EPS | +6.7% | +7.2% | +8.3% | |
DTW | Revenue | +8.0% | +4.8% | +1.8% |
| EPS | +6.7% | +7.2% | +8.3% | |
DUKB | Revenue | +3.5% | +3.8% | +3.1% |
| EPS | +6.2% | +6.7% | +6.8% | |
DUK | Revenue | +5.8% | +4.6% | +4.2% |
| EPS | +6.3% | +6.9% | +7.0% | |
AEP | Revenue | +9.5% | +5.9% | +7.6% |
| EPS | +7.9% | +7.6% | +10.6% | |
ETR | Revenue | +8.6% | +9.7% | +9.6% |
| EPS | +12.3% | +15.9% | +13.5% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.0% | +8.5% | |
D | Revenue | +13.3% | +6.3% | +5.7% |
| EPS | +5.0% | +6.3% | +7.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The plant arrives before the rate case
CMS Energy, the Michigan holding company whose Consumers Energy unit serves 1.9 million electric and 1.8 million gas customers, reported second-quarter operating income of $264m, down 16.7% from a year earlier on revenue that barely moved at $1.83bn. Its operating margin fell to 14.4% from 17.2%. DTE Energy, which serves 2.3 million electric customers in southeastern Michigan and 1.3 million gas customers statewide, saw operating income fall 7.3% to $396m. Both companies reaffirmed a 6-8% long-term earnings growth algorithm on their July 28 calls.
The two are in the middle of the largest construction programs they have ever run. DTE's five-year capital plan rose to $36.5bn from $30bn, with $30bn at DTE Electric; CMS's utility plan runs to $24bn through 2030 and supports 10.5% annual rate-base growth. The accounting for that plant lands before the revenue does — depreciation and financing costs hit the quarter they are incurred, while rate relief arrives on the commission's schedule. Both companies now show deeply negative trailing free-cash-flow yields, minus 8.9% at CMS and minus 6.8% at DTE, which is simply capital spending running ahead of operating cash flow. That gap has to be financed.
The load is signed; the earnings are not
The demand side is not in doubt. DTE has 2.4 gigawatts of signed data-center agreements — 1.4 GW with Oracle under construction and 1.0 GW with Google awaiting Michigan Public Service Commission approval expected in September — plus a further 2 GW in advanced discussion. Management said on the July 28 call that the signed contracts get it to "solidly 8%" earnings growth. CMS has contracted 135 megawatts of manufacturing and industrial load year to date and signed a large data-center tariff agreement whose customer is still evaluating multiple Michigan sites, with zoning approval pending.
What that build costs is the newer part of the story. DTE told investors it is "targeting $500-600M annual equity issuances 2026-2028 with similar levels through 2030" while "maintaining FFO to debt ratio ~15% and investment-grade rating." CMS filed a $3.0bn at-the-market common equity program with forward sales on May 13 and has completed roughly $495m of a planned $700m of 2026 equity. Common shareholders are being asked to fund this directly, not spared.
The hybrid layer is a supplement. On June 18 DTE sold $1.0bn of 2026 Series C 6.200% reset-rate junior subordinated debentures due 2058, deferrable for up to ten years; Fitch rated them BB+ and gave them 50% equity credit. That is the price of half-equity today: 6.200%, against a Michigan allowed return on equity of 9.9%.
What that repricing did to the retail notes
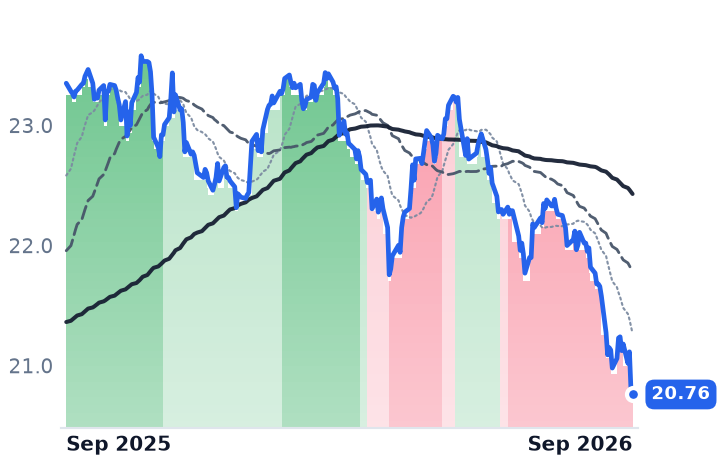
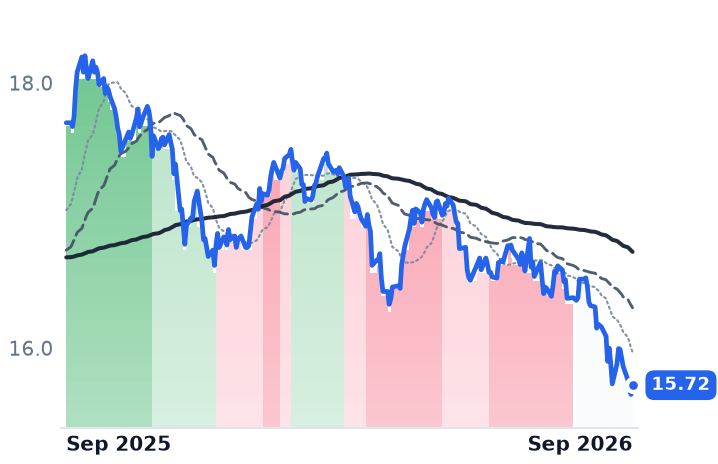
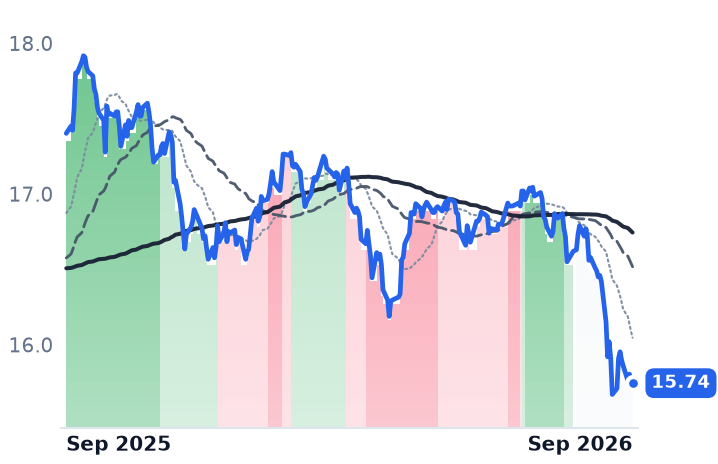
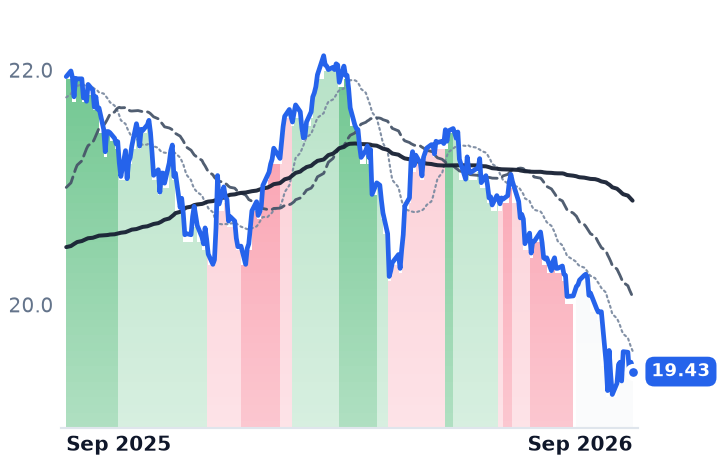
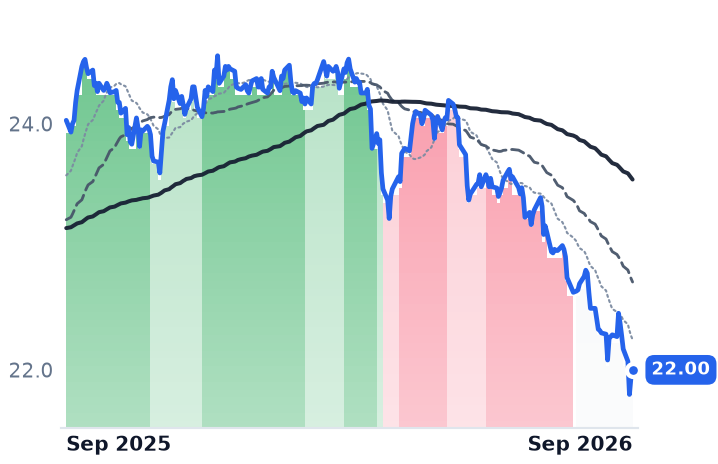
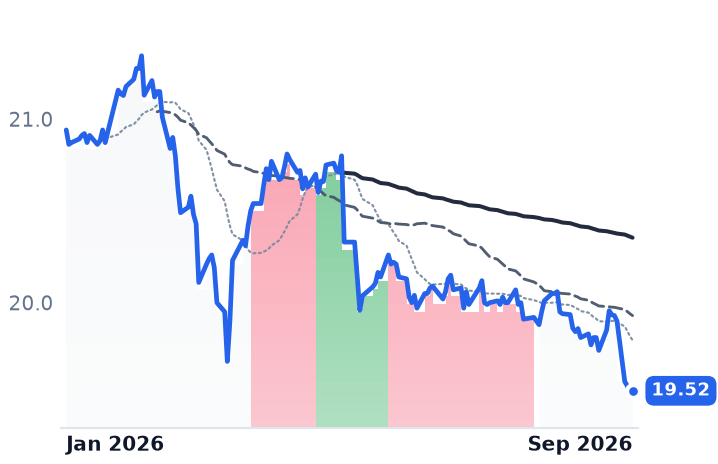
Six $25-par junior subordinated notes from these two issuers trade on the exchange — CMSA at 5.625%, CMSC and CMSD at 5.875%, DTW at 5.25%, DTB and DTG at 4.375%, all struck between 2017 and 2021. Their prices fell between 11.4% and 14.7% over the twelve months to September 3, DTW to $19.43 and DTB to $15.72. Those price series exclude coupons; including them, holders lost roughly 5.2% to 9.0%.
The cause is arithmetic. To yield what the market now demands of utility hybrids, a note paying a fixed $1.09375 a year on $25 of face has to trade near $15.72. Current yields on the six now run 6.76% to 7.15%, up 71 to 100 basis points in a year, against about 40 basis points on the 30-year Treasury, which touched 5.31% on August 17, its highest since 2007. That leaves 30 to 60 basis points of spread widening — modest, and uniform across issuers. Duke Energy's comparable 5.625% debentures fell 11.1% over the same period. Credit is not the explanation: S&P affirmed DTE at BBB+ with a stable outlook after the Oracle downgrade, and Consumers Energy's senior secured debt is rated A, A1 and A+.
The verdict
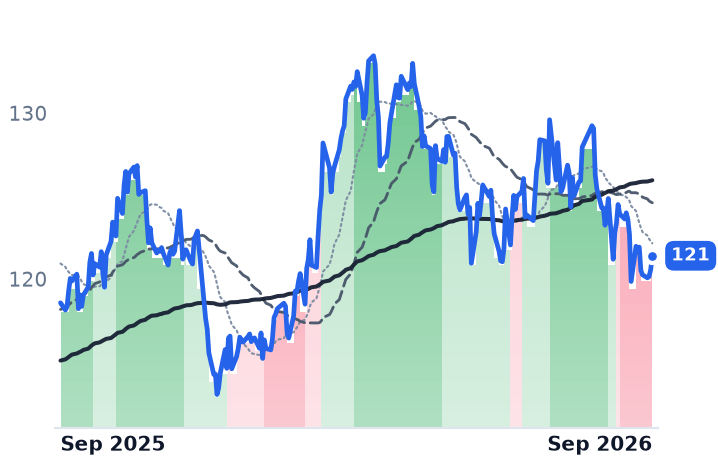
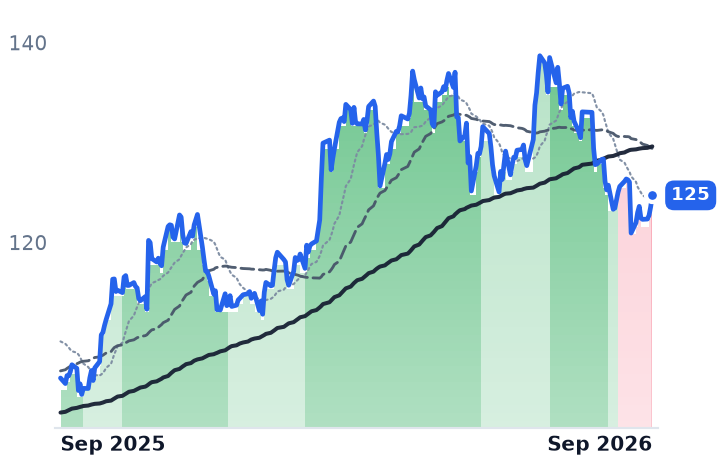
The notes have de-rated for a reason that has nothing to do with these companies: long-end rates and a higher clearing cost for hybrid capital. Nobody will redeem 4.375% money to replace it at 6.200%, so the market is treating them as very long paper and pricing them accordingly. The common shares are the harder case. CMS fell 4.1% over twelve months and DTE rose 1.2%, while Entergy gained 23.6%, NextEra 17.4%, Dominion 13.4% and American Electric Power 13.3%. That underperformance is earned — the earnings actually declined. DTE's trailing price-to-earnings ratio has risen since May, from 20.91x to 21.36x, because profits fell faster than the price; the stock went nowhere and got more expensive on what it has already reported. Both trade near 17.6x forward earnings, below Duke's 17.9x and American Electric Power's 19.5x, but that discount only exists if the consensus 6-8% growth survives the margin compression now visible in two consecutive quarters.
The Google contract's commission decision is expected this month. It is the first dated test of whether Michigan's regulators will let the load growth reach the income statement before the next round of financing prices.