

Leggett & Platt Sold Itself to Its Largest Customer as Bedding Volumes Fell 7%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A screen looking for a quietly rolling-over manufacturer found one that had already ceased to be a manufacturer with its own share price. Leggett & Platt, which builds the innersprings, wire, foam and adjustable bases inside other companies' mattresses, was absorbed by Somnigroup International — the Tempur Sealy and Mattress Firm owner that was already its biggest customer — on August 26, at a fixed 0.1455 Somnigroup shares per Leggett share.
The business underneath was improving as it shrank: June-quarter revenue of $999.7m fell 5.6% year over year while operating income rose 13.3% and gross margin widened to 20.3% from 17.9%. What it could not fix was units. US mattress shipments fell 13.2% in 2025 while market value fell only 6.5% — fewer beds, each carrying less Leggett steel. The answer to that arithmetic was vertical integration, and the price now belongs to Somnigroup, which cut full-year adjusted earnings guidance to $2.85–$3.15 a share.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LEG | Leggett & Platt, Incorporated | Bedding & Components | ⚠️ Emerging Bear | −12.0% | −1.0% |
| Compared against · context, not the story | |||||
SGI | Somnigroup International | Sleep & Wellness | ⚠️ Emerging Bear | −2.7% | −19.7% |
LZB | La-Z-Boy Incorporated | Furniture | 🌱 Emerging Bull | −23.5% | −8.5% |
MHK | Mohawk Industries | Flooring Products | 🔴 Cont. Bear | −5.4% | −1.0% |
WHR | Whirlpool | Kitchen & Home Appliances | 🔴 Cont. Bear | −12.8% | −55.3% |
NUE | Nucor | Integrated Steelmakers | 🟢 Cont. Bull | −3.7% | +83.8% |
STLD | Steel Dynamics | Long Products & Rebar | 🟢 Cont. Bull | −6.6% | +92.9% |
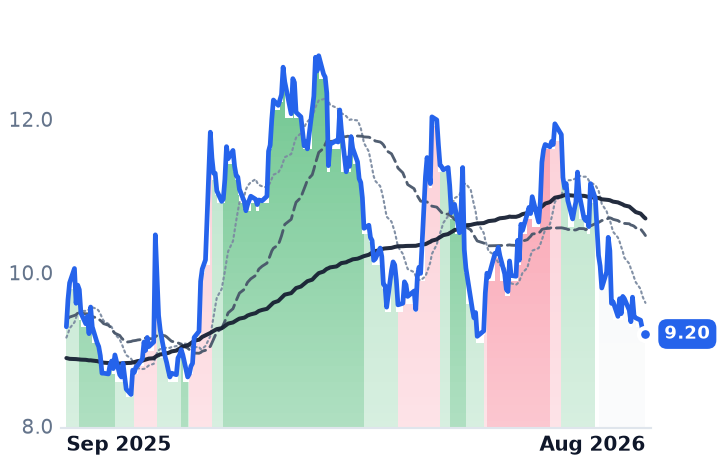
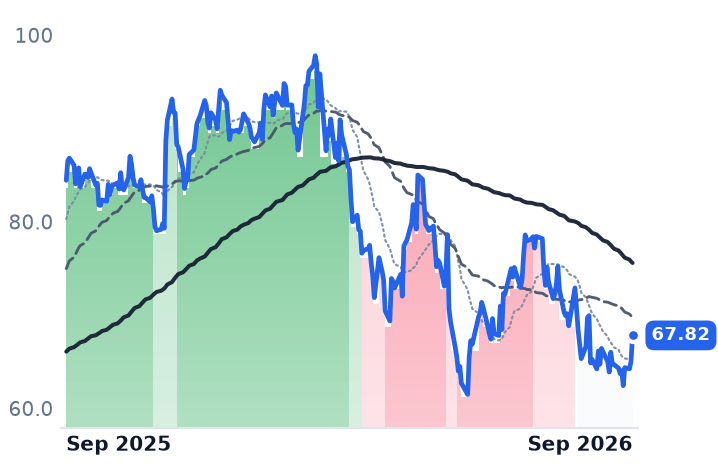
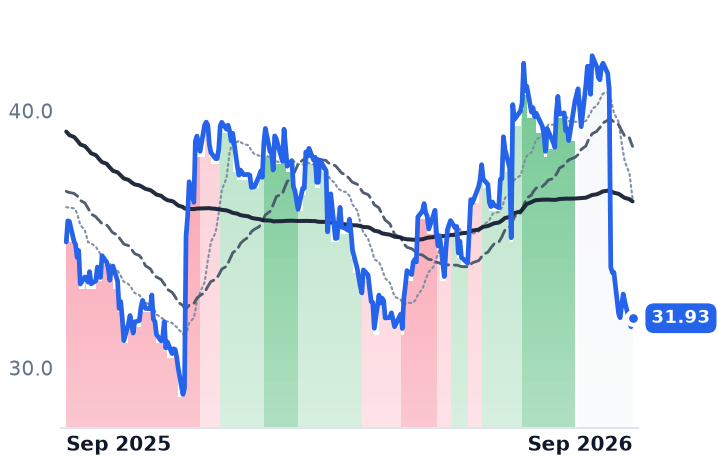
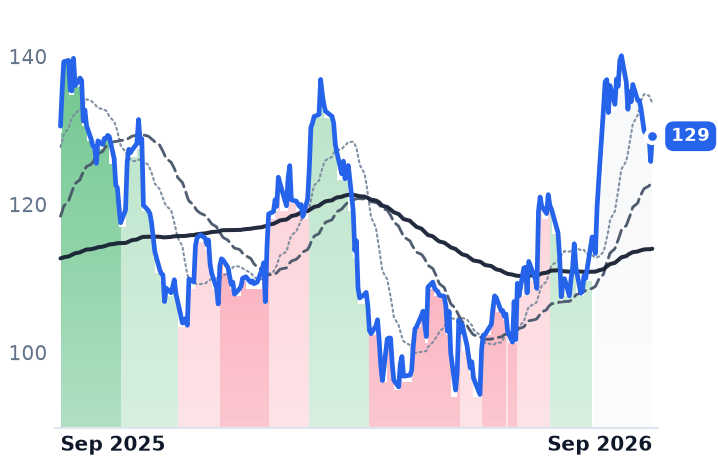
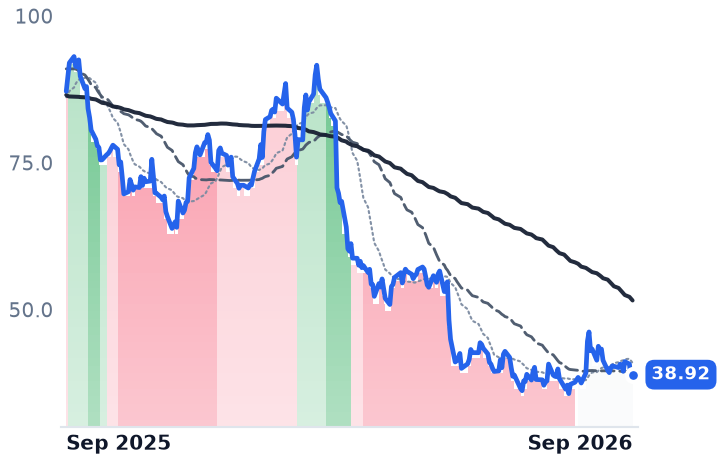
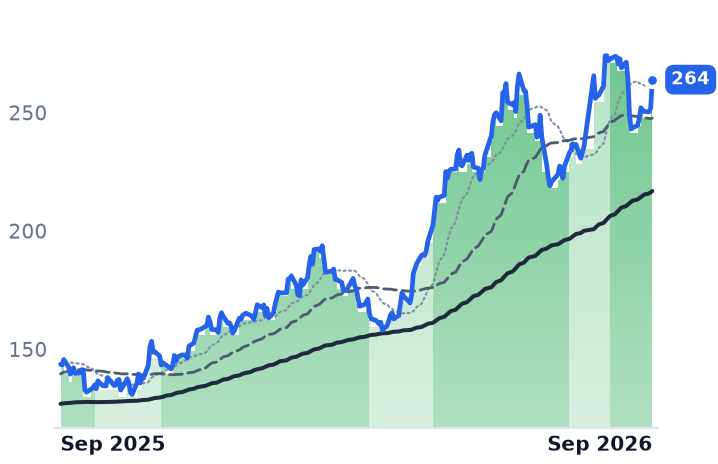
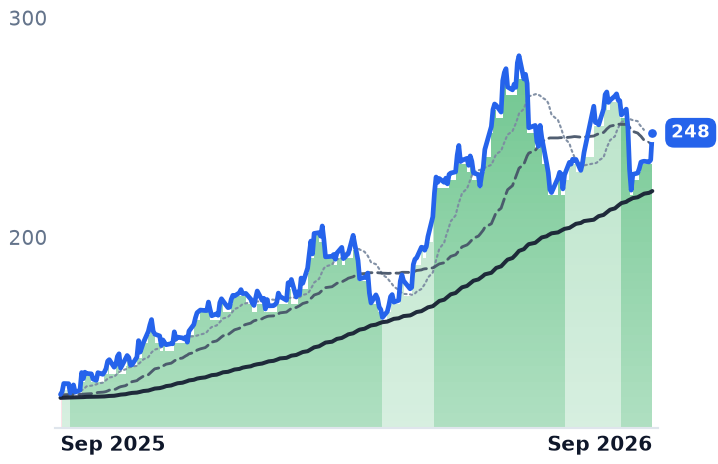
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEG | $1.3B | 5.8x | 9.0x | 0.3x | 0.3x | 1.7x | 1.7x | 5.2x | 12.5% |
SGI | $14.3B | 26.6x | 22.3x | 1.9x | 1.9x | 4.2x | 4.2x | 16.5x | 5.4% |
LZB | $1.4B | 16.8x | 11.6x | 0.7x | 0.7x | 1.5x | 1.5x | 8.6x | 11.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MHK | $5.9B | 14.3x | 11.2x | 0.5x | 0.5x | 2.2x | 2.2x | 4.9x | 12.1% |
WHR | $2.6B | 14.5x | 13.7x | 0.2x | 0.2x | 1.2x | 1.2x | 8.7x | -0.4% |
NUE | $51.7B | 22.3x | 15.9x | 1.5x | 1.4x | 10.8x | 9.7x | 11.5x | 1.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STLD | $33.1B | 24.2x | 15.2x | 1.7x | 1.5x | 12.4x | 10.7x | 15.1x | 2.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LEG | Revenue | −4.9% | +1.9% | +1.7% |
| EPS | −2.3% | +0.0% | +15.3% | |
SGI | Revenue | +1.2% | +3.5% | +4.8% |
| EPS | +12.9% | +19.0% | +25.2% | |
LZB | Revenue | +1.4% | +2.1% | +3.4% |
| EPS | −11.7% | +13.8% | +11.0% | |
MHK | Revenue | +1.7% | +3.1% | +3.9% |
| EPS | −3.9% | +15.2% | +15.8% | |
WHR | Revenue | −4.9% | +3.5% | +5.3% |
| EPS | −56.4% | +72.4% | +32.0% | |
NUE | Revenue | +16.3% | +2.4% | +1.5% |
| EPS | +79.7% | +9.6% | +6.0% | |
STLD | Revenue | +20.4% | +3.2% | +3.0% |
| EPS | +90.0% | +13.5% | +0.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Leggett & Platt sold its last share on August 27. The company, founded in Carthage, Missouri in 1883 and never a seller of finished mattresses — it makes the steel rod, drawn wire, innersprings, specialty foam, foundations and adjustable bases inside somebody else's bed — was absorbed the day before into Somnigroup International, the owner of Tempur Sealy and Mattress Firm and, for nearly half a century, Leggett's own supply counterparty.
That matters beyond the delisting notice. A component supplier is paid on units, and the units are gone: the Mattress Recovery Council's industry group ISPA reports US mattress unit shipments fell 13.2% in 2025 while the market's total value fell only 6.5%, as average selling prices for domestically produced beds rose nearly 5% and buyers who did show up traded up. Stationary foundation shipments — the steel-heavy product Leggett sells — dropped more than a quarter. Fewer beds, less content in each. Leggett's answer, after two years of plant closures, a gutted dividend and divestitures, was to be bought by the customer.
The margin repair was real
June-quarter revenue of $999.7m fell 5.6% year over year, yet gross profit rose 7.4% and operating income rose 13.3% to $80.3m. Gross margin reached 20.3% against 17.9% a year earlier. That is genuine self-help, and it is one quarter old: in the March quarter operating income fell 29% and margin was 5.0%. Revenue has declined every year since 2021 and is down about 20% from that peak.
Bedding Products trade sales were roughly flat at $386.9m on volume down 7% — retailer merchandising changes, lower volume with an adjustable-bed customer, soft US and European demand, and a decision to walk away from a financially challenged US spring customer — partly offset by higher trade rod and wire sales. Steel is both the input and, at these prices, part of the offset: US hot-rolled coil reached $1,002 a ton in March against $694 at the start of 2025 after Section 232 tariffs doubled to 50%. Net debt stood at 2.6 times trailing adjusted earnings before interest, taxes, depreciation and amortization, the quarterly dividend was held at $0.05, and full-year guidance had been withdrawn on account of the merger. The company held no earnings call.
The price was arithmetic
With the exchange ratio fixed at 0.1455 Somnigroup shares, Leggett's quote was its acquirer's, multiplied. On August 27 it closed at $9.20 against a conversion value of $9.08. On August 6, when Somnigroup cut guidance and fell 7.2%, Leggett fell 6.7% the same session on no news of its own. The 30-day slide that looked like a demand rollover was one company's earnings call transmitted through a ratio; La-Z-Boy fell 18.6% over the same stretch and Mohawk Industries rose 13.7%, so nothing segment-wide was happening. The deal was worth about $2.5bn at April's announcement and about $2.3bn at completion, the difference being Somnigroup's own share price.
"By bringing a successful supply partner into our group, we accelerate our ability to deliver differentiated, consumer-centric innovation," Somnigroup chief executive Scott Thompson said when the deal was struck. On the August 6 call he was blunter about the demand: "There's no question there's a K. Entry-level bedding has been the hardest hit by far, and luxury bedding, we'll call it, has been very resilient and at times strong."
What the buyer now owns
Somnigroup is running the same pattern at four times the scale — June-quarter revenue down 3.0% to $1.82bn, operating income up 12.1% — and its North American Tempur-Sealy gross margin jumped to 61.8% on Mattress Firm integration synergies. But it guided full-year adjusted earnings to $2.85–$3.15 a share on an assumption that the global bedding industry is down mid-single digits, upgraded from low-single digits, and the shares are down 27% year to date. They have de-rated from about 26.6 times trailing earnings to 22.3 times forward; on consensus 2027 earnings of $3.62 the same price is 18.7 times. Combined leverage was roughly 2.8 times adjusted EBITDA at close, with run-rate synergies raised to $75m.
The verdict splits cleanly. Leggett's restructuring earned its margin expansion, and none of it solved the unit problem — analysts model 2027 revenue growth of 1.9% and flat earnings for the standalone business, which is to say the base it was cutting toward never stopped shrinking. Vertical integration is the industry's answer: capture the component margin inside a branded retailer rather than sell it into a market that buys 13% fewer beds. Whether that works is now a question about one share price, because owning the innerspring business means owning the mattress retailer.
The listed component supplier no longer exists. What is left is a bet that the world's largest bedding company can earn more per bed at a time when the industry keeps selling fewer of them.