

Tapestry Guided Growth Down by More Than Half; Capri Cut Revenue, Not Earnings
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Coach is compounding and its owner's shares just had their worst session in years. Tapestry closed fiscal 2026 with revenue of $8.0bn, up 14%, handbag average unit retail rising in the mid-teens at Coach and roughly 11 million new customers added across the year — then guided fiscal 2027 to mid-single-digit growth, a rate less than half what it had just delivered, with a mid-20% tariff on US inventory receipts holding gross-margin expansion to about 30 basis points.
The guide, not the quarter, is what the market repriced: Tapestry now trades at 15.3x forward earnings against Ralph Lauren's 18.0x on a comparable mid-single-digit outlook. Capri, one-seventeenth its size, is the genuinely broken business — revenue down for a fourth straight year, Michael Kors off 7.1%, and an unchanged $2.15 earnings guide financed by $70m of expense cuts. The two are not one story.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
TPR | Tapestry | Handbags & Accessories | 🟢 Cont. Bull | −21.7% | +19.8% |
CPRI | Capri | Handbags & Accessories | ⚠️ Emerging Bear | −21.3% | −37.4% |
| Compared against · context, not the story | |||||
RL | Ralph Lauren | Premium Lifestyle | 🟢 Cont. Bull | −10.8% | +10.0% |
PVH | PVH | Premium Lifestyle | 🟢 Cont. Bull | −18.7% | −15.9% |
LEVI | Levi Strauss | Denim & Casual | 🟢 Cont. Bull | −16.8% | −7.7% |
DECK | Deckers Outdoor | Premium Lifestyle Footwear | 🌱 Emerging Bull | −14.9% | −31.1% |
VFC | V.F | Outdoor & Adventure | ⚠️ Emerging Bear | −12.3% | −10.4% |
NKE | NIKE | Athletic & Performance | 🔴 Cont. Bear | −10.6% | −48.0% |
ONON | On | Athletic & Activewear | 🔴 Cont. Bear | −26.2% | −37.5% |
BIRK | Birkenstock | Premium Lifestyle Footwear | 🌱 Emerging Bull | −11.5% | −31.8% |
KTB | Kontoor Brands | Denim & Casual | 🟢 Cont. Bull | −11.4% | −3.5% |
CRI | Carter's | Childrenswear | 🟢 Cont. Bull | −20.3% | +11.3% |
AEO | American Eagle Outfitters | Specialty Apparel | ⚠️ Emerging Bear | −7.3% | +25.0% |
LULU | Lululemon Athletica | Athletic & Activewear | 🔴 Cont. Bear | −2.8% | −39.9% |
ULTA | Ulta Beauty | Beauty & Personal Care | ⚠️ Emerging Bear | +2.2% | +2.6% |
EL | The Estée Lauder Companies | Beauty & Personal Care | ⚠️ Emerging Bear | +17.8% | +10.6% |
ANF | Abercrombie & Fitch | Specialty Apparel | 🟢 Cont. Bull | +27.9% | +51.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TPR | $24.7B | 16.3x | 15.3x | 3.1x | 2.9x | 4.0x | 3.7x | 13.0x | 7.3% |
CPRI | $1.5B | 10.2x | 6.0x | 0.4x | 0.4x | 0.7x | 0.7x | 11.5x | 5.7% |
RL | $20.8B | 21.2x | 18.0x | 2.5x | 2.4x | 3.5x | 3.4x | 14.9x | 5.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PVH | $3.6B | 148.5x | 6.6x | 0.4x | 0.4x | 0.7x | 0.7x | 11.0x | 14.8% |
LEVI | $8.3B | 13.2x | 14.0x | 1.3x | 1.2x | 2.1x | 2.0x | 10.1x | 5.9% |
DECK | $13.3B | 13.2x | 12.7x | 2.5x | 2.3x | 4.3x | 4.0x | 8.4x | 7.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VFC | $6.5B | 29.2x | 16.2x | 0.7x | 0.7x | 1.3x | 1.3x | 10.8x | -10.2% |
NKE | $61.9B | 27.5x | 28.1x | 1.3x | 1.3x | 3.3x | 3.3x | 19.9x | 1.7% |
ONON | $12.4B | 38.5x | 26.1x | 3.1x | 3.4x | 4.9x | 5.3x | 22.1x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BIRK | $5.7B | 13.8x | 15.4x | 2.3x | 2.4x | 4.0x | 4.3x | 9.1x | 6.5% |
KTB | $3.4B | 12.3x | 11.5x | 1.1x | 1.2x | 2.3x | 2.5x | 10.1x | 11.7% |
CRI | $1.2B | 13.1x | 10.4x | 0.4x | 0.4x | 0.9x | 0.9x | 7.0x | 10.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AEO | $2.5B | 13.5x | 8.7x | 0.5x | 0.4x | 1.4x | 1.3x | 7.4x | 1.0% |
LULU | $14.0B | 9.0x | 9.7x | 1.3x | 1.2x | 2.2x | 2.2x | 5.1x | 6.6% |
ULTA | $21.6B | 19.2x | 17.3x | 1.7x | 1.6x | 4.5x | 4.2x | 12.7x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EL | $29.0B | n/m | 33.1x | 2.0x | 1.9x | 2.7x | 2.6x | 21.9x | 4.4% |
ANF | $3.2B | 6.4x | 6.6x | 0.6x | 0.6x | 1.0x | 1.0x | 4.1x | 11.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TPR | Revenue | +14.7% | +7.1% | +5.4% |
| EPS | +37.4% | +14.1% | +11.7% | |
CPRI | Revenue | −20.8% | −2.2% | +2.5% |
| EPS | +38.9% | +51.2% | +18.4% | |
RL | Revenue | +13.6% | +8.8% | +5.3% |
| EPS | +35.1% | +15.9% | +11.0% | |
PVH | Revenue | +3.0% | +1.6% | +1.8% |
| EPS | −6.6% | +10.9% | +12.1% | |
LEVI | Revenue | +7.5% | +4.9% | +6.0% |
| EPS | +13.0% | +12.0% | +15.6% | |
DECK | Revenue | +9.4% | +7.0% | +6.8% |
| EPS | +16.0% | +6.6% | +10.4% | |
VFC | Revenue | −2.4% | +2.4% | +3.0% |
| EPS | +12.1% | +24.5% | +23.2% | |
NKE | Revenue | +0.7% | +0.6% | +4.4% |
| EPS | −30.5% | +22.1% | +28.6% | |
ONON | Revenue | +21.3% | +20.3% | +23.9% |
| EPS | +101.7% | +23.3% | +26.4% | |
BIRK | Revenue | +12.8% | +14.1% | +14.1% |
| EPS | +17.8% | +21.0% | +17.5% | |
KTB | Revenue | +19.4% | −9.7% | +4.2% |
| EPS | +13.2% | −2.7% | +21.4% | |
CRI | Revenue | +2.6% | +4.4% | +1.3% |
| EPS | −37.8% | −2.7% | +12.1% | |
AEO | Revenue | +2.8% | +5.6% | +3.4% |
| EPS | −19.0% | +28.1% | +12.0% | |
LULU | Revenue | +4.7% | +3.9% | +4.5% |
| EPS | −9.1% | −5.7% | +7.7% | |
ULTA | Revenue | +9.4% | +7.3% | +5.6% |
| EPS | +7.0% | +11.4% | +10.9% | |
EL | Revenue | +4.5% | +4.1% | +4.4% |
| EPS | +63.1% | +30.8% | +21.9% | |
ANF | Revenue | +6.8% | +3.9% | +3.8% |
| EPS | −7.7% | +8.9% | +9.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
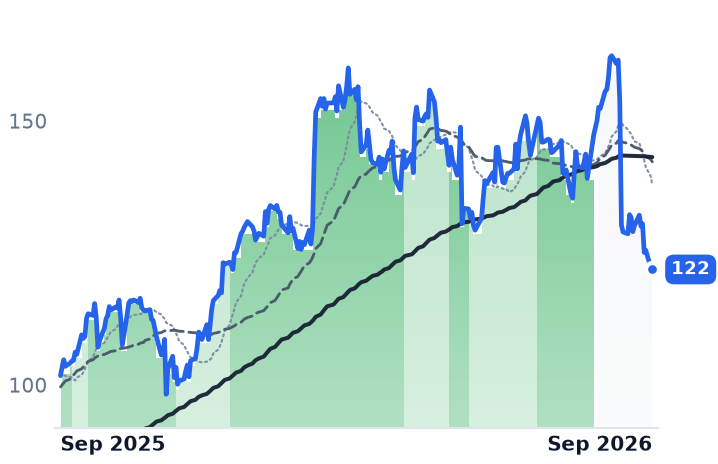
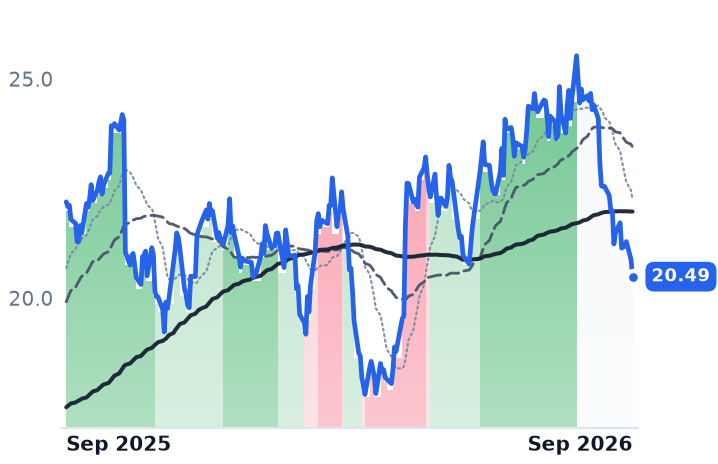
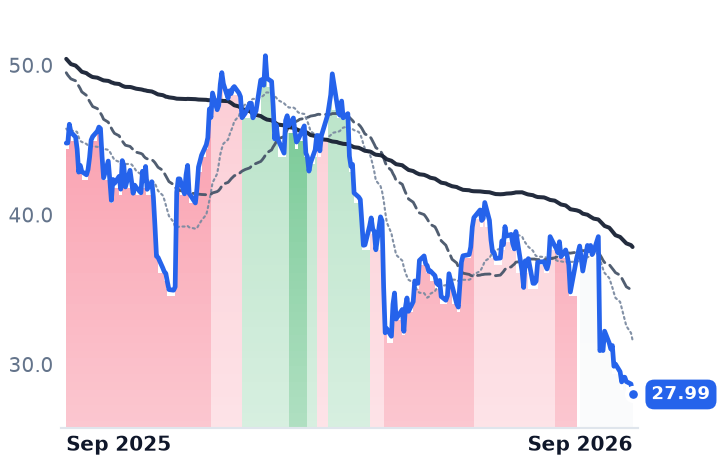
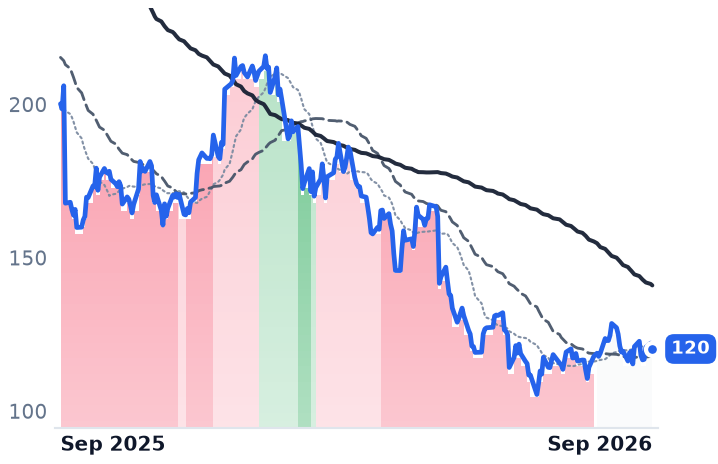
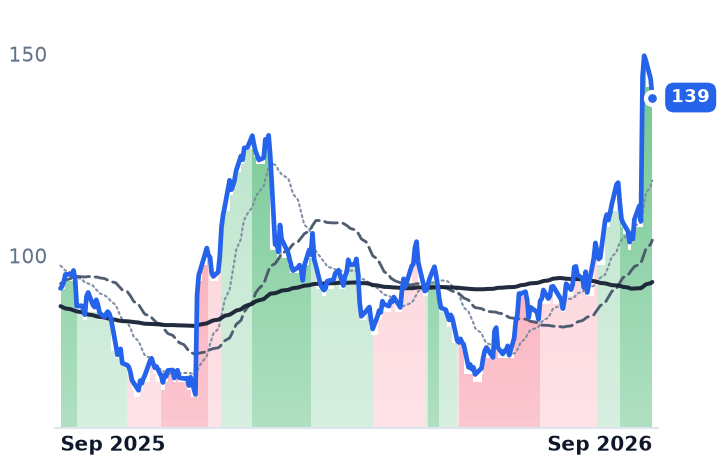
Tapestry told investors on August 13 that its Coach brand had grown 14% in constant currency in the fiscal fourth quarter, driven by mid-teens growth in handbag average unit retail, and that the year ahead would bring mid-single-digit revenue growth. The shares fell 15.2% in that session, from $153.66 to $130.29 — one day that accounts for most of a 21.7% decline over the past month.
What the market marked down was the growth rate, not the brand. Fiscal 2026 revenue reached $8.0bn, up 14%; the fiscal 2027 guide of $8.4bn to $8.5bn implies about 5.6%. The mechanism sits in the company's own outlook: the guide embeds a mid-20% tariff rate on US inventory receipts, net-neutral for the year but back-half weighted, which caps gross-margin expansion at roughly 30 basis points against the 180 points Tapestry delivered in the quarter it had just reported. Leather is the other squeeze: analysts expect prices for leather footwear and accessories to rise about 22% over the next year or two as tariffs, freight and scarce premium hides pass through.
Coach's meter is still running
Coach revenue was $1.64bn in the quarter, and Tapestry welcomed more than 2.5 million new consumers, roughly 11.0 million across the year, about 35% of them Gen Z. Coach has overtaken Michael Kors as the second-largest luxury handbag brand in the United States and ranks first in brand preference among 18-to-27-year-olds. Quarterly reported revenue growth did decelerate — from 21.2% year on year in the third quarter to 8.9% in the fourth — but operating margin in the fourth quarter was 23.6% and net margin 18.5%.
The fault line inside Tapestry is the second brand. Kate Spade revenue of $235m fell 7% in constant currency. Chief executive Joanne Crevoiserat conceded on August 13 that Kate Spade's "top-line progress was more gradual than we planned", even as she called the quarter one that "capped a year of strong growth."
Capri is a different business, not a peer
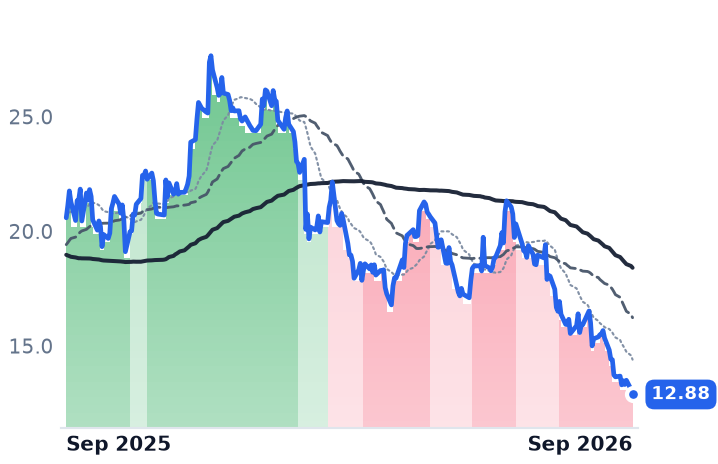
Capri Holdings, which owns Michael Kors and Jimmy Choo after selling Versace, carries a market value of $1.47bn against Tapestry's $24.68bn. Its June-quarter revenue fell 3.5% to $769m, Michael Kors down 7.1% and Jimmy Choo up 10.5%, and the fiscal 2027 revenue outlook came down to about $3.4bn — some $135m of cuts split between delayed inventory receipts, softer European trade and currency. The earnings guide held. "Based on our revised revenue expectations, we are taking actions to reduce operating expenses, which are enabling us to maintain our fiscal '27 earnings per share outlook of approximately $2.15," chairman and chief executive John Idol said on the August 5 call — a 40% increase financed by $70m of spending cuts rather than by demand. Gross margin did expand 200 basis points to 65.0%, inventory is down 20% year on year, and net debt has fallen to $224m from about $1.5bn. TD Cowen still cut the stock to Hold with a $17 target, citing second-quarter guidance implying an 11% Michael Kors decline.
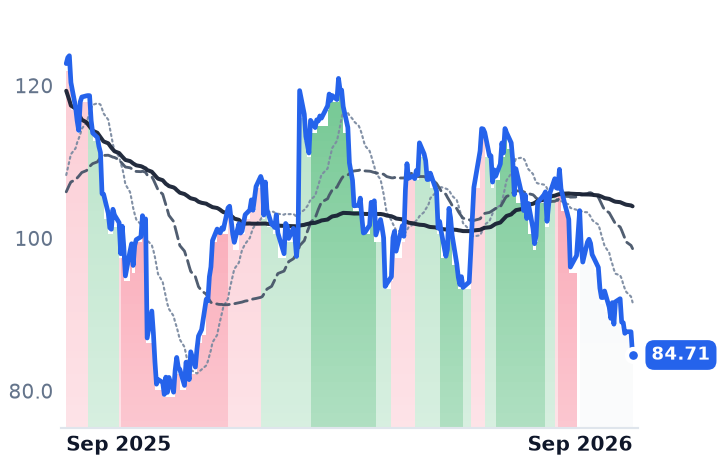
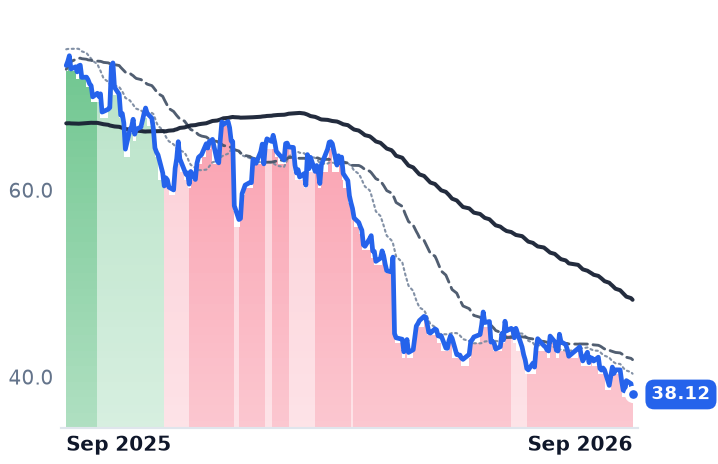
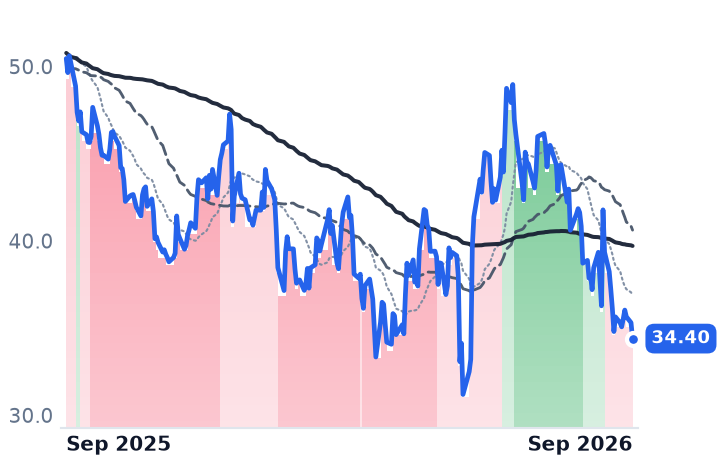
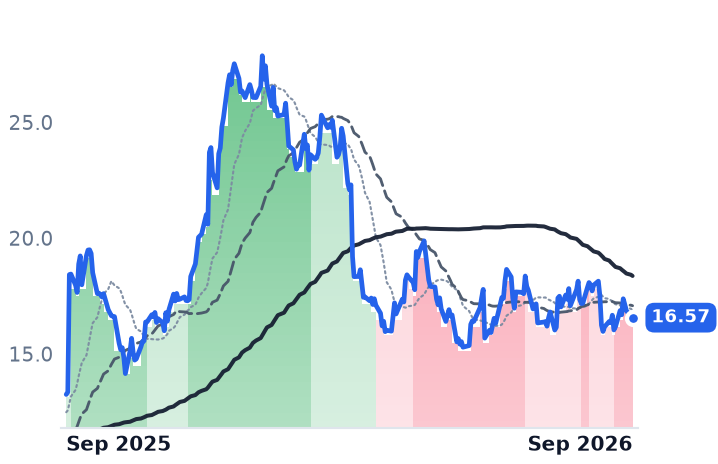
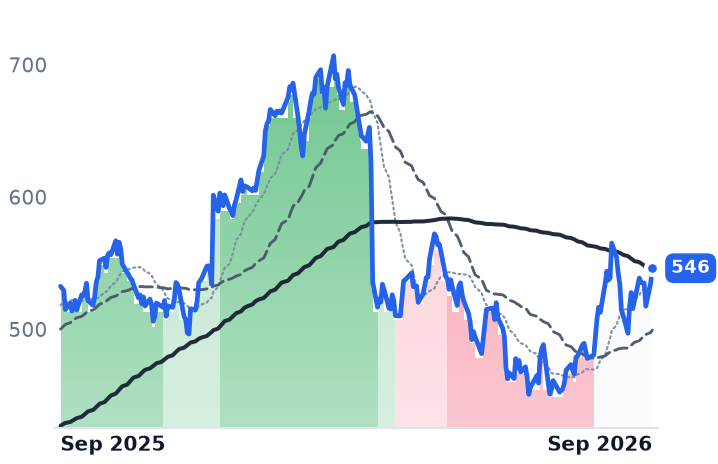
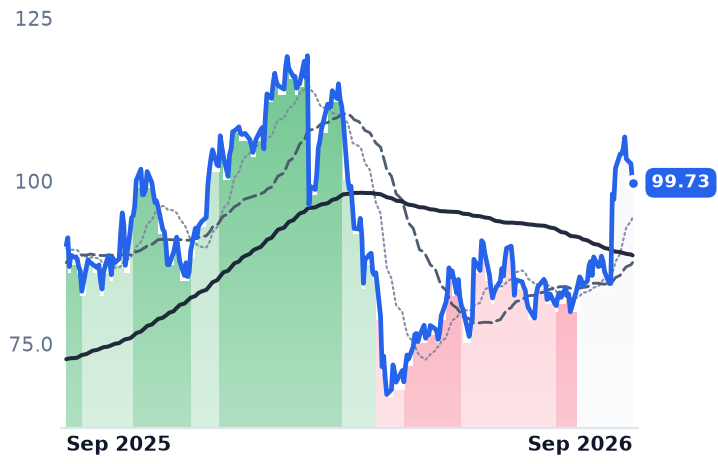
The price paths say the same thing. Over twelve months Tapestry is up 18.6% and Capri down 37.4%; Capri's shares have fallen 33.5% since late June, with its moving averages turning negative in mid-July, three weeks before it reported. Tapestry's fall is one gap and a drift; Capri's is a slide that began before the news.
What the businesses earn and what they don't
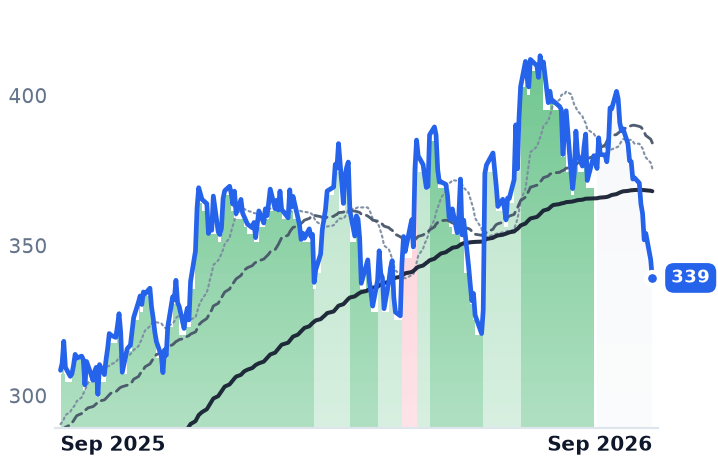
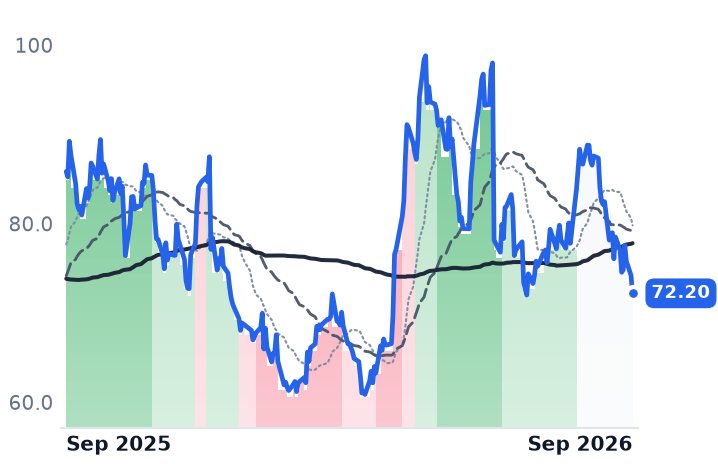
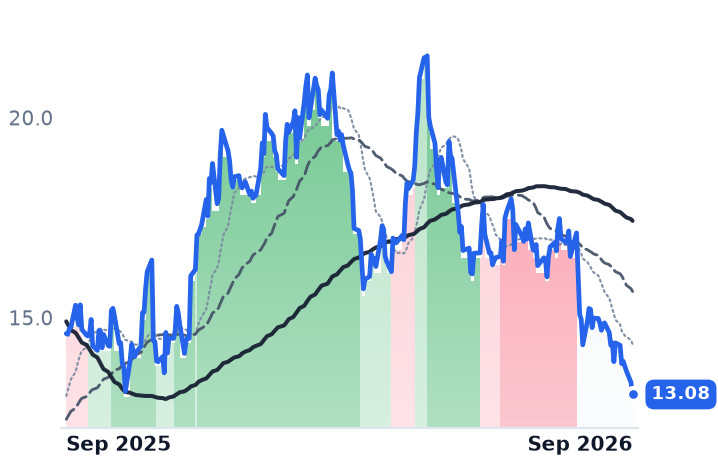
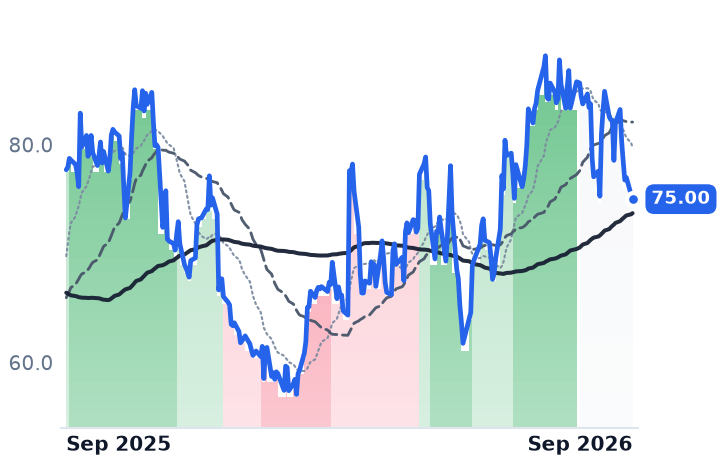
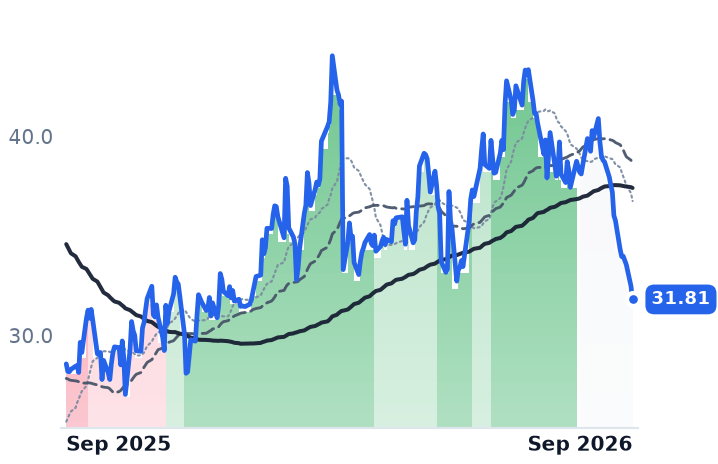
Tapestry's de-rating is partly deserved: the growth rate being capitalised genuinely halved, and the forward multiple fell from about 20.6x in early August to 15.3x on consensus earnings of $7.98. But consensus still sits above the company's own $7.80-to-$7.90 guide, so the cut to expectations is a couple of percent against a share-price fall of more than a fifth. Ralph Lauren, guiding to 5-6% constant-currency growth on the same average-unit-retail playbook, trades at 18.0x forward. The rest of Tapestry's move belongs to the group: over the same month PVH fell 18.7%, Levi Strauss 16.8% and Ralph Lauren 10.8%, against US retail sales down 0.6% in July and sentiment sliding to a preliminary 51. Capri's 0.43x forward sales, versus Tapestry's 2.88x, is not a dislocation on the same evidence — consensus sees revenue up 2.5% in fiscal 2028 on a base that has shrunk from $5.62bn in fiscal 2023.
Europe offers the awkward counterpoint: LVMH's fashion and leather goods division returned to growth in the June quarter, ending seven quarters of decline, and Kering turned positive for the first time in three years — the leather-goods cycle turning up while the American accessible-luxury names were sold. Tapestry plans to return about $1.7bn to holders again this year, near 7% of its market value, buying shares from a customer file that added eleven million names. Whether that is a franchise on sale or a growth rate correctly re-rated will be settled in November, when the first quarter tests a guide the company set in the worst week of the year to set one.