

Liberty Energy Committed to 3 Gigawatts of Turbines and Turned Free Cash Flow Negative
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
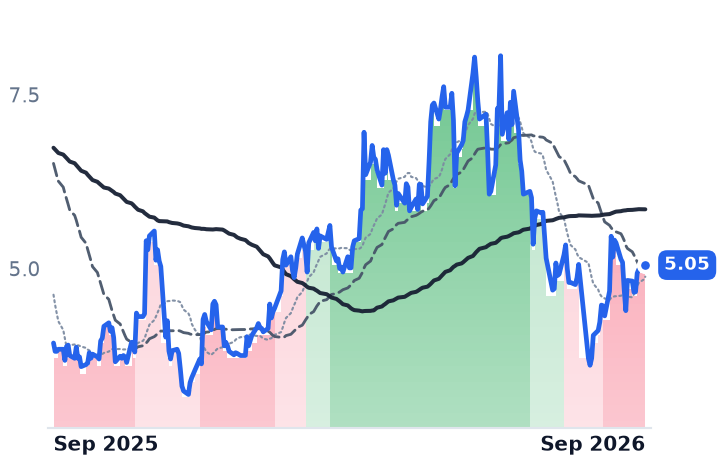
Two of the five North American frac contractors have poured capital into gas-fired power for data centers, and both have lost roughly a third of their value since late April, while the three peers without a power venture held or gained. Liberty Energy's pumping business improved — second-quarter revenue rose 14% and gross margin went from 9.7% to 17.5% — yet operating income fell 70%, trailing free cash flow is negative, and this year's capital budget runs to about 2.5 times the EBITDA analysts expect, against no signed customer lease at its Texas campus. ProPetro is the counter-case: 350 megawatts under contract and a live hyperscaler site already earning, but it still trades above Liberty and Patterson-UTI on earnings with revenue falling. The twelve-month re-rating in this group belongs to completions pricing rather than to power.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LBRT | Liberty Energy | Well Services & Stimulation | ⚠️ Emerging Bear | +5.9% | +84.9% |
PUMP | ProPetro | Well Services & Stimulation | ⚠️ Emerging Bear | +1.7% | +126.5% |
| Compared against · context, not the story | |||||
PTEN | Patterson-UTI Energy | Onshore Land Drilling | 🟢 Cont. Bull | +24.1% | +127.9% |
RES | RPC | Well Services & Stimulation | ⚠️ Emerging Bear | +13.4% | +38.7% |
ACDC | ProFrac | Well Services & Stimulation | 🔴 Cont. Bear | +22.9% | +28.5% |
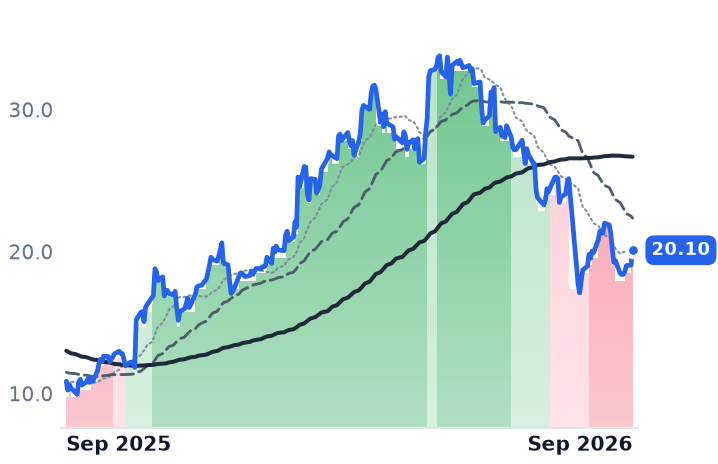
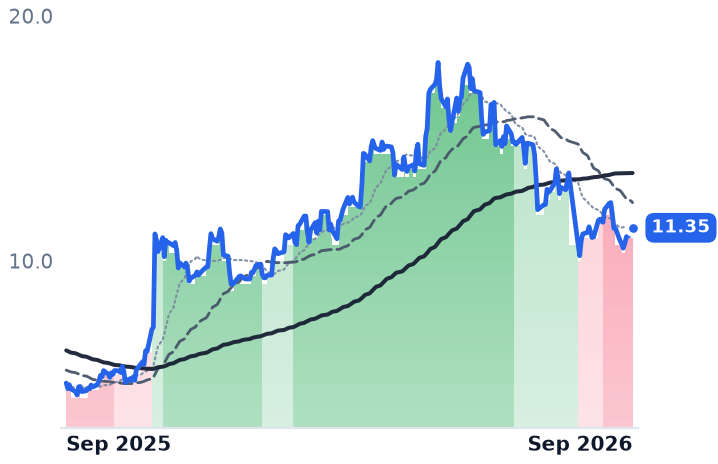
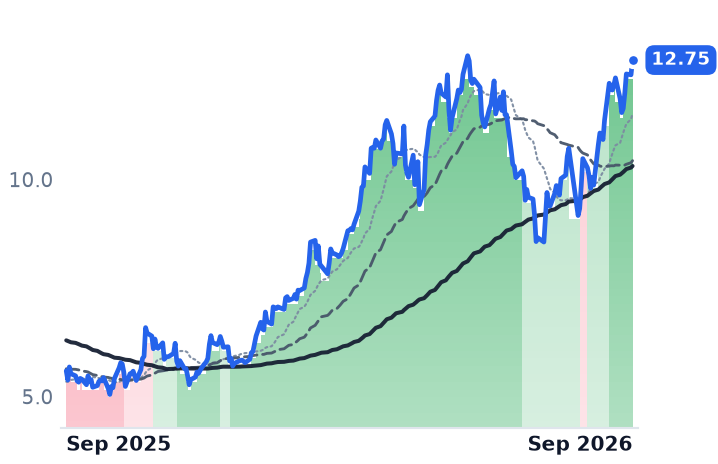
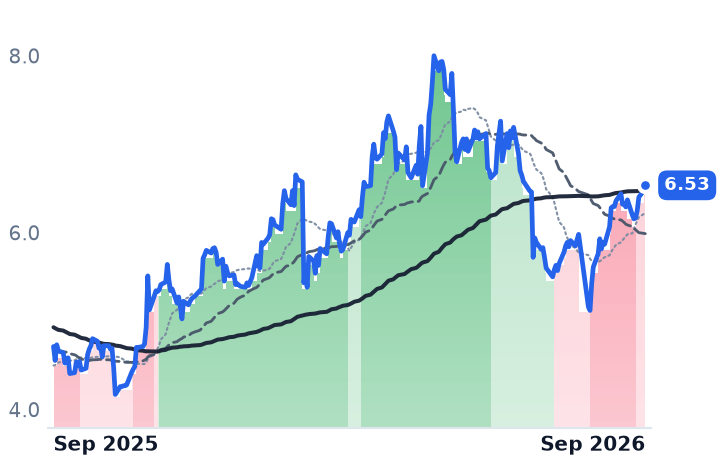
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LBRT | $3.3B | 26.6x | 72.8x | 0.8x | 0.7x | 6.1x | 5.6x | 7.0x | -9.7% |
PUMP | $1.4B | n/m | — | 1.2x | 1.1x | 14.5x | 13.6x | 8.8x | -1.6% |
PTEN | $4.9B | n/m | — | 1.0x | 1.0x | 7.3x | 7.0x | 7.0x | 3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RES | $1.5B | 65.8x | 26.8x | 0.8x | 0.8x | 8.6x | 8.4x | 6.1x | 2.7% |
ACDC | $902.8M | n/m | — | 0.5x | 0.5x | 11.1x | 9.9x | 15.8x | -6.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LBRT | Revenue | +19.1% | +8.7% | +15.3% |
| EPS | −534.1% | −39.9% | +311.7% | |
PUMP | Revenue | −2.1% | +17.8% | +11.4% |
| EPS | −79.2% | −3223.9% | +224.7% | |
PTEN | Revenue | +2.6% | +7.3% | +1.1% |
| EPS | −93.3% | −1578.9% | +78.0% | |
RES | Revenue | +12.5% | +2.1% | +2.7% |
| EPS | −15.0% | +4.1% | +35.2% | |
ACDC | Revenue | +4.6% | +10.8% | −4.3% |
| EPS | −22.0% | −44.0% | −78.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Liberty Energy, the second-largest North American hydraulic fracturing contractor and owner of two Permian sand mines, raised its 2026 capital budget in July to roughly $1.5bn from about $1.2bn. Nearly all of the increase is deposits on gas engines and turbines bound for data centers; $71m of such deposits went out in the second quarter alone. Management told investors the machines will have minimal effect on the profit-and-loss statement until 2028.
The spending sets up a clean test inside a five-company group. Liberty and ProPetro, the Midland pressure pumper whose PROPWR arm sells behind-the-meter electricity, are the two members with named power ventures, and both are down roughly a third from late-April highs. Patterson-UTI, RPC and ProFrac, which have none, rose 9.6%, fell 2.2% and fell 22.2% respectively over the same three months. Liberty's 2026 capex is about two and a half times the $602m of EBITDA consensus expects it to earn this year.
Why pumpers are selling electricity
The constraint on American data-center construction is generating equipment. GE Vernova's gas turbine backlog reached 116 gigawatts in the second quarter from 100 a quarter earlier, and it is now taking reservations for 2031 deliveries. US data-center load is projected to climb from 31 gigawatts in 2025 to 66 in 2027. Frac companies already buy reciprocating engines by the hundred, condition wellhead gas and run field crews around the clock, so they can sell speed into that queue.
Liberty has secured 3 gigawatts of supply through 2029 from Bergen Engines and Wärtsilä, at an estimated $5-6bn of eventual capex, targeting 17-18% unlevered returns and funding through special-purpose vehicles carrying non-recourse debt. It ended the quarter with $559m of cash against $736m of net debt. What it does not yet have is a customer. Its most contract-like commitment is a January partnership with Vantage Data Centers anchored by a reservation of 400 megawatts of 2027 capacity; the 2-gigawatt Alpha Digital campus in Reeves County, a joint venture with PowerBridge announced on 22 July, has no leases signed. Chief executive Ron Gusek said the company had "gained strong commercial traction, capitalizing on the revolutionary transformation of power supply and delivery." Barclays' Eddie Kim wrote that "the company has no energy service agreement or firm contract, which is what investors had been hoping for", cutting his target to $23 from $32.
The pumping business underneath is getting better, not worse. Second-quarter revenue of $1.189bn was up 14% year on year, gross margin widened from 9.7% to 17.5%, and adjusted EBITDA was $151m. But operating income fell 70% to $12.7m, and trailing free cash flow is negative, running at about -9.7% of market value.
The one power arm that earns
ProPetro's version is further along. PROPWR's contracted capacity rose to 350 megawatts from 240 during the quarter, its 60-megawatt behind-the-meter site for a Midwest hyperscaler is live, and the segment generated positive EBITDA in the final two months of the quarter. A Caterpillar framework gives access to about 2.1 gigawatts more. It pre-funded the buildout with a $690m zero-coupon convertible in May and ended the quarter with $784m of cash, budgeting $400-450m for power against $125-145m for completions.
The pumping side is the weak half: revenue of $305.8m fell 6.2% and the company lost $8.1m, though it activated a twelfth frac fleet and is deploying a thirteenth. Chief executive Sam Sledge said results "once again demonstrate the strength of our business model." At 8.75x trailing EV/EBITDA, ProPetro is priced above Liberty at 7.04x, Patterson-UTI at 7.03x and RPC at 6.07x — with consensus placing the payoff in 2028, when EBITDA is modeled at $383m.
What the year actually paid for
Patterson-UTI has no data-center venture and is up 119.4% over twelve months, essentially matching ProPetro's 122.5%. Its gross margin went from 2.3% to 22.9% on drilling day rates up 10-15% sequentially, and management says completions pricing is down about 30% over three years with a large part of that recoverable. RPC's Ben Palmer was blunter about volumes: "We currently have no plans to reactivate fleets at current levels." Active crew counts have been choppy rather than collapsing, 165 in late April and 205 in early July. The twelve-month re-rating was pricing recovery in drilling and completions, not payment for power.
The three-month drawdown is the market applying oilfield capital discipline to generation capex. Patterson-UTI and RPC convert into positive free cash flow; Liberty and ProPetro do not. Liberty's margin repair is real and unrewarded, and its shares now carry no visible premium for 3 gigawatts of secured turbine slots — but cheapness measured on EBITDA is not cheapness measured on cash, and the discount is the price of a deposit that has not become a contract.
Liberty's own timetable puts first power at Alpha Digital in late 2027 and full run-rate at the end of 2029. Three more annual budgets have to be defended before the first one pays.