

Cold Storage Is 10% Oversupplied: Americold's Storage Rate Rose and Lineage's Fell 0.7%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The two public cold-storage operators both reported occupancy gains in the June quarter and got opposite results underneath them. Americold's revenue grew 1.9% year over year after four straight years of annual decline, its storage rate per pallet turned positive, and it raised full-year adjusted funds from operations guidance to $1.26–$1.32 a share.
Lineage's same-store net operating income fell 2.9%, and the share of rent-and-storage revenue carrying minimum guarantees slid to 44.5% — the fixed-commitment conversion meant to underwrite the sector is running backwards at the larger operator.
The explanation is supply, not appetite for frozen food: US cold-storage capacity grew 14.5% between 2021 and 2025 against roughly a third as much demand growth. Neither company is riding a volume recovery. One is taking share; the other is losing price.
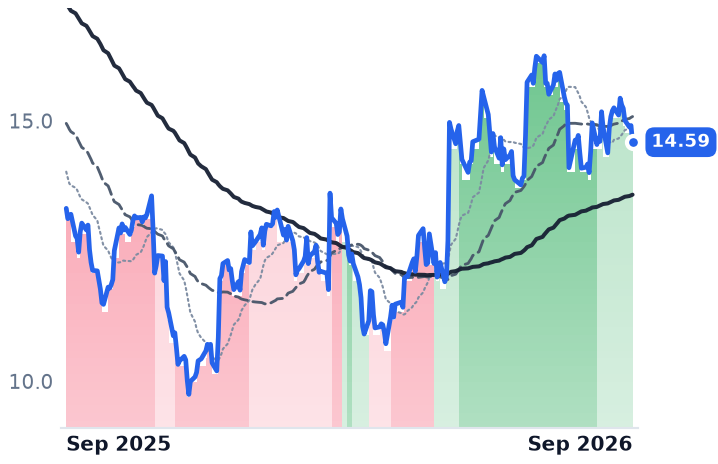
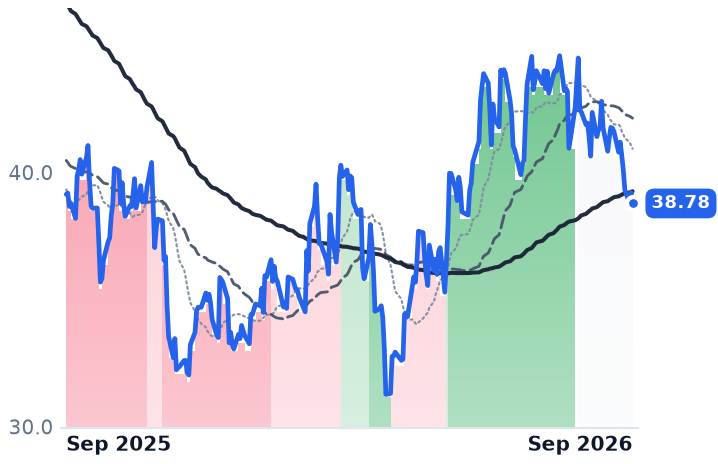
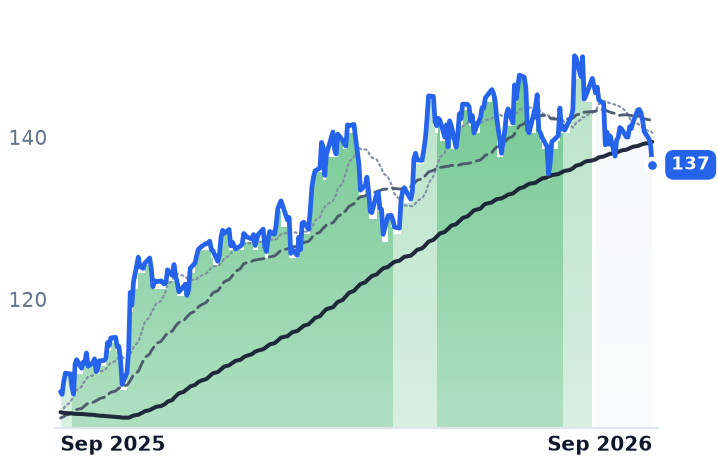
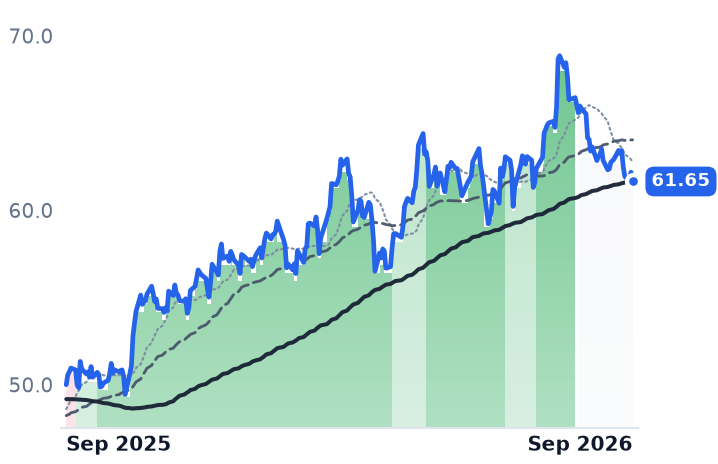
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
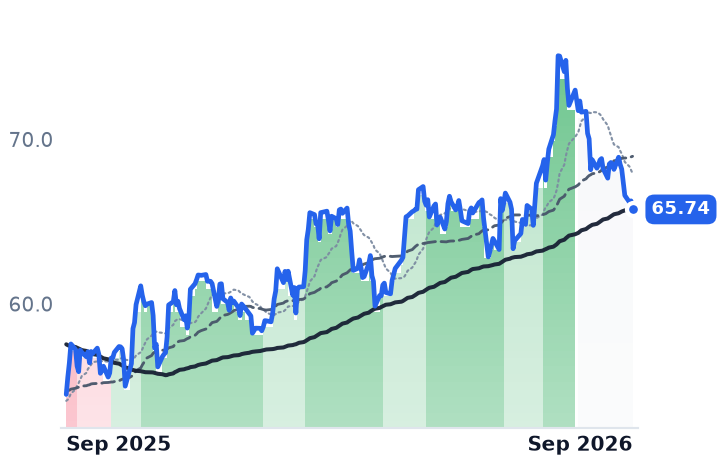
COLD | Americold Realty Trust | Temperature-Controlled Warehousing | 🌱 Emerging Bull | +3.4% | +9.5% |
LINE | Lineage | Temperature-Controlled Warehousing | 🌱 Emerging Bull | −7.4% | −0.9% |
| Compared against · context, not the story | |||||
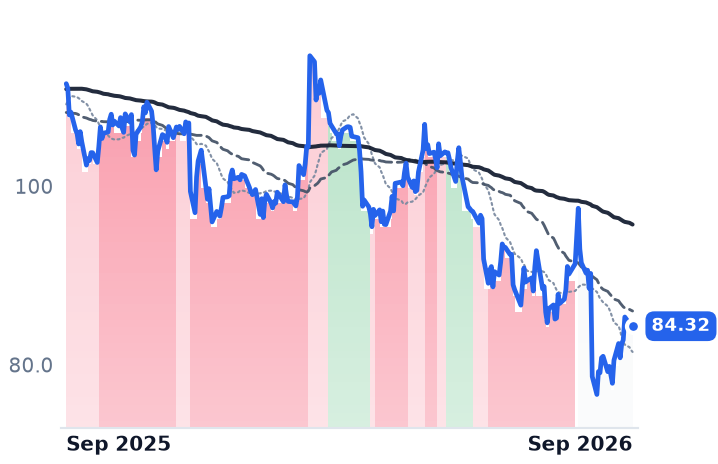
PLD | Prologis | Logistics & Distribution | 🟢 Cont. Bull | −5.2% | +25.8% |
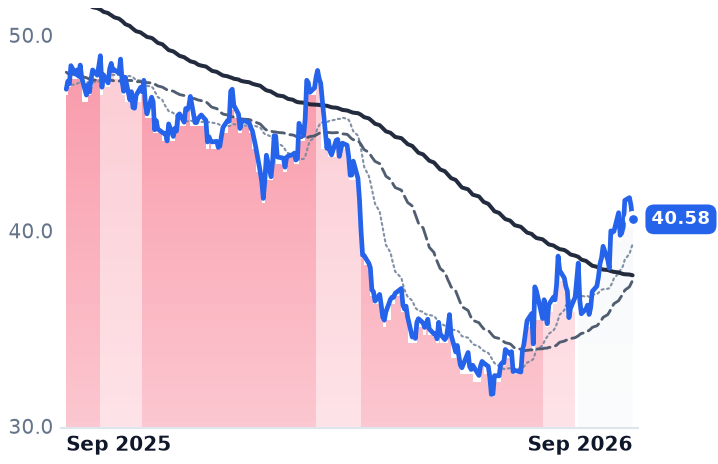
FR | First Industrial Realty Trust | Logistics & Distribution | 🟢 Cont. Bull | −5.9% | +23.3% |
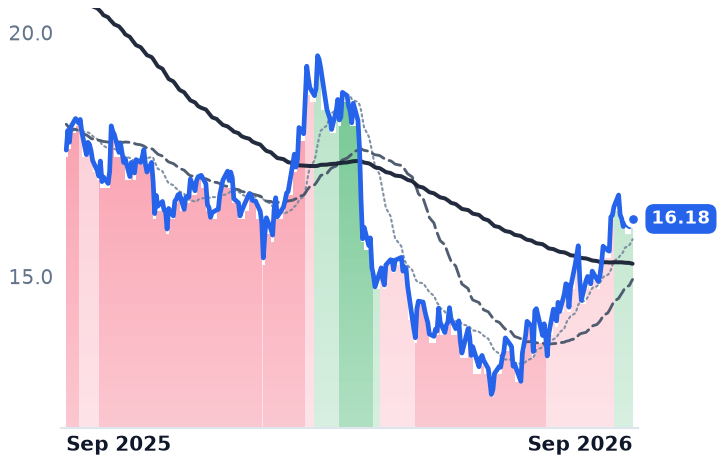
TRNO | Terreno Realty | Logistics & Distribution | 🟢 Cont. Bull | −8.3% | +20.6% |
POST | Post | Cereals & Breakfast | 🔴 Cont. Bear | −6.6% | −24.4% |
GIS | General Mills | Cereals & Breakfast | 🔴 Cont. Bear | +12.7% | −14.1% |
CAG | Conagra Brands | Frozen & Prepared Foods | 🔴 Cont. Bear | +8.5% | −8.0% |
HRL | Hormel Foods | Meat & Protein Processing | 🔴 Cont. Bear | −12.6% | −8.4% |
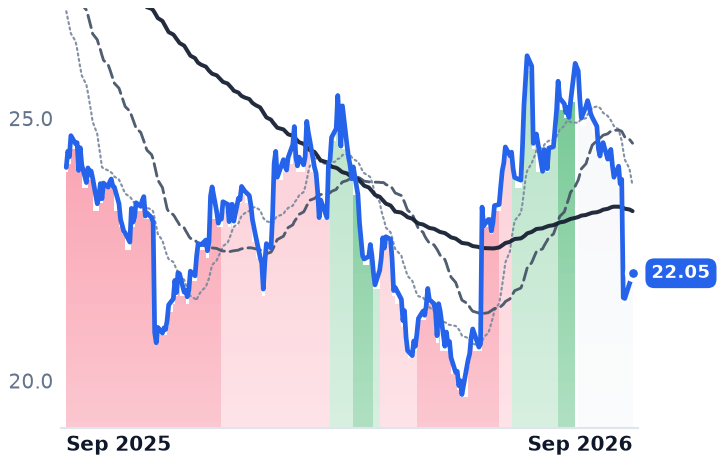
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
COLD | $4.2B | n/m | — | 1.6x | 1.7x | — | — | 126.3x | -2.8% |
LINE | $8.8B | n/m | — | 1.6x | 1.6x | 15.0x | 14.9x | 12.4x | 2.8% |
PLD | $131.0B | 35.2x | 42.1x | 14.6x | 15.1x | 33.8x | 34.7x | 21.4x | 3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FR | $8.1B | 23.5x | 29.1x | 10.8x | 10.7x | 23.0x | 22.7x | 12.2x | 6.0% |
TRNO | $6.9B | 16.1x | 43.0x | 14.1x | 13.5x | 22.1x | 21.1x | 13.5x | 2.9% |
POST | $4.6B | 14.3x | 13.1x | 0.5x | 0.5x | 2.0x | 2.1x | 8.3x | 15.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GIS | $17.6B | 8.1x | 9.6x | 1.0x | 1.0x | 2.9x | 2.9x | 10.1x | 9.4% |
CAG | $6.4B | n/m | 7.9x | 0.6x | 0.6x | 2.4x | 2.4x | 13.8x | 13.1% |
HRL | $10.9B | 22.2x | 13.5x | 0.9x | 0.9x | 5.8x | 5.7x | 12.6x | 5.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
COLD | Revenue | −3.6% | +0.7% | +5.8% |
| EPS | +5159.4% | −113.5% | −28.0% | |
LINE | Revenue | −0.1% | +2.4% | +5.2% |
| EPS | +94.2% | −19.4% | −31.8% | |
PLD | Revenue | +6.7% | +6.3% | +2.8% |
| EPS | +21.3% | +12.3% | +8.1% | |
FR | Revenue | +4.4% | +7.3% | +7.4% |
| EPS | +24.9% | −9.8% | +4.4% | |
TRNO | Revenue | +8.4% | +11.1% | +15.8% |
| EPS | −57.8% | +2.2% | +22.8% | |
POST | Revenue | +2.2% | −0.2% | −0.0% |
| EPS | +9.5% | +13.5% | +14.4% | |
GIS | Revenue | −5.6% | −2.5% | +1.0% |
| EPS | −18.2% | −4.5% | +4.0% | |
CAG | Revenue | −3.1% | −1.3% | +1.1% |
| EPS | −26.5% | −0.9% | +5.0% | |
HRL | Revenue | +1.3% | +1.5% | +2.6% |
| EPS | +7.4% | +7.0% | +5.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Americold filled more of its freezer space this June quarter than a year earlier, and it did so in a market carrying more empty cold storage than at any point in two decades. Physical occupancy at the operator — 185 refrigerated facilities renting space and selling pallet-handling labor to food producers and retailers — rose roughly 300 basis points year over year and more than 200 sequentially, which is not how the season normally runs. Revenue grew 1.9%, after four straight years of annual decline.
That is worth understanding because a cold-storage REIT is only half a landlord. Storage rent is a claim on how much frozen food customers choose to hold; the other half of revenue is labor billed on throughput. When both are shrinking, occupancy gains have to come from somewhere, and the somewhere here is a competitor's building.
The vacancy is in old buildings
US cold-storage vacancy reached 7.7% in the first half of 2026, with move-outs of about 56 million cubic feet against 41 million delivered — the first negative first-half absorption since 2007. New capacity rose 14.5% between 2021 and 2025 while demand grew about 5%, leaving the market roughly 10% oversupplied. But the emptiness is concentrated by vintage: pre-2006 buildings hold 68% of total vacancy, while facilities built between 2006 and 2019 run 3.4% vacant. Scaled operators with modern boxes are absorbing customers from capital-constrained regionals that spent two years cutting price.
Americold held its rates through that fight. Storage rate per pallet turned positive in the June quarter, handling rates rose, and churn stayed at 2.1%. "Our customers are realizing the value of that best-in-class service, and they're coming back to Americold organically and our churn rate is really low," chief executive Robert Chambers told investors on August 6. Fixed commitments are steady at 58% of revenue, though renewal terms now run 12 to 18 months against five years historically — customers are committing, over shorter windows.
The volume line has not turned: throughput pallets fell 1.0%. What carried adjusted funds from operations to $0.35 in the quarter and guidance up to $1.26–$1.32 was self-help — a completed $30m cost program that removed over 400 positions, a second phase targeting $25m more by early 2027, ten facilities exited. "We are not relying on a recovery in demand to create value," chief financial officer Christopher Papa said the same day. On August 31 the company closed a $1.3bn joint venture with EQT covering 12 facilities, freeing roughly $1.1bn to cut debt by about a quarter.
The same market, the opposite quarter
Lineage, the world's largest temperature-controlled REIT at 498 facilities and about three times Americold's cubic footage, posted its first year-over-year occupancy gain since its July 2024 listing — and same-store net operating income still fell 2.9%. Rent, storage and blast revenue per physical pallet slipped 0.7% to $67.28; throughput fell 1.8% with container volumes down 14%; and the share of rent-and-storage revenue under minimum guarantees dropped to 44.5% from a 46.7% peak. Its own raised guidance of $2.80–$3.05 came from capex management and procurement savings. Leverage sits near 6.0x against a 5.0–5.5x target, and a fire at the Big Bear facility costs $15m of second-half EBITDA. Chief executive Greg Lehmkuhl, on August 5: "We wouldn't be surprised at all, and we're certainly hearing on the street, that there'll be a couple of competitor exits in the coming quarters."
The customer evidence supports his supply logic more than any demand thesis. Frozen vegetable stocks were still down 8% year over year at the end of May, and Conagra expects fiscal-2027 volumes down mid-single digits on unusually high price elasticity in frozen.
What the shares have priced
Americold has gained 11.8% over six months and trades at 11.3x the midpoint of guided AFFO, 1.73x book, with a 6.3% dividend absorbing 71% of that guidance — against average closes of $25.72 in 2024 and $16.67 in 2025, so the recovery has barely dented a two-year de-rating. Lineage is down 9.8% over three months at 13.3x guided AFFO, 12.4x trailing EBITDA and 1.12x book, about half its $78 IPO price; JPMorgan rates it Underweight. Over twelve months, while Prologis rose about 25%, neither operator participated in the industrial REIT rally.
The verdict is that the price gap between them is earned, and the reason it is earned is narrower than it looks. Americold's inflection is real but rests on rate discipline and cost removal, not on more food moving — its throughput is still shrinking, and consensus still models FY2026 revenue down 3.6%. Lineage's discount rests on a committed-revenue share going the wrong way while it carries the sector's heaviest balance sheet. Neither is a bet on frozen-food demand; both are bets on which operator absorbs the regionals that leave.
If Lehmkuhl is right that competitors exit in the coming quarters, the 68% of vacancy sitting in pre-2006 warehouses is the inventory that has to disappear before either operator gets pricing power back rather than just share.