

Wolfspeed Needs $800m of Annual Sales to Break Even and Is Running $200m Short
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Wolfspeed's substrate business — the vertically integrated end that was supposed to be its moat — is the part that broke. Materials revenue fell 45% year over year to $43.3m in the June quarter on what the company called tightening demand and increased competition, while power devices rose 6% sequentially on AI data-center orders.
Group revenue of $149.6m leaves the company running near a $600m annual rate against the roughly $800m management says gross margin requires, with depreciation on two 200mm fabs running regardless. Both listed wide-bandgap pure-plays roughly halved over three months, but only one business deteriorated: Navitas grew revenue 22.5% sequentially, guided to $13.5m, and still trades near 80 times trailing sales.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
WOLF | Wolfspeed | Discrete & Power | 🌱 Emerging Bull | +9.4% | +20.6% |
NVTS | Navitas Semiconductor | Other | ⚠️ Emerging Bear | −2.7% | +94.6% |
| Compared against · context, not the story | |||||
VSH | Vishay Intertechnology | Discrete & Power | 🟢 Cont. Bull | −13.5% | +110.2% |
ON | ON Semiconductor | Analog & Mixed-Signal | 🟢 Cont. Bull | −10.8% | +47.8% |
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | 🟢 Cont. Bull | −10.4% | +48.9% |
STM | STMicroelectronics | Analog & Mixed-Signal | 🟢 Cont. Bull | −2.8% | +94.9% |
IFX.DE | Infineon Technologies | Semiconductors | ⚠️ Emerging Bear | −9.3% | +69.7% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +7.9% | +31.4% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.0% | +20.5% |
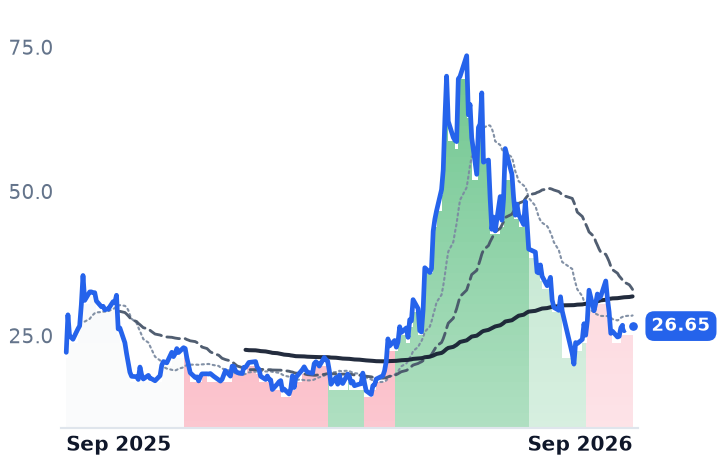
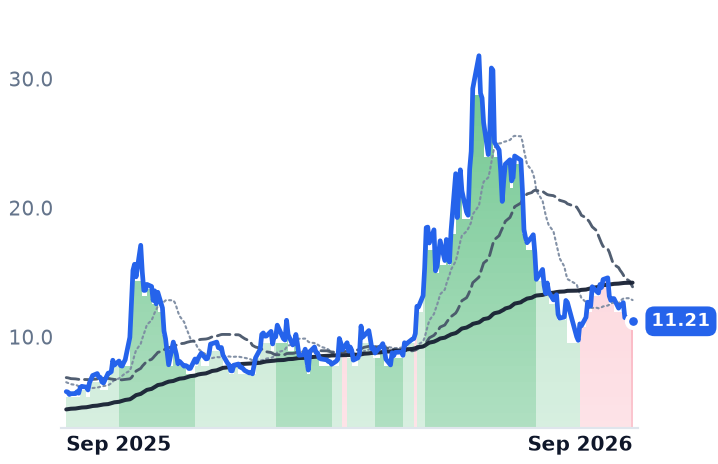
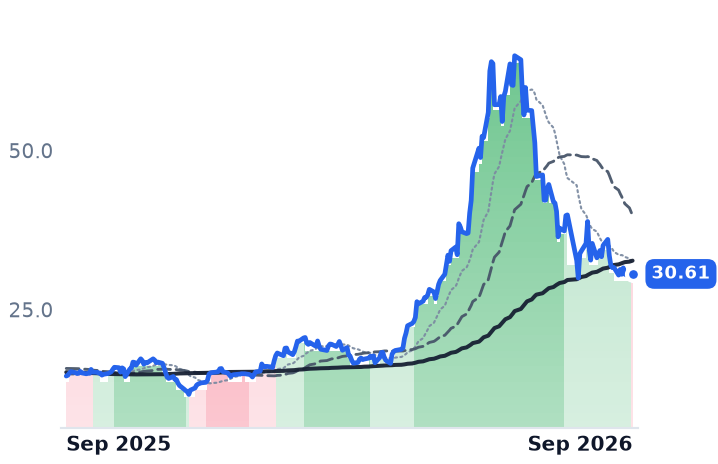
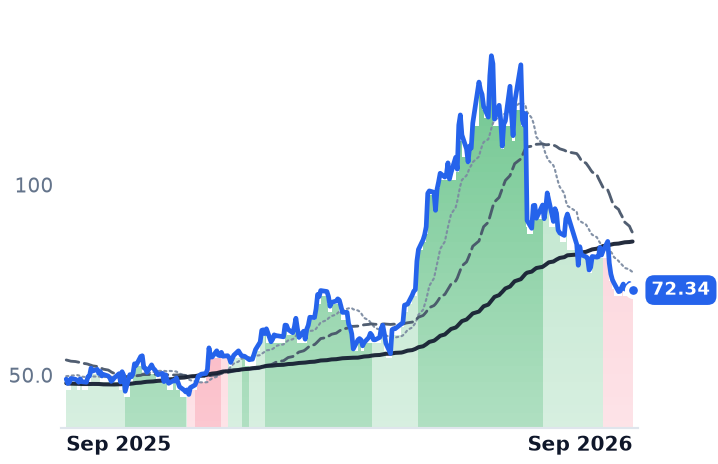
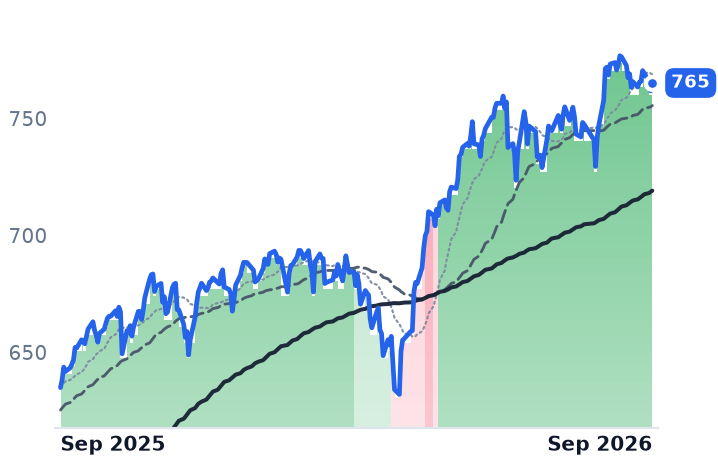
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WOLF | $1.4B | n/m | — | 2.1x | 2.2x | — | — | n/m | -25.5% |
NVTS | $2.9B | n/m | — | 80.1x | 61.4x | — | — | n/m | -2.3% |
VSH | $4.3B | 118.1x | 36.1x | 1.0x | 1.2x | 5.0x | 5.6x | 11.3x | -0.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ON | $32.5B | 52.8x | 26.1x | 5.2x | 5.0x | 14.0x | 13.2x | 26.4x | 5.5% |
MPWR | $64.7B | 80.3x | 48.0x | 19.8x | 15.6x | 35.8x | 28.2x | 62.9x | 0.9% |
STM | $49.8B | 107.2x | 41.7x | 3.7x | 3.5x | 10.9x | 10.1x | 22.5x | 0.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IFX.DE | $77.5B | 70.8x | 35.7x | 5.1x | 4.9x | 13.0x | 12.4x | 22.0x | 1.5% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% | |
NVTS | Revenue | +4.7% | +52.5% | +59.8% |
| EPS | −21.9% | −17.9% | −44.8% | |
VSH | Revenue | +21.1% | +15.8% | +11.4% |
| EPS | −2768.7% | +110.0% | +53.5% | |
ON | Revenue | +9.2% | +12.9% | +13.5% |
| EPS | +37.1% | +41.7% | +31.7% | |
MPWR | Revenue | +49.2% | +28.7% | +20.3% |
| EPS | +54.8% | +31.0% | +20.0% | |
STM | Revenue | +22.4% | +18.7% | +13.2% |
| EPS | +104.2% | +98.3% | +45.6% | |
IFX.DE | Revenue | +8.5% | +14.3% | +11.4% |
| EPS | +15.2% | +43.7% | +21.9% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The substrate business that was supposed to be Wolfspeed's moat is the part that broke. Materials revenue fell 45% year over year in the June quarter, to $43.3m, on what the company called a tightening demand environment and increased competition, while power devices rose 6% sequentially on AI data-center orders.
That leaves group sales running roughly a quarter below the volume management says it needs to break even on gross margin — fixed-cost arithmetic, and depreciation on two 200mm fabs does not care about it. Shares in both listed wide-bandgap pure-plays roughly halved over three months, but only one of the businesses deteriorated: Navitas grew revenue 22.5% sequentially and guided higher, and still trades near 80 times trailing sales.
Wolfspeed — the Durham, North Carolina maker of silicon carbide and gallium nitride materials and power devices — reported its fiscal fourth quarter on August 19, and its two halves moved in opposite directions. Power products, the switches sold into electric vehicles and increasingly into data-center power supplies, brought in $106.3m, up 6% from the March quarter. Materials, which sells silicon carbide substrate wafers to everyone else in the industry, brought in $43.3m, down 45% from a year earlier — a decline the company attributed to a tightening demand environment and increased competition.
The materials line is the one that matters beyond a single quarter, because it was the profitable, vertically integrated end of the business: the Mohawk Valley device fab fed by the roughly $5bn John Palmour Manufacturing Center in Siler City, the only 200mm silicon carbide chain of its kind at scale. Those buildings depreciate whether or not wafers move through them. Management put gross-margin breakeven at roughly $800m of annual revenue and named factory utilization the primary lever. September-quarter guidance is $140m to $160m of revenue with non-GAAP gross margin still negative — about a $600m run rate. Roughly $200m of annual revenue has to appear before the first dollar of gross profit does.
Four quarters down, capital spending switched off
Group revenue was $149.6m, down 24% year over year, at a GAAP gross margin of minus 25% and a net loss of $145m. It was the fourth consecutive quarterly decline, and the guide makes a fifth. Full-year revenue was $665.1m against $757.6m in fiscal 2025. Capital expenditure was cut to $5m in the quarter from $38m against about $1.1bn of cash and roughly $600m of net debt, the legacy of a prepackaged Chapter 11 that closed on September 29, 2025 and took borrowings from about $6.7bn to about $2bn. Chief executive Robert Feurle said the quarter's achievements "strengthen our technology leadership and confidence in our long-term growth opportunities."
The cheap-Chinese-substrate explanation needs a caveat. Six-inch prices in China collapsed from roughly $1,500 to about $500 a wafer, with Tankeblue and SICC taking the number two and three share positions — but Digitimes reported in July that six-inch prices had bottomed and begun recovering as supply tightened. The likelier reading of a 45% decline is lost share and weak electric-vehicle demand landing on top of a price reset that already happened.
What is growing is small and undisclosed. Wolfspeed said AI data-center revenue more than doubled from fiscal 2025 to fiscal 2026 and rose about 20% sequentially, without giving a dollar figure, and on August 6 announced its silicon carbide had been qualified into LITEON's 800-volt direct-current sidecar platform for hyperscale customers.
The fabless side of the same bet
Navitas Semiconductor, the Torrance, California gallium-nitride and silicon-carbide designer that owns no fabs and employs 190 people, is running the opposite cost structure and posted the opposite trend: June-quarter revenue of $10.5m, up 22.5% sequentially, with third-quarter guidance of $13.5m at a 39.7% non-GAAP gross margin, and $557m of cash and no debt. Its data-center content arrives in four dated tranches from the second half of 2026 through 2028, with the largest — in-rack 800-volt conversion — in 2027. "We are also actively engaged with hyperscalers, merchant power customers, data centers, OEM, ODM on multiple program ramping in the second half of 2026 that will accelerate throughout 2027," chief executive Chris Allexandre told investors on the July 27 call. Wolfspeed sued Navitas in Delaware on July 7 over five wide-bandgap patents; Renesas, a large Wolfspeed shareholder, followed on July 22 with a trade-secret claim. Navitas countersued in August and called the suits a sign competitors are losing share.
What the fall does and does not explain
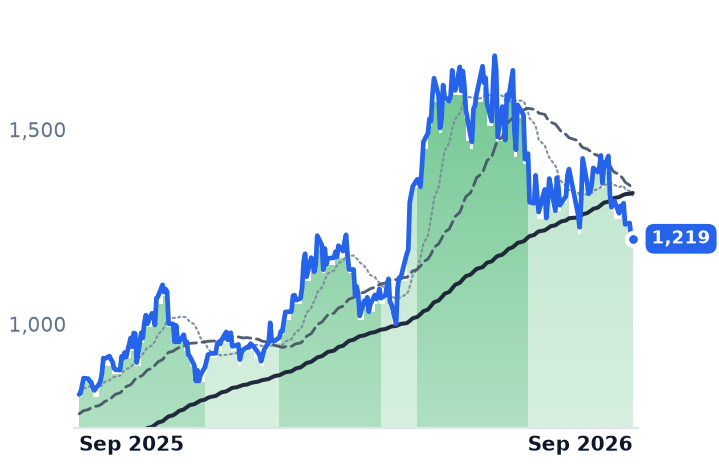
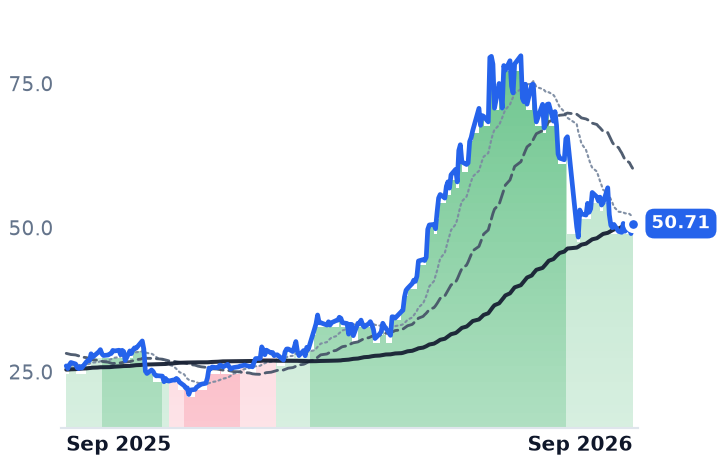
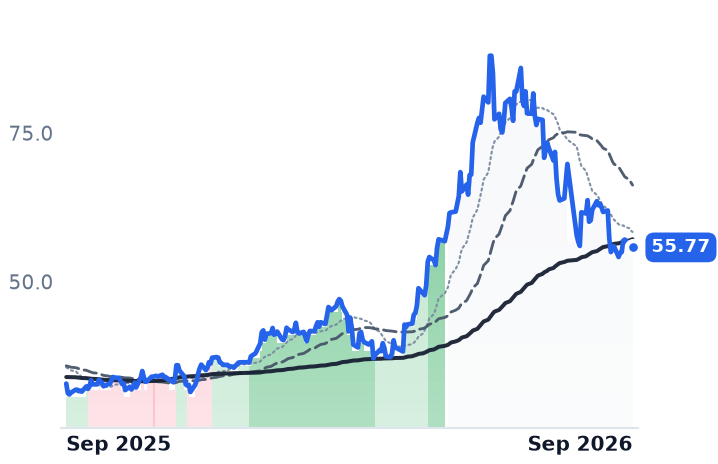
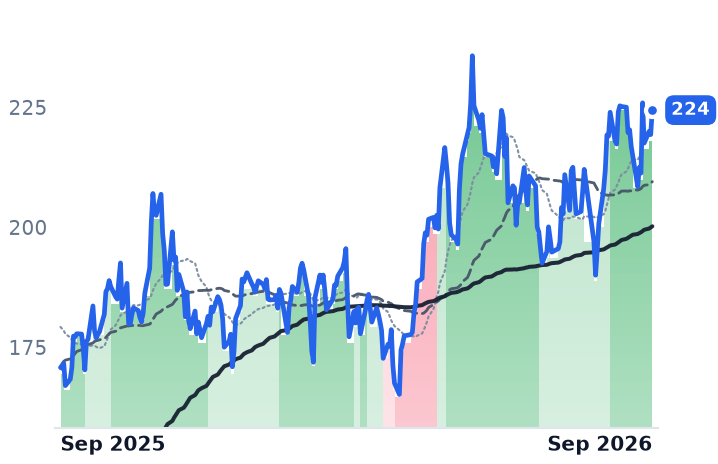
Over the three months to September 2, Wolfspeed fell 55% and Navitas 58% — but silicon-incumbent Vishay fell 41%, onsemi 40% and STMicroelectronics 27% while the S&P 500 rose about 1%. The 20 largest chip stocks shed more than $1.3trn in the days to July 29. This was an unwind of AI-power momentum that hit the pure-plays hardest because they had the least earnings underneath.
Wolfspeed earns its share of it. The shares now change hands at 2.08 times trailing revenue and 2.16 times forward — the forward multiple sits above trailing because consensus has fiscal 2027 revenue falling 15% to $642.8m — and price-to-book is 1.48 times, close to the accounting value of the fabs. Navitas is a different case: the business accelerated and the halving only takes it from roughly 190 times trailing sales to 80, with 61 times forward, against consensus $500m of revenue in 2030 that would still be 5.9 times today's market value. Its fall repriced a story; Wolfspeed's recorded a shrinking one.
Both companies now point at the same prize — 800-volt racks in 2027. Wolfspeed has to fund four more quarters of depreciation to be there to collect it. Navitas has to ship.