

US Army Picked BWXT's BANR Microreactor for the $2.2bn Janus Program
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Three weeks after chief executive Rex Geveden declined to discuss the economics of a pending Army competition, BWX Technologies won a place in it — and the shares had set a 52-week low the day before the award.
The decision lands on the one nuclear business in this group already being paid: backlog of $8.4bn, up 40% year over year, on a 1.7x book-to-bill, with every 2026 guidance line raised in August. Its forward earnings multiple has compressed from roughly 47x in May to 34x while consensus revenue growth accelerated.
The fuel-cycle names it gets traded alongside are a different case. Term uranium rose to $96 a pound and Cameco calls conversion and enrichment pricing elevated, so the meter is not softening; Centrus's earnings are, with operating income down 69% on a 14% revenue gain.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
BWXT | BWX Technologies | Naval & Shipbuilding | ⚠️ Emerging Bear | −9.2% | −1.1% |
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | +7.8% | +28.5% |
LEU | Centrus Energy | Uranium | ⚠️ Emerging Bear | −10.7% | −19.0% |
| Compared against · context, not the story | |||||
UEC | Uranium Energy | Uranium | ⚠️ Emerging Bear | +17.4% | +6.6% |
UUUU | Energy Fuels | Uranium | ⚠️ Emerging Bear | +17.6% | +25.7% |
NXE | NexGen Energy | Uranium | ⚠️ Emerging Bear | +4.6% | +30.2% |
DNN | Denison Mines | Uranium | ⚠️ Emerging Bear | +13.5% | +43.4% |
URA | Global X - Uranium ETF | Asset Management | ⚠️ Emerging Bear | +8.0% | +13.9% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | +1.8% | −75.4% |
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −6.6% | −47.7% |
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −13.6% | −50.8% |
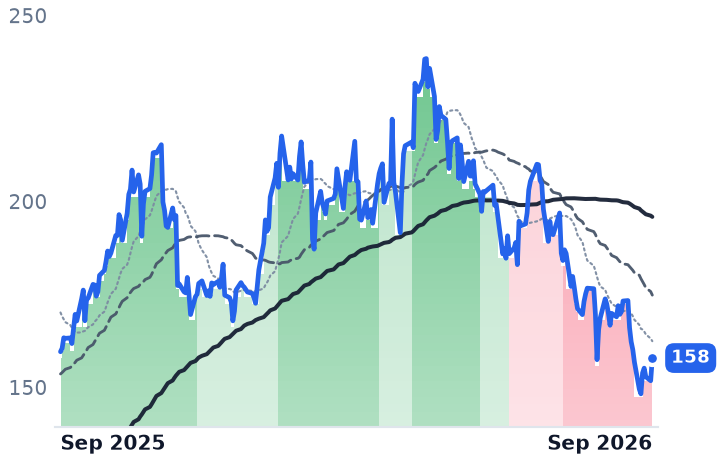
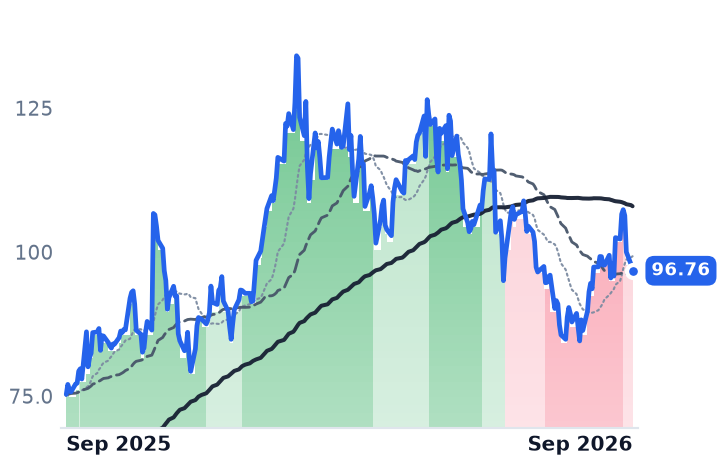
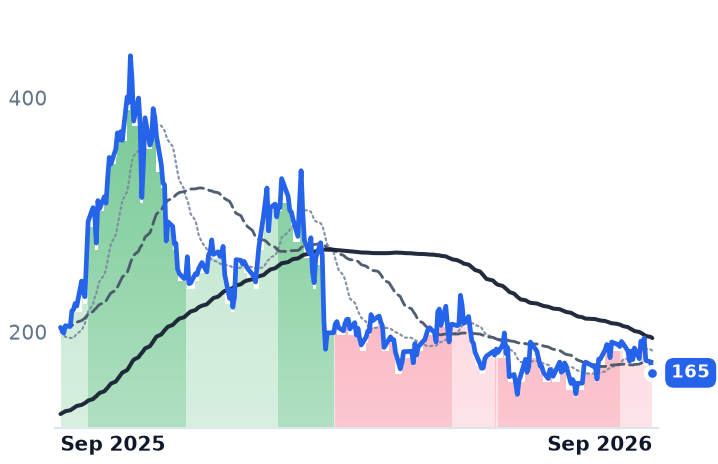
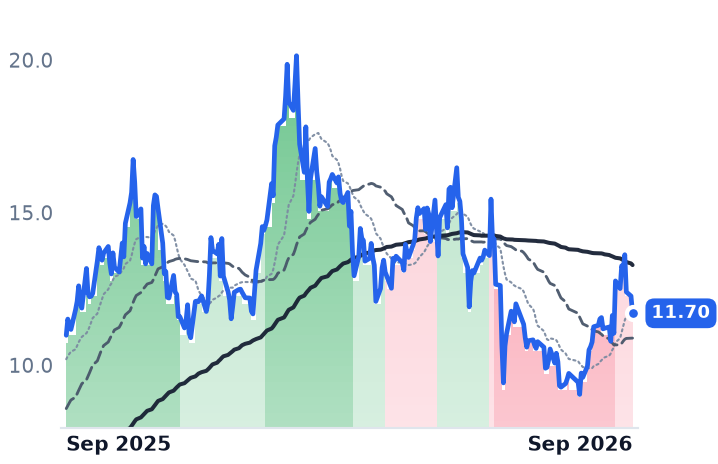
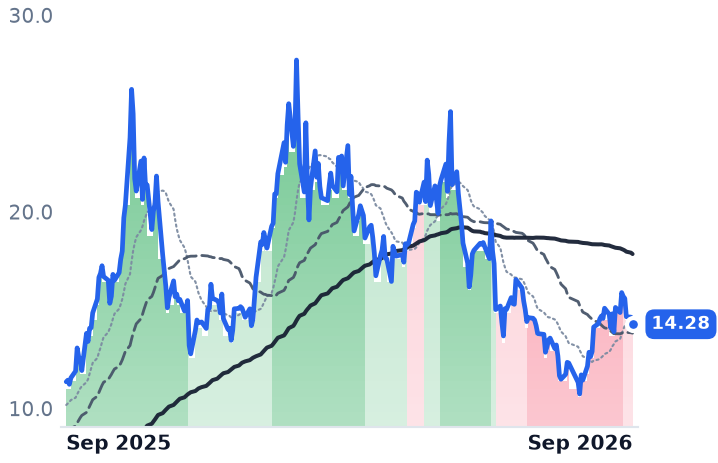
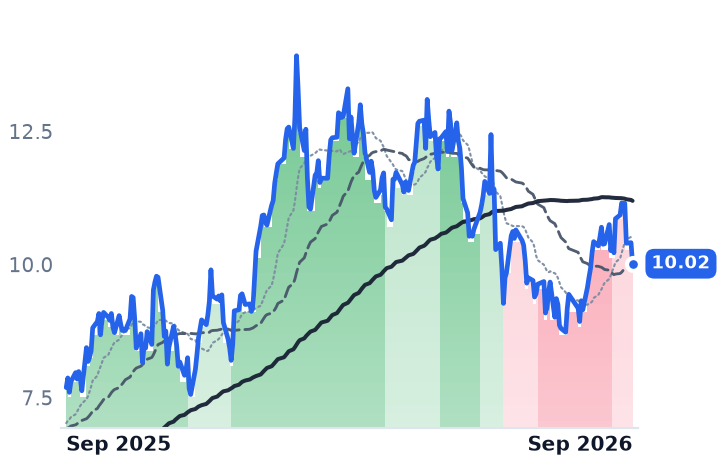
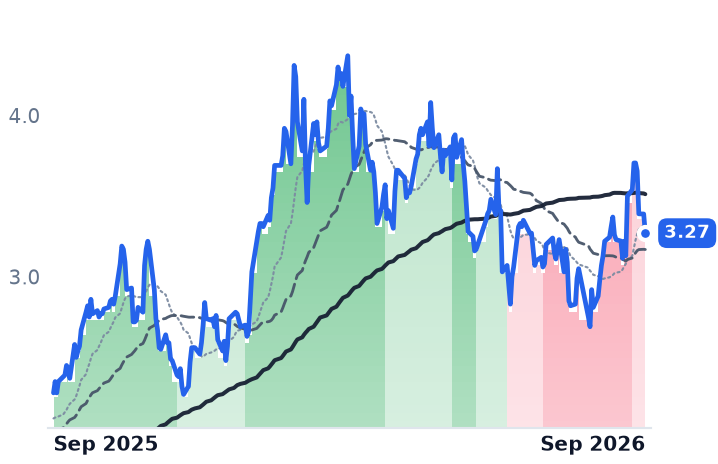
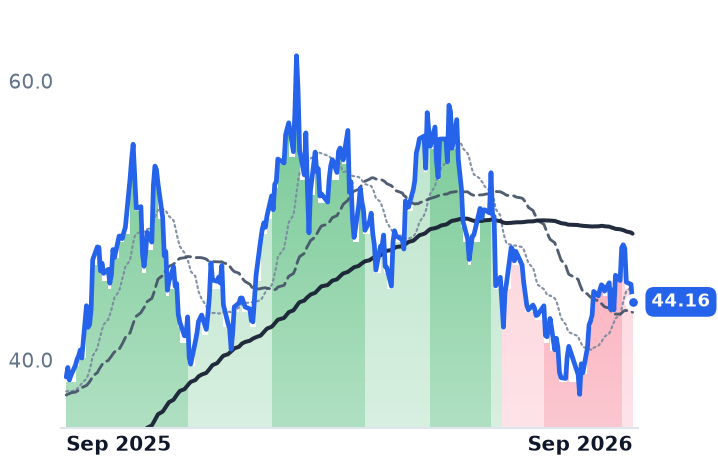
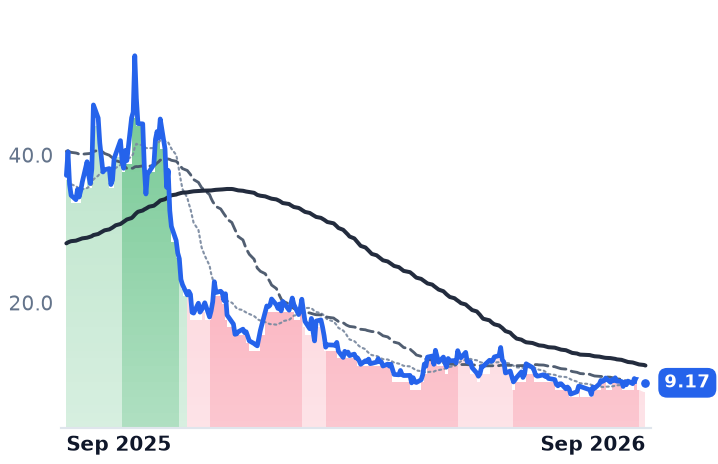
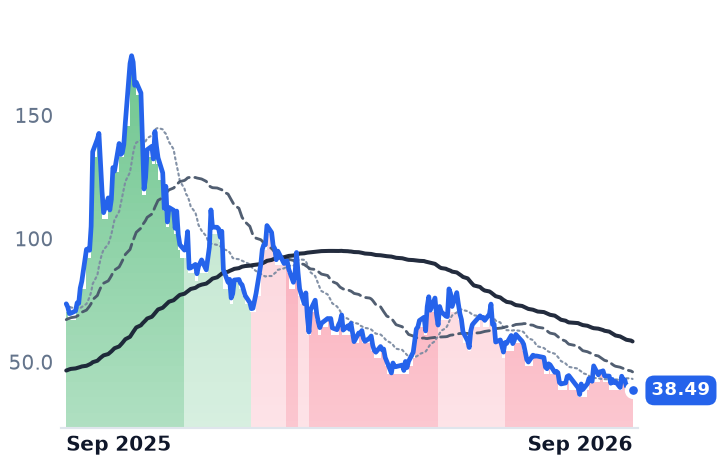
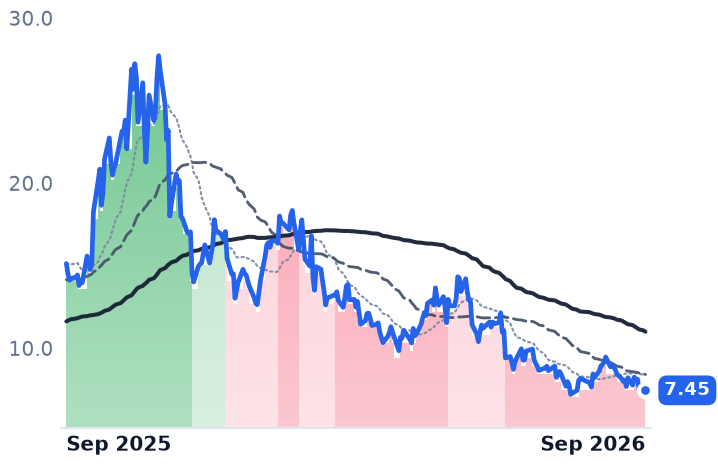
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $14.8B | 41.6x | 34.1x | 4.2x | 3.9x | 19.1x | 17.6x | 29.3x | 2.1% |
CCJ | $41.9B | 163.6x | 62.3x | 16.8x | 11.8x | 60.8x | 42.7x | 67.4x | 0.9% |
LEU | $3.2B | 67.1x | 68.4x | 6.7x | 6.8x | 28.9x | 29.2x | 34.4x | -7.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UEC | $6.5B | n/m | — | 321.7x | 64.7x | 760.1x | 152.9x | n/m | -1.9% |
UUUU | $3.7B | n/m | — | 35.0x | 25.0x | 80.8x | 57.9x | n/m | -3.0% |
NXE | $7.2B | n/m | — | n/m | — | — | — | n/m | -2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DNN | $2.9B | n/m | — | 988.4x | 120.1x | — | — | n/m | -4.1% |
URA | $3.9B | — | — | — | — | — | — | — | — |
SMR | $2.8B | n/m | — | 261.9x | 91.1x | — | 432.7x | n/m | -27.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKLO | $7.3B | n/m | — | — | — | — | — | n/m | -3.8% |
LTBR | $297.0M | n/m | — | n/m | — | — | — | n/m | -5.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWXT | Revenue | +20.6% | +9.8% | +7.1% |
| EPS | +24.1% | +11.4% | +11.6% | |
CCJ | Revenue | +4.0% | +10.9% | +7.7% |
| EPS | +7.7% | +69.4% | +25.2% | |
LEU | Revenue | +4.8% | −0.2% | −9.4% |
| EPS | −45.1% | +17.7% | −15.9% | |
UEC | Revenue | −59.3% | +272.6% | +157.9% |
| EPS | +56.8% | −79.8% | −647.6% | |
UUUU | Revenue | +152.8% | +63.3% | +59.0% |
| EPS | −52.3% | −188.4% | +252.4% | |
NXE | Revenue | −68.7% | +131.4% | +32282.1% |
| EPS | −38.6% | −10.8% | +37.8% | |
DNN | Revenue | +394.2% | −27.3% | +1699.7% |
| EPS | −30.5% | −73.1% | −363.0% | |
SMR | Revenue | −26.7% | +434.9% | +101.2% |
| EPS | −74.7% | +33.4% | −18.3% | |
OKLO | Revenue | — | +241.0% | +577.4% |
| EPS | +50.0% | +10.3% | +16.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
On 26 August the US Army selected BWX Technologies' BANR reactor for Project Janus, a $2.2bn program to build and operate microreactors on military bases, with a 20-megawatt unit destined for Fort Campbell, Kentucky. Five companies were named — Antares, Radiant, General Atomics, Westinghouse and BWXT. Three weeks earlier, on the company's second-quarter call, chief executive Rex Geveden had said he was optimistic about the competition but deferred detail on economics until after negotiation and a possible award.
That resolution matters beyond one base in Kentucky, because BWXT is the only name in the nuclear complex whose orders are already cash. It builds naval reactors and fuel for the US Navy's Naval Nuclear Propulsion Program on a sole-source basis — more than 420 reactors delivered over half a century — alongside commercial reactor components and medical isotopes, and it holds a $1.5bn sole-source defense fuels award and a $1.6bn ten-year high-purity depleted uranium contract from the National Nuclear Security Administration. It competes with heavy-forging suppliers, not with uranium miners.
The order book against the share price
Second-quarter revenue rose 18% to $901.6m, with Commercial Operations up 72%. Backlog reached $8.4bn, up 40%, on a trailing-twelve-month book-to-bill of 1.7x. On 3 August the company raised every 2026 guidance line: revenue to about $3.8bn, adjusted earnings before interest, taxes, depreciation and amortization to $662m-$672m, adjusted earnings per share to $4.70-$4.80 from $4.55-$4.70, and free cash flow to $345m-$360m. Gross margin fell 2.6 percentage points, and the Commercial Operations margin was guided down about a point on hiring and capacity expansion — the cost of building the plant that fills the backlog.
The shares nonetheless closed at a 52-week low of $148.26 on 25 August, down 27% over six months. Forward earnings have gone from roughly 47x in May to 34.1x, and price to gross profit from 24.7x to 19.1x, while consensus 2026 revenue growth accelerated to more than 20%.
The fuel cycle is not the problem
The premise that BWXT is being sold with a softening enrichment market does not survive the price series. Spot uranium finished August near $89.75 a pound, an 18-month high, with the term price adding $2 to $96, up nearly 11% this year. Cameco, the largest listed uranium producer and owner of 49% of Westinghouse, told investors on 31 July that conversion and enrichment pricing "remains elevated despite new supply announcements," left production guidance at 19.5-21.5 million pounds and pointed to contracts covering more than 28 million pounds of average annual deliveries. Centrus, one of two licensed US enrichers, said on 6 August that enriched-fuel prices "had very strong run-up" this year.
What is soft is Centrus's income statement. Second-quarter revenue grew 14% to $176.1m, but separative work unit volumes fell 23% while low-margin resold uranium filled the gap; operating income fell 69% and consensus 2026 earnings per share sit 45% lower year over year. Its forward multiple of 68.4x sits above its trailing 67.1x — the market expects less, not more. Cameco's six-month drawdown is a different failure: second-quarter profit slipped largely on an 18% fall in delivery volumes and a Westinghouse comparison against a one-off Czech payment, and trailing earnings fell faster than the price, so the shares are dearer than in May at 163.6x, not cheaper.
Five sessions that split the group
From 25 August to 1 September the pattern inverted: BWXT rose 6.5% off its low while Cameco fell 9.2% and Centrus 14.1%. No company news is discoverable behind the uranium leg's reversal; coverage attributed the weakness to investors trimming after a rally and to reports of renewed US-Canada trade friction. Given that August's spot move was driven substantially by trust and hedge-fund buying rather than utility contracting, the likelier reading is a squeeze unwinding.
So the ledger divides cleanly. Centrus has earned its de-rating: the enrichment price rose and its enrichment volumes did not. Cameco's is a valuation question the 2027 consensus must answer. BWXT's is the one nothing in the business explains — raised guidance, a 40% larger backlog and now a named Army program, against a multiple a quarter lower than in spring.
BWXT has told investors to expect at least one new-build nuclear equipment order before the year is out. Janus is not that order; it is a reactor the company would build and operate on a base, priced in appropriations rather than in dollars a pound.