

As Crashes Get Rarer, CCC Now Bills 85% by Subscription and 15% by the Claim
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
CCC Intelligent Solutions gets paid when American drivers wreck their cars, and Americans are wrecking fewer of them. The company's own Crash Course data put repairable claims down 9.7% in 2025 and total-loss frequency at a record 23.1% of claims, while insurers file rate cuts citing lower accident frequency.
Rather than ride that meter down, CCC has moved its mix from roughly 80% subscription to about 85% and converts transactional carriers at renewal. Second-quarter revenue rose 9.8% to $285.9m, with artificial-intelligence products above $120m annualized supplying four of the ten growth points and net dollar retention at 107.
The shares are up over three months anyway — but the advance dates to July reports of a sale process and an Elliott stake, not to the numbers.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
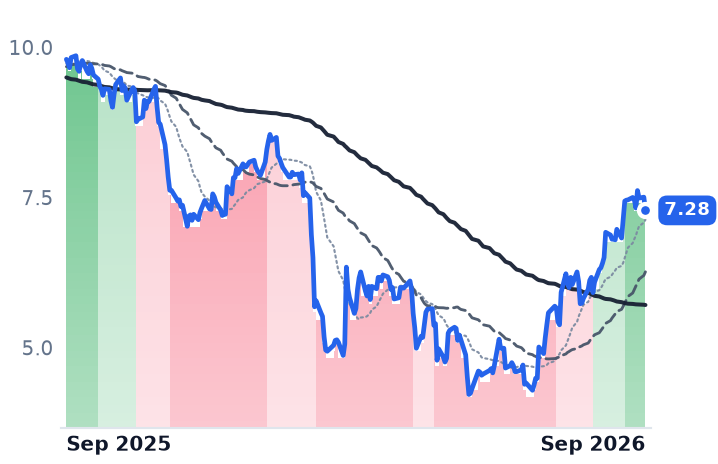
CCC | CCC Intelligent Solutions | Business Software & Automation | 🌱 Emerging Bull | +15.6% | −25.7% |
| Compared against · context, not the story | |||||
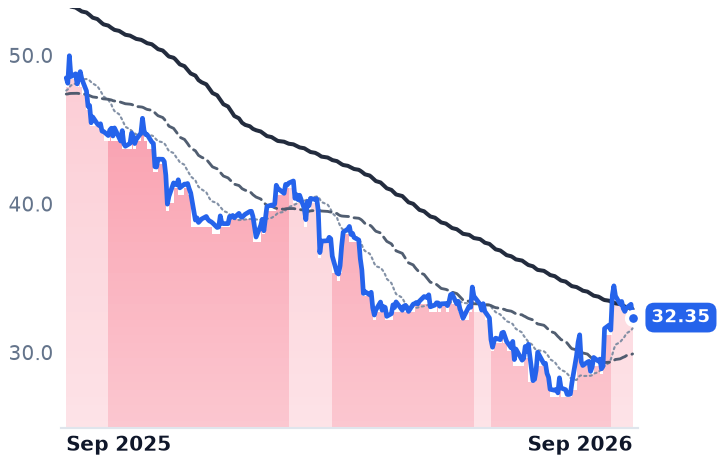
CPRT | Copart | Vehicle & Asset Auctions | 🔴 Cont. Bear | +10.2% | −33.3% |
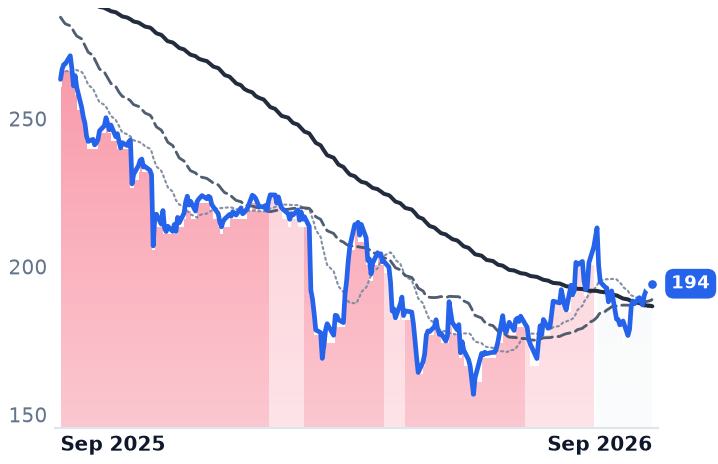
VRSK | Verisk Analytics | Software - Services | 🔴 Cont. Bear | +0.6% | −26.2% |
SPSC | SPS Commerce | Business Software & Automation | 🔴 Cont. Bear | +10.1% | −22.0% |
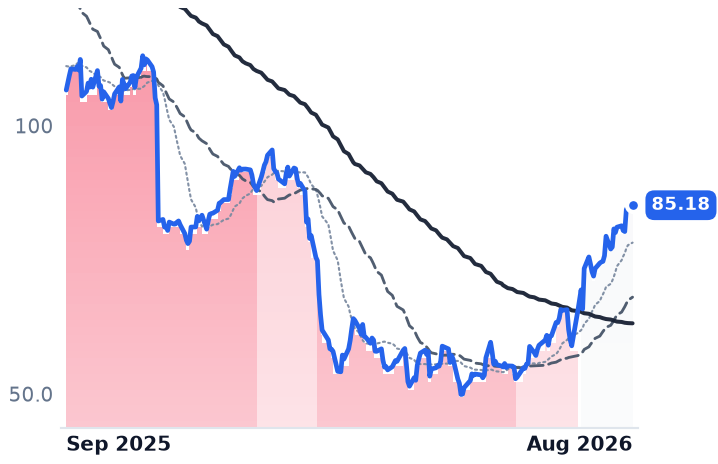
AVPT | AvePoint | Business Software & Automation | 🌱 Emerging Bull | +1.0% | −16.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCC | $4.3B | 109.8x | 16.1x | 3.8x | 3.7x | 5.2x | 5.0x | 17.4x | 7.2% |
CPRT | $31.1B | 20.1x | 20.5x | 6.7x | 6.7x | 14.9x | 14.9x | 13.3x | 4.5% |
VRSK | $21.3B | 24.1x | 21.2x | 6.9x | 6.6x | 10.2x | 9.8x | 14.9x | 5.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPSC | $2.9B | 39.0x | 16.5x | 3.8x | 3.7x | 5.4x | 5.3x | 15.0x | 6.8% |
AVPT | $3.0B | 41.8x | 31.1x | 6.4x | 5.8x | 8.7x | 7.9x | 35.7x | 3.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CCC | Revenue | +10.1% | +8.9% | +8.1% |
| EPS | +26.0% | +16.2% | +13.1% | |
CPRT | Revenue | −1.0% | +4.5% | +6.8% |
| EPS | +1.9% | +6.5% | +8.0% | |
VRSK | Revenue | +4.9% | +6.8% | +6.4% |
| EPS | +10.2% | +13.2% | +11.8% | |
SPSC | Revenue | +5.1% | +6.3% | +7.2% |
| EPS | +18.8% | +8.6% | +13.3% | |
AVPT | Revenue | +22.9% | +20.5% | +19.7% |
| EPS | +33.4% | +10.4% | +28.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Fewer Americans are crashing their cars, and the software company that gets paid when they do has spent the past year rearranging how it bills. CCC Intelligent Solutions — the cloud network that carries collision estimates, total-loss valuations, parts orders and casualty claims between insurers, repair shops and adjusters — reported second-quarter revenue of $285.9m on 30 July, up 9.8%, on a network whose underlying unit count is shrinking.
That gap is the whole story, and it is newer than the sale headlines around it. CCC's Crash Course 2026 report, released 31 March, found repairable claims down 9.7% in 2025, total-loss frequency at a record 23.1% of claims, and average paid bodily-injury severity up 10.3% year on year. Small claims are vanishing fastest: appraisals under $2,000 fell from 41.5% of the mix in 2019 to 25.5% through mid-2025 as deductibles rose. The feedback loop is now visible in premiums — insurers are filing rate reductions citing reduced accident frequency, including an approved 7.6% decrease for Allstate in some states.
Billing away from the meter
CCC's answer has been to sell the network by contract rather than by event. Historically about 80% subscription and 20% transactional, the mix is now roughly 85/15, with chief financial officer Brian Herb describing proactive conversion of transactional clients to subscription at renewal. What replaces volume is attach. In the second quarter, cross-sell and upsell into the existing base supplied 7.5 points of growth and new customers 2.5; software net dollar retention rose to 107 from 106 for 2025, with gross retention of 98%.
The attach is mostly artificial intelligence. "We are a scale player in AI today, generating more than $120 million of annualized revenue from AI-based solutions that are growing at nearly 50% year-over-year," chief executive Githesh Ramamurthy told investors on the July 30 call. Those products are about 11% of revenue and delivered four of the quarter's ten growth points. Penetration is early: CCC disclosed with its fourth-quarter results that more than 125 insurers and over 15,000 repair facilities had adopted AI solutions, but the share of claim volume actually processed through the models runs from low single digits to low double digits.
The strategy works, and it is losing ground. Growth has stepped down from 12.7% to 11.8% to 9.8% across three quarters, with the second half guided near 9% including a one-point headwind from a legacy casualty fleet customer leaving. Gross profit grew 8.6% against revenue's 9.8% as newer AI products carry lower margins — adjusted gross margin slipped to 76% from 78%. And diluted shares fell 9.7% year on year on a $300m accelerated repurchase, so per-share arithmetic is doing work demand is not. EvolutionIQ, the $730m casualty-AI acquisition that closed in early 2025, is fully in the base; management calls the raised $1.161bn full-year guide organic.
What the shares are actually pricing
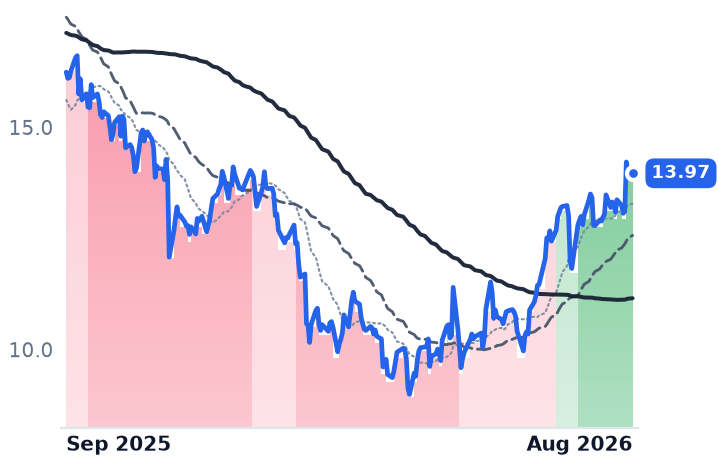
Over twelve months CCC is down about 26% while trailing free cash flow rose 36% to $308m. The recovery since June — a 42% three-month advance — traces to two dates rather than to results: Reuters reported on 9 July that CCC had hired Morgan Stanley to explore a sale, and Bloomberg reported the next day that Elliott had built a large stake. On 18 August Bloomberg reported that salvage-auction operator Copart is in talks against private-equity bidders GTCR and Veritas Capital. Shares rose 10% on the Elliott report and 4.6% on the Copart report.
So the business earns the mix shift and the retention; it does not earn the re-rating. At about 16x forward earnings, against roughly 22x implied by its own price a year ago on the same 2026 estimate, CCC is cheaper than it was — and part of that discount is earned. Claims keep falling. General Motors' February design-patent suits and its trade complaint at the International Trade Commission unusually name CCC and rival Mitchell International alongside parts makers. And on 7 August Solera launched Qapter Direct Dispatch, designed to let insurers send estimate assignments to any shop with an email address regardless of platform — aimed squarely at the network lock-in that is CCC's moat.
A vendor that converts a shrinking transaction stream into contracted subscriptions buys itself years, not permanence: each renewal is repriced against a claim count that is smaller than the last one. What a buyer would be acquiring is the $2trn of historical claims data and 30,500 connected repair shops behind that billing — assets that outlast the meter. What a holder owns until someone signs is a business guided to single-digit growth in a market where the underlying event is disappearing.