

Figma Grew 48% and Still Trailed Its Whole Software Group in August's AI Rally
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Figma's shares have been climbing since late August, but none of the move originated at Figma. The last tranche of post-listing lock-up shares — about 77.7m, roughly 15% of the float — came free on August 8 and the price rose into the supply; the 13% jump on August 27 followed Salesforce's quarter, not any Figma disclosure.
Underneath, the franchise is compounding: revenue reached $370.1m in the June quarter, a third straight acceleration, net dollar retention held at 136%, and customers above $100,000 of annual recurring revenue grew 46%. What the de-rating genuinely earns sits in the cost line — gross margin fell to 83.7% from 88.8% as artificial-intelligence inference landed in cost of revenue, and $316.6m of first-half stock compensation turned a small operating profit into a $117.3m loss.
At 9.02x forward sales against Adobe's 4.39x for roughly a third the growth, the multiple is no longer the problem. Guidance is: management guided the September quarter to 36% growth.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
FIG | Figma | Design & Content Creation | 🔴 Cont. Bear | +9.6% | −58.3% |
| Compared against · context, not the story | |||||
ADBE | Adobe | Design & Content Creation | 🔴 Cont. Bear | +14.7% | −16.6% |
TEAM | Atlassian | Developer Tools & DevOps | 🌱 Emerging Bull | +80.2% | +8.0% |
GTLB | GitLab | Developer Tools & DevOps | 🌱 Emerging Bull | +24.6% | −6.5% |
CRM | Salesforce | Customer Experience & CRM | 🔴 Cont. Bear | +37.8% | +2.2% |
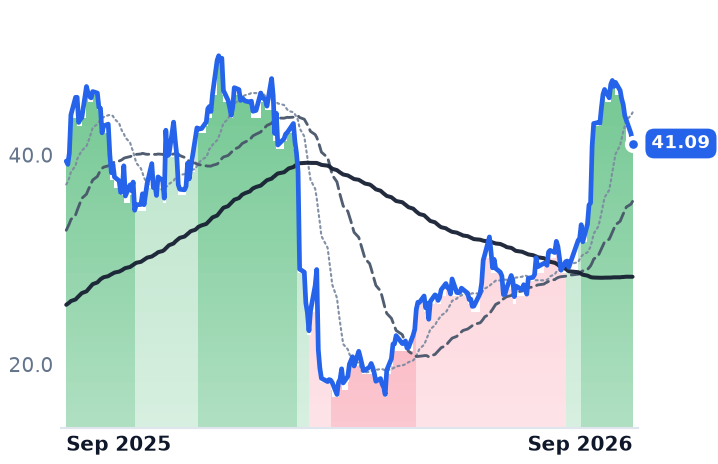
U | Unity Software | Design & Content Creation | 🟢 Cont. Bull | +23.1% | +4.3% |
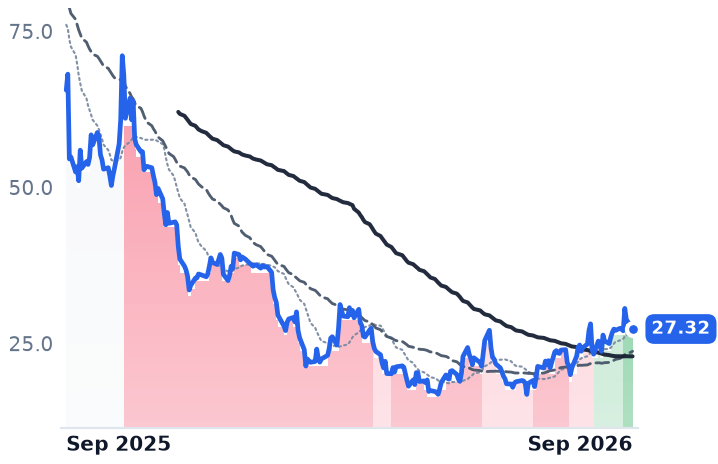
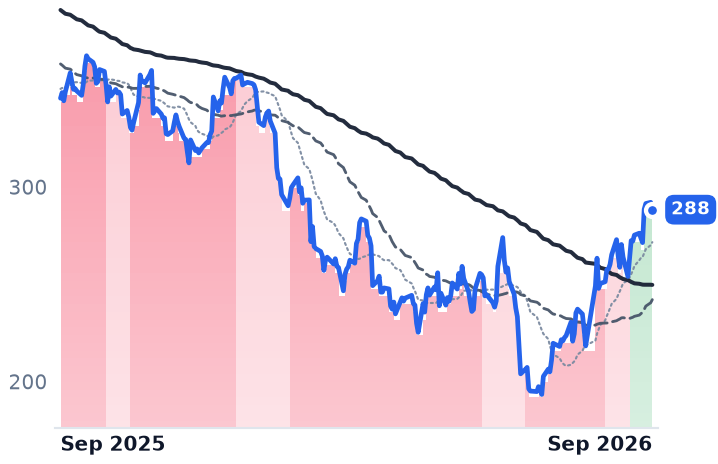
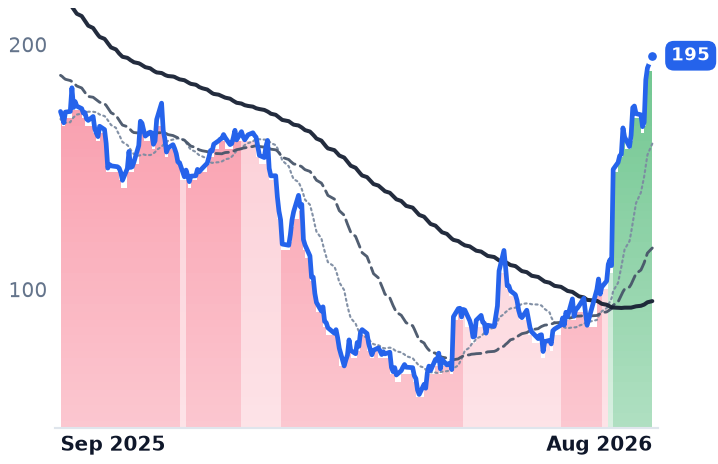
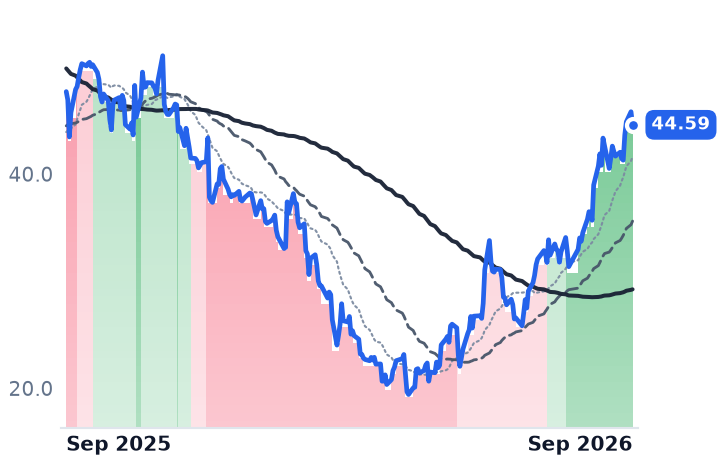
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FIG | $13.3B | n/m | 94.9x | 10.3x | 9.0x | 13.1x | 11.4x | n/m | 1.7% |
ADBE | $116.4B | 16.7x | 12.0x | 4.6x | 4.4x | 5.2x | 4.9x | 11.9x | 9.1% |
TEAM | $50.0B | n/m | 34.6x | 7.6x | 6.7x | 9.0x | 7.9x | 331.1x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GTLB | $7.6B | n/m | 55.5x | 7.6x | 6.8x | 8.7x | 7.9x | n/m | 3.5% |
CRM | $211.4B | 23.5x | 15.8x | 4.8x | 4.6x | 6.2x | 5.9x | 15.5x | 7.2% |
U | $19.8B | n/m | — | 9.8x | 9.3x | 15.9x | 15.1x | n/m | 2.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FIG | Revenue | +40.5% | +23.8% | +24.1% |
| EPS | −24.4% | +26.7% | +34.5% | |
ADBE | Revenue | +12.0% | +9.1% | +8.8% |
| EPS | +17.2% | +12.7% | +14.2% | |
TEAM | Revenue | +24.7% | +15.4% | +14.7% |
| EPS | +55.5% | −0.1% | +21.6% | |
GTLB | Revenue | +25.6% | +17.8% | +15.3% |
| EPS | +40.9% | −8.9% | +25.2% | |
CRM | Revenue | +9.3% | +11.4% | +9.6% |
| EPS | +17.4% | +38.4% | −2.0% | |
U | Revenue | +16.1% | +14.5% | +15.8% |
| EPS | −211.3% | −157.9% | +88.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The supply cleared, and then someone else's earnings arrived
The final block of shares held back by Figma's post-listing lock-up came free on August 8 — some 77.7m shares under an agreement signed in August 2025 with holders of about 54.1% of the Class A stock, releasing on the second trading day after the June-quarter results. Roughly 15% of the float became sellable, and the price rose about 15% over the following fortnight.
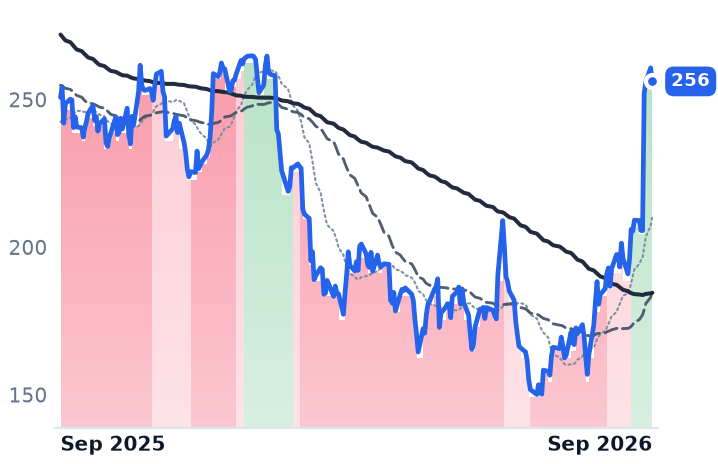
That is the useful fact about the turn in Figma's shares, which have held an uptrend since August 26 with the 50-day average above the 200-day. The company itself has disclosed nothing since its August 5 report. The single biggest session of the advance, a 13.2% gain on August 27, followed Salesforce's second-quarter beat, which recast artificial intelligence for software investors as a revenue line rather than a cost; Atlassian rose 8% the same day. Figma, which sells a browser-based collaborative design canvas to product and engineering teams, was a passenger.
The franchise underneath is compounding
Revenue in the June quarter was $370.1m, up 48.2% — a third consecutive acceleration, from 38% two quarters earlier. Net dollar retention held at 136%. Paid customers above $10,000 of annual recurring revenue numbered 15,964, up 34%, and those above $100,000 reached 1,635, up 46%. International revenue grew 50%. Full-year guidance rose $40m to $1.463–1.467bn, and the quarter threw off $53.2m of free cash flow against $1.7bn of cash.
"Q2 was Figma's third straight quarter of accelerated revenue growth, and as code gets commoditized and value moves up the stack, the opportunity ahead of us has only grown," chief executive Dylan Field told investors on August 5.
What the de-rating does earn
The damage is in the cost line. Gross margin fell to 83.7% from 88.8% a year earlier as inference costs landed in cost of revenue, though it recovered four points from the March quarter. Code Layers, Motion, Weave, the Figma agent and production-code support in Make consume no paid credits and are excluded from guidance — inference expense today, revenue at some unstated later date. And $316.6m of stock-based compensation in the first half, against $7.5m a year before, turned a small operating profit into a $117.3m operating loss. Diluted shares rose only 8.2%, so dilution is not what the market is repricing; the reported loss is.
Competition arrived this spring, when Anthropic launched Claude Design and Canva shipped a foundation-model release within a day of each other, attacking an interface-design position estimated at 80–90% share. Figma also lost its chief product officer, chief marketing officer and sitting chief technology officer in one announcement on the August call.
The lag, and the price of it
From August 3 to September 1 Figma gained 9.6%. Atlassian gained 80.2%, Salesforce 37.8%, GitLab 24.6% and Adobe 14.7%. The stock fell 14.9% the session after its own results and needed another company's print three weeks later to recover. It sits 62% above its June low of $16.84 and 76% below its first trading close of $115.50, with short interest reported by a secondary source at roughly 11% of shares outstanding, undated.
At 9.02x forward sales and 11.40x forward gross profit, against roughly 64x trailing sales at the listing close, the multiple has compressed by around 85% while revenue nearly doubled. Adobe, growing about 12%, trades at 4.39x forward sales — meaning Figma's premium is roughly proportionate to its growth. There is no earnings support: the forward price-to-earnings ratio of 94.9x rests on a non-GAAP consensus of $0.29 a share.
So the honest split: the margin compression and the swing to a GAAP loss justify part of a 58% twelve-month decline, and the acceleration in revenue and retention justifies none of the rest. August did not resolve it — the supply overhang ended and the sector re-rated, neither of which is information about Figma.
The next thing that can be is the September quarter, which management has already guided to 36% growth as last year's pricing change anniversaries. Figma has not confirmed a date for it.