

MongoDB's Atlas Grew 29% and Its Licence Line 13%; the Full Year Is Guided to 19-20%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
MongoDB's business has been telling a cleaner story than its share price. Atlas — the managed document database billed on the compute, storage and queries a customer's applications actually consume — passed a $2bn annual run rate last quarter and added a record $117m of year-on-year dollar growth, while the upfront-licence business it is displacing crept along in the low teens. Net revenue expansion improved to 121%.
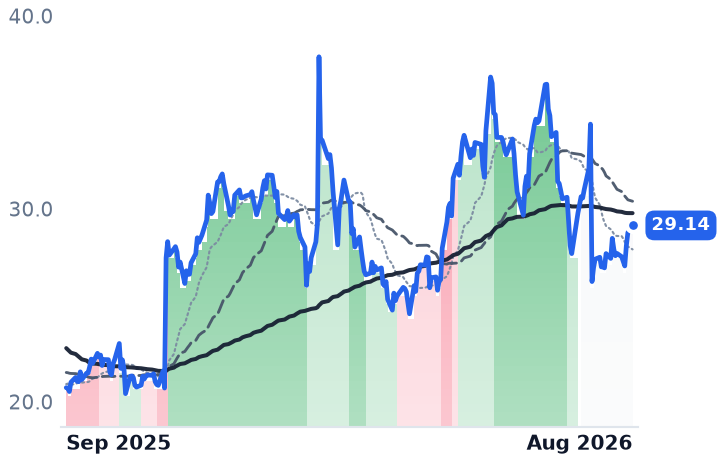
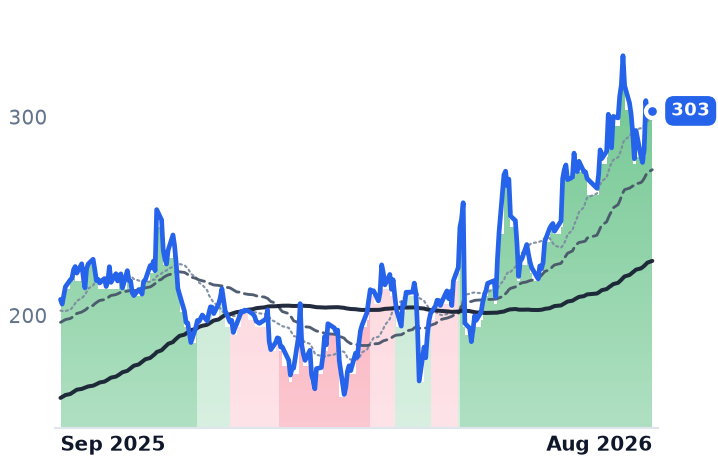
What the financials do not explain is the summer. The shares have roughly doubled from their April low without a single new disclosure since May 28, and the multiple on gross profit has expanded about 46% in five weeks. The second-quarter print lands after the close today, and MongoDB's own full-year guide implies Atlas decelerating through the second half.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MDB | MongoDB | Data Management & Analytics | 🟢 Cont. Bull | +26.7% | +42.4% |
| Compared against · context, not the story | |||||
ESTC | Elastic | Data & Analytics Platforms | 🌱 Emerging Bull | +39.2% | +13.7% |
DDOG | Datadog | Data & Analytics Platforms | 🌱 Emerging Bull | −14.0% | +74.8% |
SNOW | Snowflake | Data & Analytics Platforms | 🌱 Emerging Bull | +6.3% | +39.9% |
TDC | Teradata | Data Management & Analytics | 🟢 Cont. Bull | −9.2% | +40.6% |
DBX | Dropbox | Data Management & Analytics | 🌱 Emerging Bull | +7.4% | +24.7% |
VRNS | Varonis Systems | Data Management & Analytics | 🌱 Emerging Bull | +6.8% | −22.6% |
TEAM | Atlassian | Developer Tools & DevOps | 🌱 Emerging Bull | +88.9% | +13.2% |
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | +7.2% | +45.7% |
ORCL | Oracle | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +5.3% | −33.2% |
NTAP | NetApp | Enterprise Storage & Software | 🟢 Cont. Bull | +2.2% | +64.3% |
DOCN | DigitalOcean | Cloud Infrastructure & Platforms | 🟢 Cont. Bull | −13.7% | +244.2% |
AVPT | AvePoint | Business Software & Automation | 🌱 Emerging Bull | +4.5% | −14.0% |
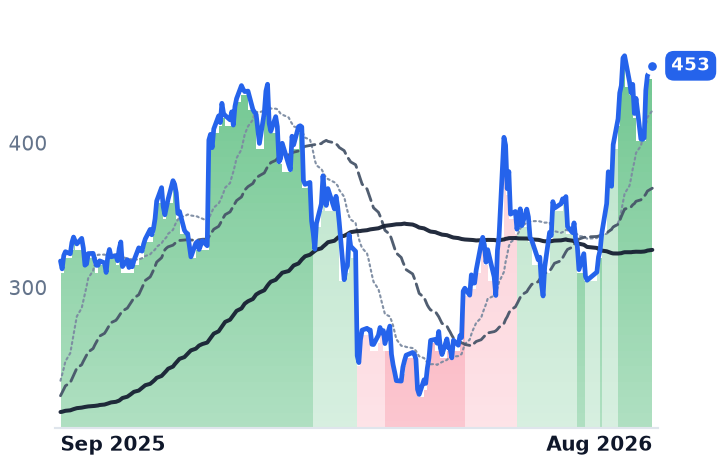
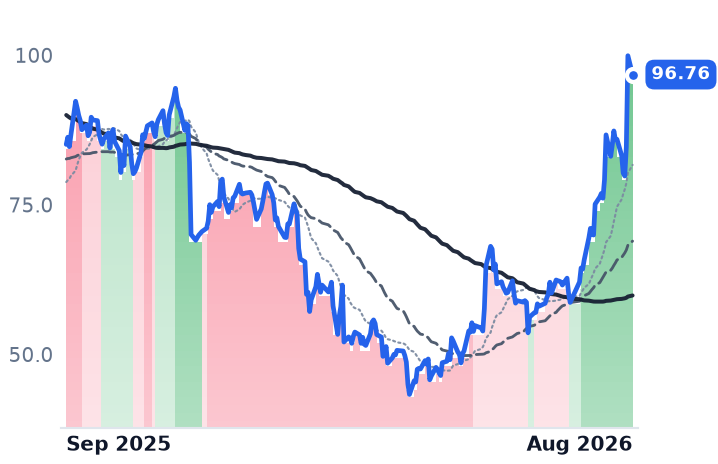
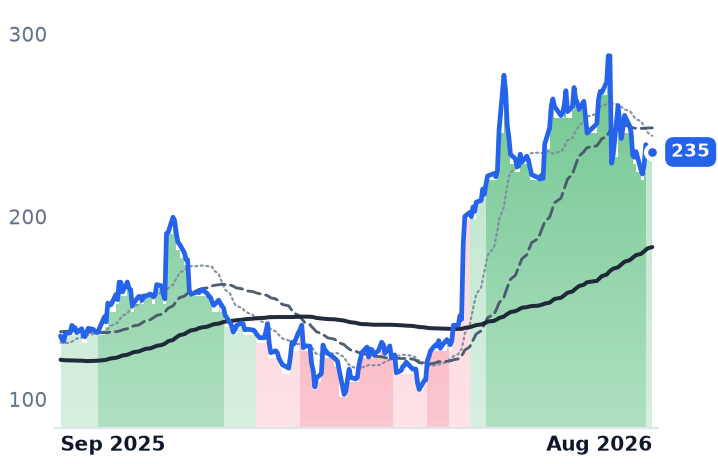
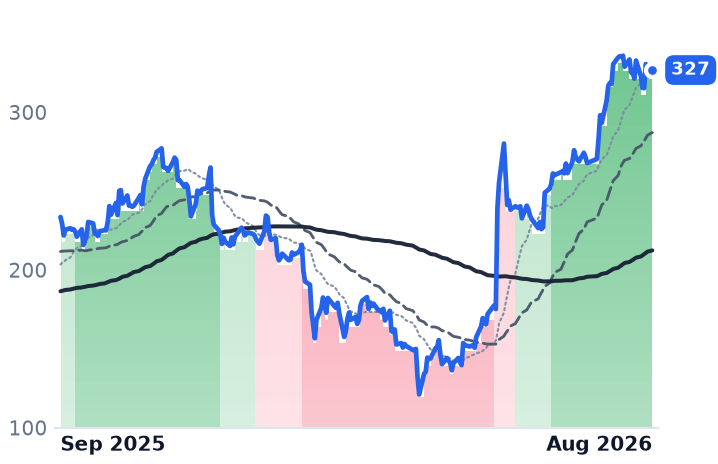
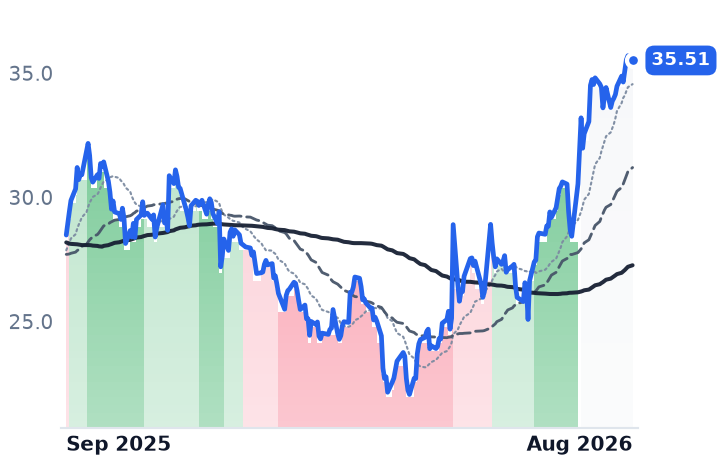
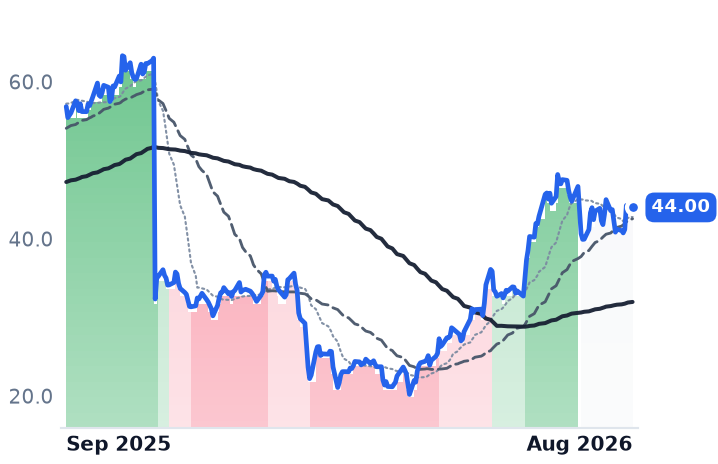
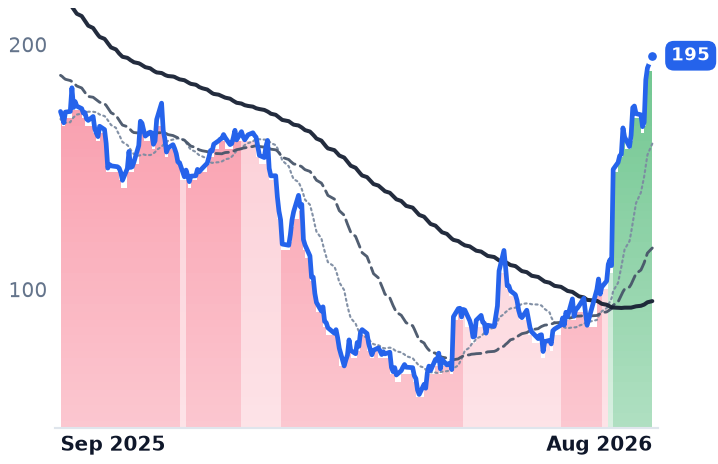
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MDB | $36.5B | n/m | 74.0x | 14.0x | 12.3x | 19.5x | 17.1x | — | 1.6% |
ESTC | $10.1B | 27.0x | 29.1x | 5.6x | 5.1x | 7.5x | 6.7x | 155.2x | 3.4% |
DDOG | $86.5B | 488.6x | 96.0x | 21.8x | 19.4x | 27.4x | 24.3x | 331.7x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SNOW | $113.7B | n/m | 169.5x | 22.6x | 18.6x | 33.6x | 27.7x | n/m | 1.0% |
TDC | $2.6B | 5.6x | 10.2x | 1.5x | 1.6x | 2.5x | 2.6x | 3.2x | 28.6% |
DBX | $8.7B | 18.7x | 11.1x | 3.4x | 3.4x | 4.3x | 4.3x | 13.4x | 11.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRNS | $4.7B | n/m | 278.9x | 6.9x | 6.4x | 8.9x | 8.3x | n/m | 2.6% |
TEAM | $50.0B | n/m | 34.6x | 7.6x | 6.7x | 9.0x | 7.9x | 331.1x | 2.6% |
NET | $106.4B | n/m | 237.7x | 42.3x | 37.1x | 58.3x | 51.1x | — | 0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ORCL | $433.0B | 25.3x | 18.7x | 6.4x | 4.8x | 9.8x | 7.3x | 17.4x | -5.5% |
NTAP | $36.7B | 29.1x | 20.7x | 5.3x | 4.9x | 7.5x | 6.9x | 19.1x | 5.1% |
DOCN | $13.0B | 44.1x | 76.5x | 12.9x | 11.1x | 22.5x | 19.3x | 36.7x | 0.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AVPT | $3.0B | 41.8x | 31.1x | 6.4x | 5.8x | 8.7x | 7.9x | 35.7x | 3.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MDB | Revenue | +23.1% | +21.5% | +18.0% |
| EPS | +59.1% | +27.3% | +19.7% | |
ESTC | Revenue | +17.6% | +15.6% | +14.6% |
| EPS | +30.3% | +32.3% | +17.4% | |
DDOG | Revenue | +31.7% | +22.3% | +22.9% |
| EPS | +25.3% | +17.0% | +22.2% | |
SNOW | Revenue | +29.4% | +31.1% | +26.0% |
| EPS | +72.3% | +59.6% | +42.0% | |
TDC | Revenue | +0.3% | +1.3% | +2.1% |
| EPS | +12.6% | +7.5% | +11.2% | |
DBX | Revenue | +0.3% | −0.0% | −0.3% |
| EPS | +8.5% | +8.3% | +18.4% | |
VRNS | Revenue | +19.2% | +18.8% | +17.4% |
| EPS | +16.5% | +179.0% | +68.6% | |
TEAM | Revenue | +24.7% | +15.4% | +14.7% |
| EPS | +55.5% | −0.1% | +21.6% | |
NET | Revenue | +33.7% | +28.4% | +27.1% |
| EPS | +38.0% | +32.5% | +35.3% | |
ORCL | Revenue | +17.8% | +33.2% | +45.5% |
| EPS | +25.3% | +7.6% | +35.6% | |
NTAP | Revenue | +4.3% | +10.1% | +5.7% |
| EPS | +10.4% | +13.0% | +11.2% | |
DOCN | Revenue | +31.2% | +53.5% | +43.7% |
| EPS | −29.0% | +23.2% | +60.4% | |
AVPT | Revenue | +22.9% | +20.5% | +19.7% |
| EPS | +33.4% | +10.4% | +28.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
MongoDB reports second-quarter results after the close today, its first new financial disclosure since May 28, and the summer has already priced an answer. The company sells a document database in two forms: Atlas, a fully managed multi-cloud service billed on consumption, and Enterprise Advanced, a licensed server a customer runs itself. The meter now supplies roughly three quarters of the revenue.
That split is the whole question. A licence renewal can be signed by a procurement officer once and recognized in a lump; a consumption meter only pays if applications are actually running queries. If the AI-application boom is real in billed dollars anywhere, it should show up here first — and MongoDB is the rare case where the metered line and the licensed line are disclosed side by side.
The meter is doing the work
In the April quarter Atlas revenue reached $512.5m, up 29.4% year on year, against $153.7m for Enterprise Advanced and other, which grew 13%; the licence business's annual recurring revenue grew about 11%. Atlas passed a $2bn annual run rate and posted a fourth consecutive quarter of at least 29% growth, with a record $117m of year-on-year dollar growth. So the ASC 606 worry — growth manufactured by multi-year licences recognized upfront — points the wrong way. The upfront leg is the drag.
The expansion is coming from inside the installed base. Customers paying at least $100,000 of annual recurring revenue rose to 2,895 from 2,506, a 15.5% increase — well short of Atlas's revenue growth, which means existing accounts are consuming more rather than large new logos arriving. Net ARR expansion improved to 121%. Total customers reached 67,700, of which 66,400 are on Atlas.
Nor is the earnings improvement engineering. GAAP gross margin widened to 72.2% from 71.2%, operating margin improved to -3.6% from -9.75%, and the diluted share count rose 0.6% despite a $1bn repurchase authorization dating from June 2025 — so buybacks are not shrinking the denominator. One honest asterisk: chief financial officer Michael Berry reported non-GAAP subscription gross margin of 77.1%, about 60 basis points below the year-ago quarter, on Atlas/Enterprise Advanced mix. The cloud product does carry the thinner margin; it has not yet turned the blended line.
What is billed, and what is given away
The AI layer is metered, not bundled. Voyage AI embedding and reranking — from the acquisition MongoDB folded into Atlas — is billed to the Atlas account tied to the API key, at $0.12 per million tokens for voyage-4-large, $0.06 for voyage-4 and $0.02 for voyage-4-lite, with voyage-4-nano free. But each model carries a one-time, non-refreshing grant of 200 million free tokens per organization — a tranche sized to seed consumption before billing starts — and MongoDB discloses no revenue at all for vector search or Voyage. The only quantification offered was that Voyage customers more than doubled sequentially.
Management's own language is careful. Asked on the May 28 call whether agentic AI had left proof-of-concept, president and chief executive CJ Desai said, "We are ready to scale when someone wants to create an agentic workload in production," adding, "While it's still early, I'm seeing encouraging signs".
The bar for tonight
MongoDB guided the July quarter to $729m–$734m, or 23–24% growth, and raised the full year to $2.92bn–$2.96bn, or 19–20% — a full year guided below the quarter. Cantor Fitzgerald reads that as implied Atlas deceleration to roughly 21% in the second half from the 26% guided for the second quarter, and calls it conservative. Guggenheim expects 29% Atlas growth tonight and a third-quarter Atlas guide of 26% against consensus of 23%. Those are the numbers to hold the print against.
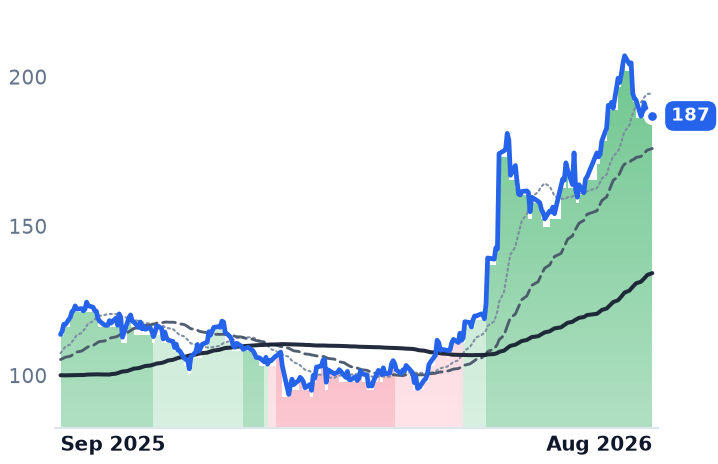
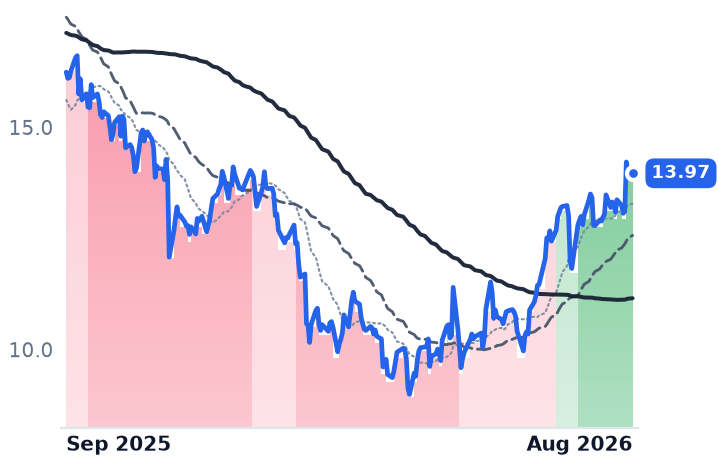
The shares, meanwhile, have run without them. MongoDB closed August up 34.3% on the month and roughly 100% above its April 10 low, and the move began when chip stocks shed more than $1trn in late July on fears AI infrastructure spending was peaking and the money rotated into software. Price-to-gross-profit — the usable lens, since a GAAP loss makes the earnings multiple meaningless — stands at 19.5x trailing and 17.1x forward, against 13.9x on July 20, 15.2x in May and 11.5x a year ago. The market capitalization has gone from $24.98bn on July 29 to $36.47bn, roughly 46% of multiple expansion in five weeks with nothing new disclosed.
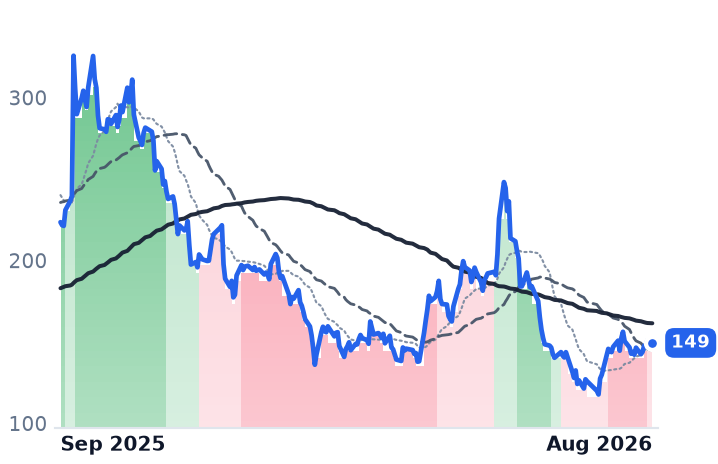
The peers split on the same mechanism. Elastic, MongoDB's closest rival for retrieval-augmented AI work, grew cloud revenue 20% in constant currency and rose 19.3% on August 28 — nine points of growth below Atlas. Datadog is the warning: it grew 35.6% to $1.12bn, its fastest in two years, and still sits well below its pre-print level because its largest AI customer renewed for less. A meter can run backwards on one buyer's budget decision. Snowflake reports the July quarter tomorrow.
So the verdict divides cleanly. The business earns the consumption story: Atlas is outgrowing the licence line by more than two to one, expansion is coming from accounts already onboard, margins are widening and the share count is not being shrunk to flatter anything. What the business does not earn is the re-rating of the last five weeks, which happened on a product launch and a rotation out of semiconductors rather than a number. Tonight the two halves meet.
The 200 million free tokens MongoDB hands each customer are the cheap part of an AI strategy. The expensive part is learning whether the developers who spent them came back and paid.