

GitLab Beat Its Guidance by Five Points While Paying Customers Grew Only 8%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
GitLab's bookings and its paying-account meter told opposite stories in the quarter it reported after the close on Tuesday. Revenue of $286.3m came in five percentage points of growth above the company's own guide, and chief executive Bill Staples claimed record gross bookings — but customers with more than $5,000 of annual recurring revenue grew just 8% year on year, roughly a third the pace of revenue, and dollar-based net retention held at 117% against 118% for the prior fiscal year.
Underneath, the agent economics showed up on the wrong line. Gross margin fell to 84.1% from 87.9% a year earlier, so gross profit grew 16% while revenue grew 21%. Premium seats carry twelve free artificial-intelligence credits a month and Ultimate twenty-four as a launch promotion; that work consumes inference GitLab pays for and bills nobody. The shares have risen 29% in a month into a print the market had not yet seen.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
GTLB | GitLab | Developer Tools & DevOps | 🌱 Emerging Bull | +24.6% | −6.5% |
| Compared against · context, not the story | |||||
TEAM | Atlassian | Developer Tools & DevOps | 🌱 Emerging Bull | +80.2% | +8.0% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +2.5% | −0.7% |
FROG | JFrog | Developer Tools & DevOps | 🟢 Cont. Bull | +14.6% | +93.1% |
CDNS | Cadence Design Systems | Developer Tools & DevOps | 🌱 Emerging Bull | −5.9% | −7.7% |
SNPS | Synopsys | EDA & Design Tools | 🔴 Cont. Bear | +7.0% | −29.2% |
ADSK | Autodesk | Design & Content Creation | 🔴 Cont. Bear | +6.4% | −21.7% |
PTC | PTC | Specialized Enterprise Solutions | 🔴 Cont. Bear | +9.2% | −28.2% |
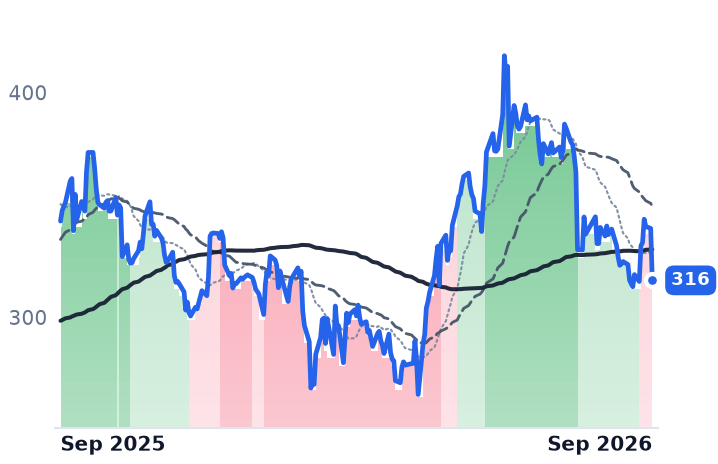
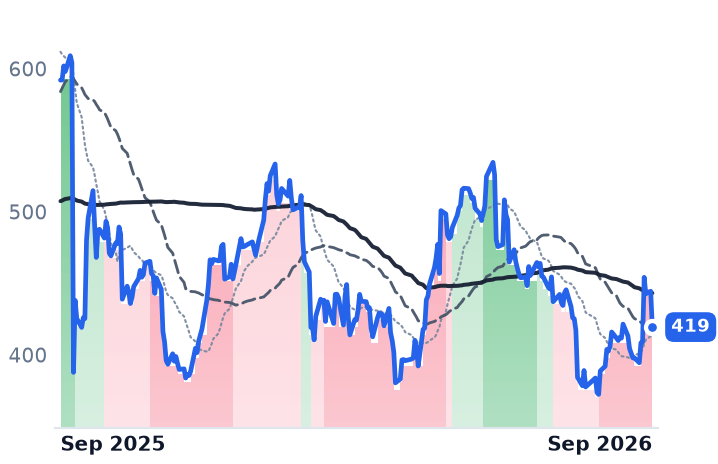
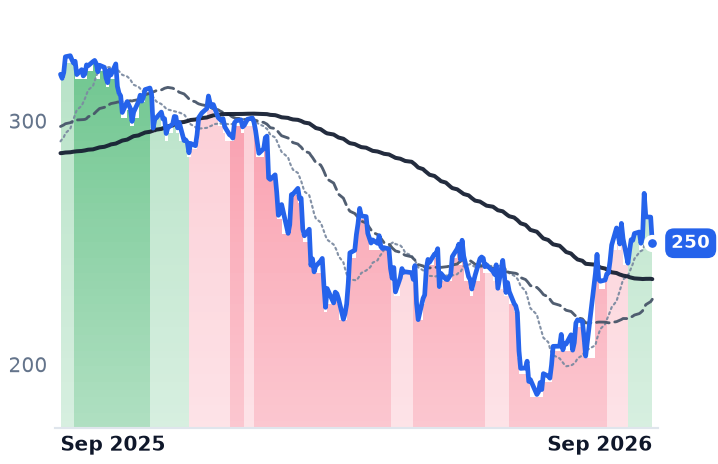
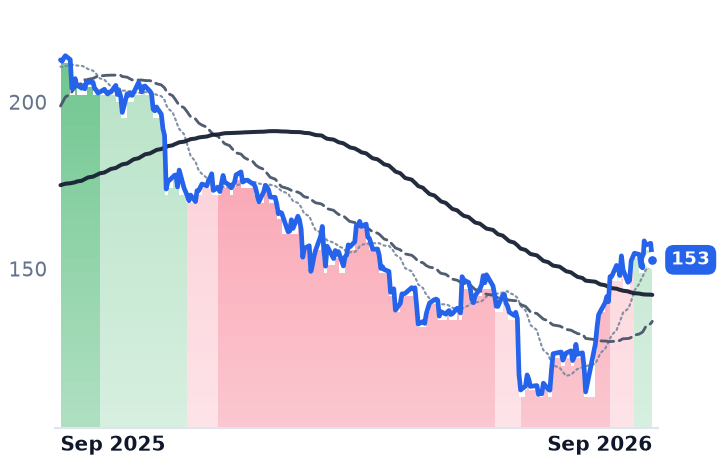
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GTLB | $7.6B | n/m | 55.5x | 7.6x | 6.8x | 8.7x | 7.9x | n/m | 3.5% |
TEAM | $50.0B | n/m | 34.6x | 7.6x | 6.7x | 9.0x | 7.9x | 331.1x | 2.6% |
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FROG | $10.9B | n/m | 92.0x | 18.2x | 16.7x | 23.4x | 21.5x | n/m | 1.6% |
CDNS | $94.6B | 67.9x | 42.2x | 16.2x | 15.0x | 18.3x | 16.9x | 43.8x | 1.8% |
SNPS | $87.1B | 187.9x | 30.8x | 9.2x | 9.0x | 12.8x | 12.4x | 30.7x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADSK | $55.0B | 33.6x | 20.7x | 7.1x | 6.6x | 7.7x | 7.3x | 24.1x | 5.1% |
PTC | $16.9B | 14.1x | 17.9x | 5.7x | 6.2x | 6.8x | 7.4x | 10.8x | 5.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
GTLB | Revenue | +25.6% | +17.8% | +15.3% |
| EPS | +40.9% | −8.9% | +25.2% | |
TEAM | Revenue | +24.7% | +15.4% | +14.7% |
| EPS | +55.5% | −0.1% | +21.6% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% | |
FROG | Revenue | +24.2% | +17.7% | +18.3% |
| EPS | +23.8% | +16.8% | +26.0% | |
CDNS | Revenue | +19.7% | +13.6% | +11.7% |
| EPS | +15.3% | +17.0% | +14.3% | |
SNPS | Revenue | +37.4% | +10.9% | +11.9% |
| EPS | +15.2% | +16.9% | +18.0% | |
ADSK | Revenue | +17.0% | +15.9% | +10.7% |
| EPS | +23.0% | +22.9% | +12.5% | |
PTC | Revenue | +4.9% | +6.2% | +7.5% |
| EPS | +20.1% | +8.5% | +10.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
GitLab reported fiscal second-quarter results after the US market close on Tuesday, its first hard numbers since June, and they land on both sides of the argument the company has been trading on all summer. Revenue of $286.3m, up 21%, beat the company's own guidance of $272m–$274m by about five percentage points of growth. The count of paying accounts did not keep up: customers above $5,000 of annual recurring revenue reached 11,114, up 8% year on year, and those above $100,000 reached 1,571, up 17%.
That gap is the whole question at GitLab, which sells a single platform for planning, building, securing and shipping software and bills for it by the human developer seat. Roughly thirteen points of the quarter's growth came from existing customers spending more — tier mix, price, expansion — rather than from new paying accounts. Dollar-based net retention was 117%, unchanged from the April quarter and down from 118% for fiscal 2026 and 123% the year before.
The credits are priced; the promotion is not
The agent layer is no longer a free giveaway with no meter behind it. Since the Duo Agent Platform went generally available in January, agentic usage has carried a list price of $1 per credit, with agentic code review at $0.25 a review. But Premium seats include twelve credits per user per month and Ultimate twenty-four, described by GitLab as a time-limited launch promotion. Every agent invocation inside that allotment burns third-party inference and compute GitLab pays for and charges the customer nothing.
It shows. Gross margin fell to 84.1% from 87.9% a year earlier, and gross profit grew 16.0% against revenue growth of 21.3% — a widening of the same gap visible in the April quarter. The paid consumption run rate, which GitLab first disclosed in June and restated in a July business update, had surpassed $20m at the end of June — under 2% of an annualized revenue base near $1.14bn. The metered line is real and small; the metered cost is real and already in the margin.
Microsoft's GitHub has converged on the same structure, moving all Copilot plans to usage-based billing on 1 June, with $19-a-seat Business including $19 of monthly credits and promotional allowances on top. The industry did not abandon the developer seat. It turned the seat into an entry fee and subsidized the meter behind it.
What the bookings say
"Q2 was an exceptional quarter, with record gross bookings and net ARR growth exceeding 40% year over year," Staples said in the 1 September release. He added that "as AI drives more software creation and more work through the development lifecycle, the context, security, governance and control GitLab provides become increasingly valuable." GitLab raised full-year revenue guidance to $1.112bn–$1.118bn.
The contracted book does not yet corroborate it. Total remaining performance obligations grew 16% to $1.2bn and the current portion grew 20%, both below the 21% revenue line and both slower than the April quarter. That kills the bear case that lengthening contracts were flattering revenue, and replaces it with something less comfortable: backlog is growing more slowly than the profit-and-loss statement. GAAP operating loss widened to $56.9m, a negative 20% margin, against a positive 15% on the non-GAAP presentation.
The verdict
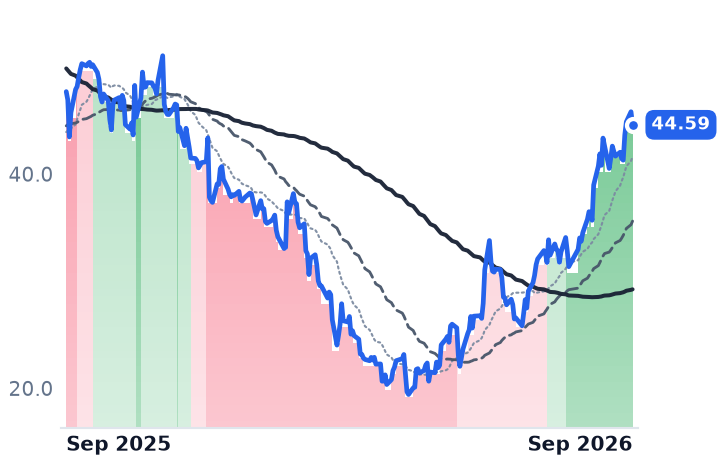
The shares closed at $44.59 on Tuesday, up 29% in a month and 74% off the 21 May low of $25.62, still 7% below where they stood a year ago — and that close predates the print entirely. On recomputed trailing figures the company is valued at about 8.4 times gross profit, against 6.4 times on 29 July and 4.6 times in early May. Forward earnings sit at 55.5 times consensus of $0.81 for this fiscal year, which is 9% below the $0.89 consensus for the year just finished.
So the business earns part of the move: a guidance beat, a raised year, bookings management calls a record. It does not yet earn the rest. Reported growth decelerated for a fifth straight quarter, the paying base expanded at a third the rate of revenue, margin gave up nearly four points, and backlog fell behind the income statement. A 37% expansion in the price paid per dollar of gross profit in five weeks is a bet on bookings converting before the credits stop being free.
GitLab has guided the October quarter to $281m–$283m, sequentially below the one it just reported. The date that matters more is the one it has not set: when the promotional credits expire and enterprises find out what the agent work they already run actually costs.