

Adobe and Autodesk Both Delayed Charging for AI, Cutting Prices to Buy Usage
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The two largest incumbents in design software were supposed to be the first to meter generative artificial intelligence. Both have instead deferred the bill. Adobe told investors in June it would absorb roughly $500m of second-half recurring revenue to push free tiers of Acrobat, Express and Firefly; its separately disclosed AI-first recurring revenue, a little over $500m, equals about 1.9% of a $27.10bn total. Autodesk cut the entry price of its Flex consumption tokens from $300 to $99 and says it has adjusted the timing of charging for machine-based usage.
One line down the income statement the two diverge. Adobe's revenue has accelerated for four straight quarters, yet operating margin fell to 33.8% from 35.9% a year earlier. Autodesk grew revenue 16% with operating margin expanding to 29.3% — though a point and a half of that growth is an accounting reclassification management says stops next year. The cheaper of the two is the one whose operating leverage is running backwards.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ADBE | Adobe | Design & Content Creation | 🔴 Cont. Bear | +17.6% | −18.3% |
ADSK | Autodesk | Design & Content Creation | 🔴 Cont. Bear | +10.9% | −17.2% |
| Compared against · context, not the story | |||||
PTC | PTC | Specialized Enterprise Solutions | 🔴 Cont. Bear | +15.3% | −26.4% |
CDNS | Cadence Design Systems | Developer Tools & DevOps | 🌱 Emerging Bull | +2.3% | −2.9% |
SNPS | Synopsys | EDA & Design Tools | 🔴 Cont. Bear | +18.9% | −26.7% |
FIG | Figma | Design & Content Creation | 🔴 Cont. Bear | +21.3% | −59.0% |
TEAM | Atlassian | Developer Tools & DevOps | 🔴 Cont. Bear | +94.1% | +7.1% |
U | Unity Software | Design & Content Creation | 🟢 Cont. Bull | +29.9% | +9.9% |
CRM | Salesforce | Customer Experience & CRM | 🔴 Cont. Bear | +41.7% | +0.7% |
OKTA | Okta | Identity & Access Management | 🌱 Emerging Bull | +18.4% | +79.2% |
CRWD | CrowdStrike | Cybersecurity & Threat Protection | ⚠️ Emerging Bear | +17.9% | −48.5% |
SEMR | Semrush | Marketing & Advertising Technology | 🟢 Cont. Bull | — | +51.9% |
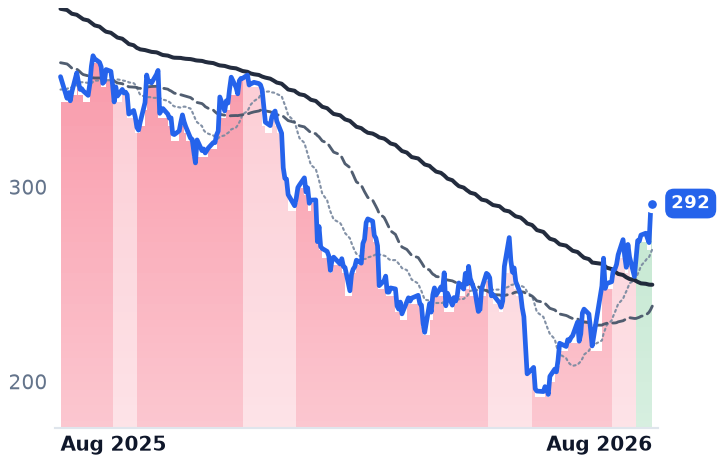
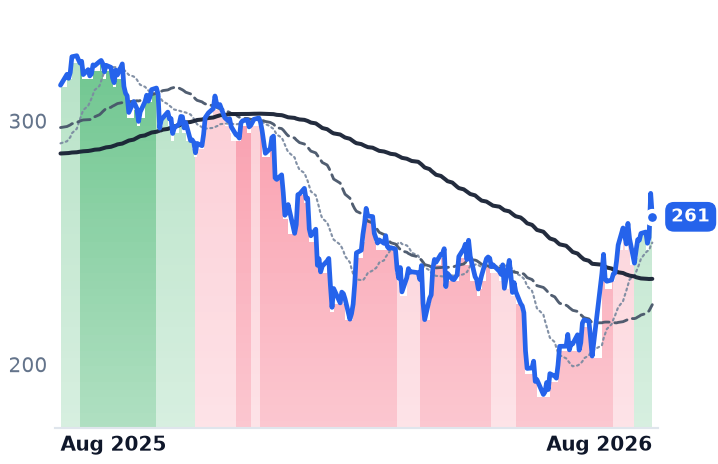
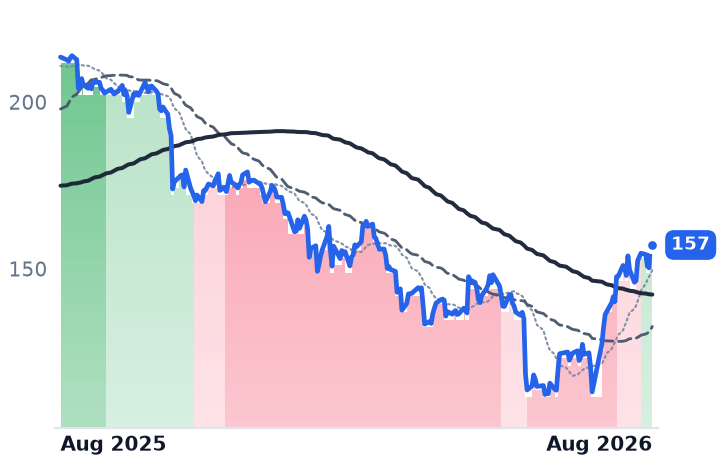
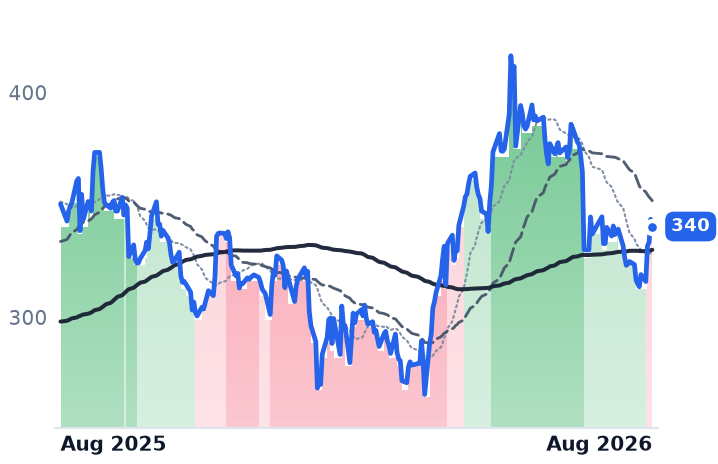
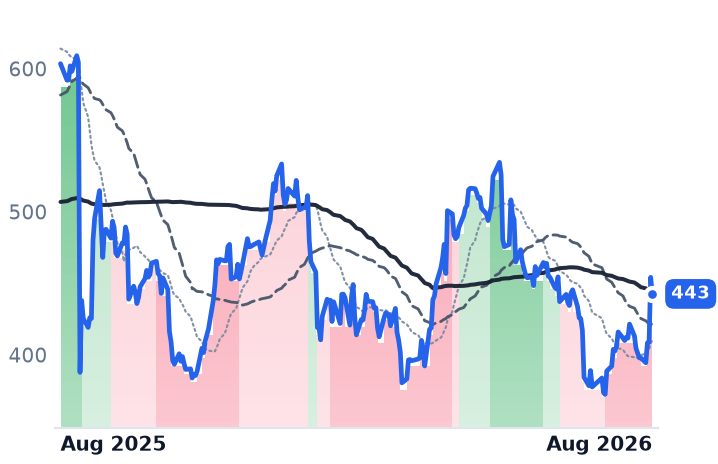
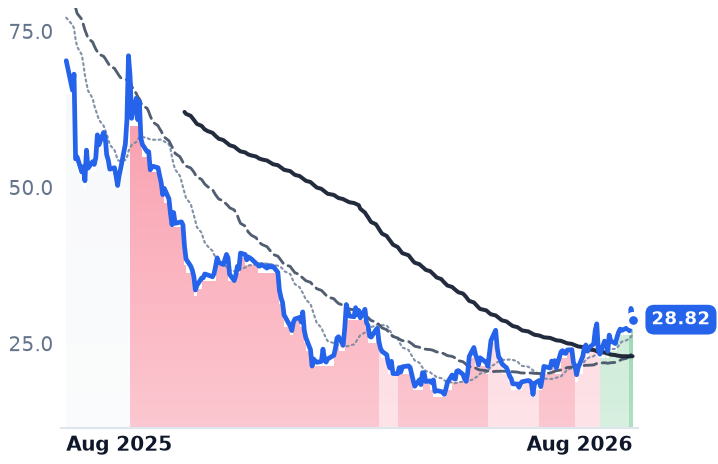
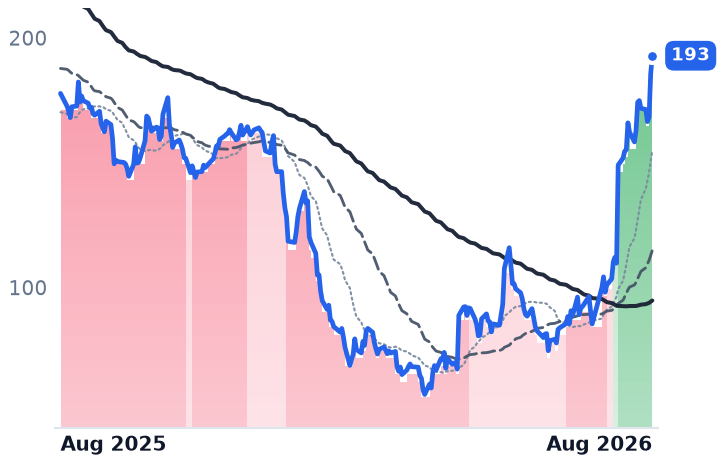
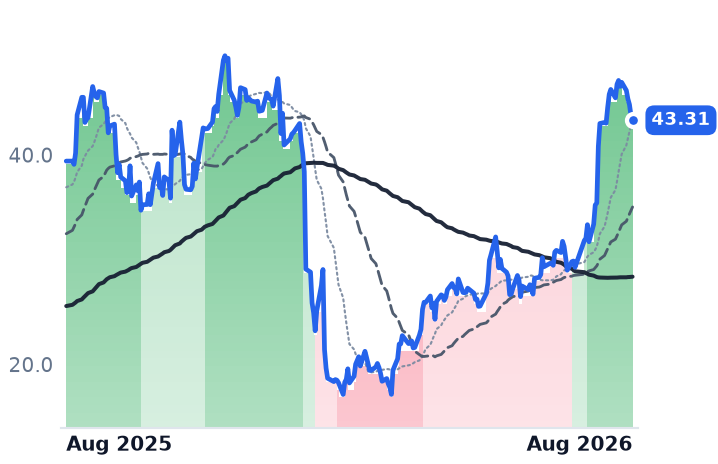
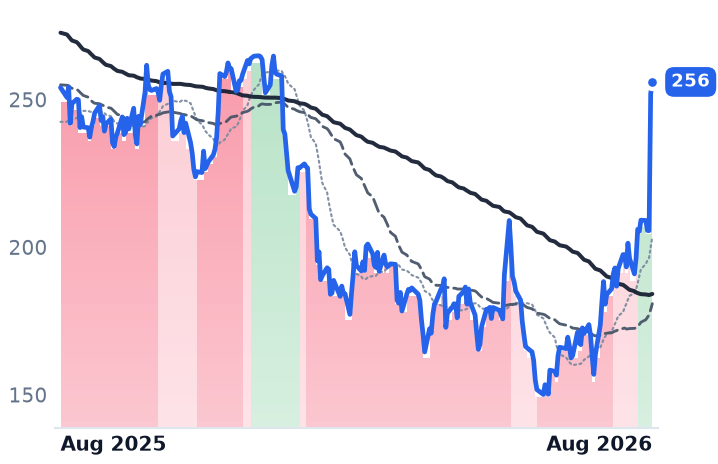
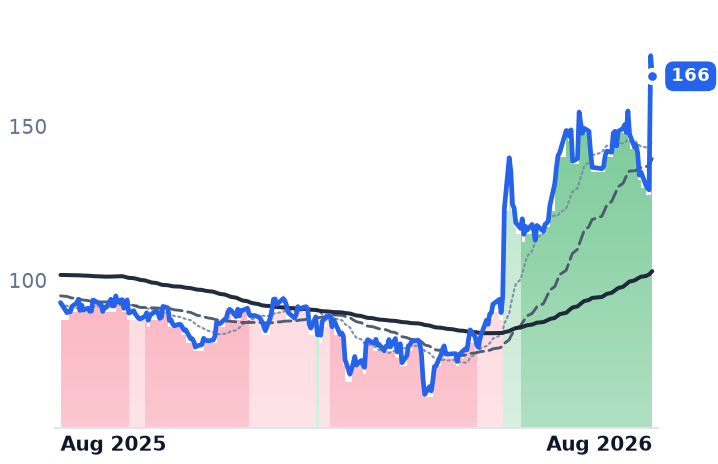
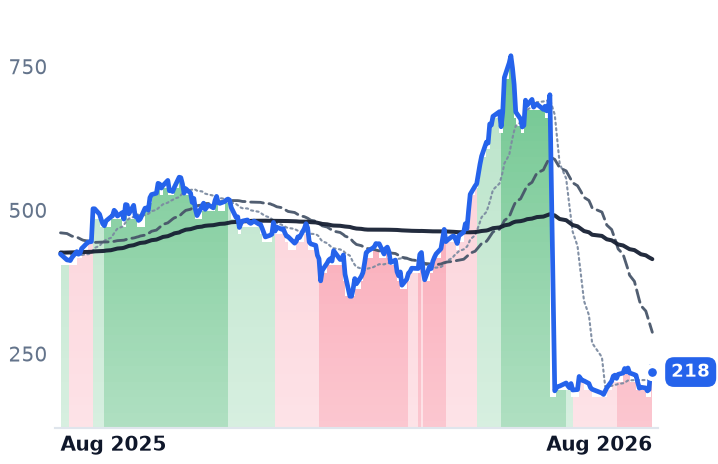
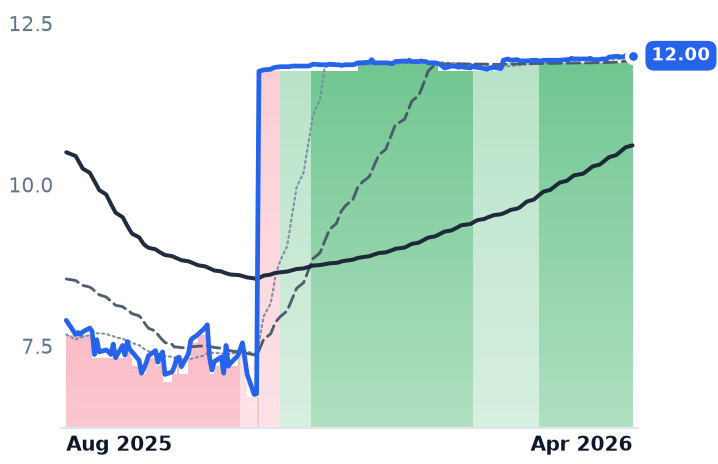
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADBE | $115.9B | 16.7x | 11.9x | 4.6x | 4.4x | 5.2x | 4.9x | 11.9x | 9.2% |
ADSK | $55.0B | 33.6x | 20.7x | 7.1x | 6.6x | 7.7x | 7.3x | 24.1x | 5.1% |
PTC | $16.9B | 14.1x | 17.9x | 5.7x | 6.2x | 6.8x | 7.4x | 10.8x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CDNS | $94.6B | 67.9x | 42.2x | 16.2x | 15.0x | 18.3x | 16.9x | 43.8x | 1.8% |
SNPS | $87.1B | 187.9x | 30.8x | 9.2x | 9.0x | 12.8x | 12.4x | 30.7x | 3.2% |
FIG | $14.9B | n/m | 106.9x | 11.6x | 10.2x | 14.7x | 12.8x | n/m | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TEAM | $50.0B | n/m | 34.6x | 7.6x | 6.7x | 9.0x | 7.9x | 331.1x | 2.6% |
U | $19.8B | n/m | — | 9.8x | 9.3x | 15.9x | 15.1x | n/m | 2.7% |
CRM | $209.7B | 23.3x | 15.8x | 4.8x | 4.5x | 6.2x | 5.9x | 15.4x | 7.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKTA | $27.6B | 98.4x | 43.2x | 9.0x | 8.6x | 11.5x | 11.0x | 68.3x | 3.5% |
CRWD | $222.4B | — | 174.3x | 41.2x | 37.1x | 54.8x | 49.2x | 638.9x | 0.7% |
SEMR | $1.8B | n/m | 30.4x | 4.1x | 3.6x | 5.1x | 4.4x | 254.3x | 2.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ADBE | Revenue | +12.0% | +9.1% | +8.8% |
| EPS | +17.2% | +12.7% | +14.2% | |
ADSK | Revenue | +17.0% | +15.9% | +10.7% |
| EPS | +23.0% | +22.9% | +12.5% | |
PTC | Revenue | +4.9% | +6.2% | +7.5% |
| EPS | +20.1% | +8.5% | +10.5% | |
CDNS | Revenue | +19.7% | +13.6% | +11.7% |
| EPS | +15.3% | +17.0% | +14.3% | |
SNPS | Revenue | +37.4% | +10.9% | +11.9% |
| EPS | +15.2% | +16.9% | +18.0% | |
FIG | Revenue | +40.5% | +23.8% | +24.1% |
| EPS | −24.4% | +26.7% | +34.5% | |
TEAM | Revenue | +24.7% | +15.4% | +14.7% |
| EPS | +55.5% | −0.1% | +21.6% | |
U | Revenue | +16.1% | +14.5% | +15.8% |
| EPS | −211.3% | −157.9% | +88.3% | |
CRM | Revenue | +9.3% | +11.4% | +9.6% |
| EPS | +17.4% | +37.6% | −1.6% | |
OKTA | Revenue | +12.0% | +10.0% | +9.5% |
| EPS | +24.3% | +11.7% | +10.9% | |
CRWD | Revenue | +22.2% | +24.9% | +22.2% |
| EPS | −1.2% | +34.9% | +26.4% | |
SEMR | Revenue | +14.2% | +14.3% | +14.4% |
| EPS | +15.5% | +24.1% | +21.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Adobe told investors in June it would give up roughly $500m of second-half annualized recurring revenue to push free versions of Acrobat, Express and Firefly, and would defer planned price increases to do it. Ten weeks later Autodesk told a different set of investors it had cut the minimum purchase of its Flex consumption tokens from $300 to $99, and that while it remains committed to charging for application programming interfaces and machine-based usage, it has moved the timing out.
Both companies sell the software seats generative AI is most often said to replace — Adobe's Photoshop, Illustrator and Premiere to creative professionals and Acrobat to everyone else; Autodesk's AutoCAD and Revit to architects and builders, Fusion to manufacturers. The expectation was that they would defend those seats by metering AI on top of them. What the disclosure actually shows is two incumbents spending price to buy usage first. Adobe's creative freemium monthly active users went from more than 50m to more than 90m, and total monthly actives passed 850m. Its AI-first recurring revenue tripled year-on-year to surpass $500m — a different $500m from the one being given away, and still under two cents of every ARR dollar.
The mix line went away
Checking price against units at either company just got harder. Effective in the first quarter of fiscal 2026, Adobe combined Digital Media, Digital Experience and Publishing into a single reportable segment, retiring Digital Media ARR in favor of one total — $27.10bn, up 12.5%, of which about $480m arrived with the Semrush acquisition. Autodesk said on August 27 it will stop reporting design and make revenue, substituting construction, Fusion, operations and MaintainX. Each removed the line the question depended on.
Growth without leverage, and leverage without growth
Adobe's revenue rose 12.7% to $6.618bn in its April-quarter, the fourth straight acceleration. Operating income grew 6.1%, and margin fell to 33.8% from 35.9%; diluted earnings per share held at $4.25 mainly because the share count shrank 7.2%. Gross margin was flat at 89.2%, so the cost of generating images is not yet visible in cost of revenue. Meanwhile Canva has reached about $4bn of recurring revenue growing 35%, roughly 15% the size of Adobe's base.
Autodesk is the mirror image. Revenue grew 16.1% to $2.046bn with GAAP operating margin expanding to 29.3% from 25.5% and operating income up 33.1%. But billings grew 10%, slower than revenue; remaining performance obligations of $7.43bn were down 10% against the prior fiscal year end and deferred revenue down 9%, which the company attributes to reducing multi-year discounts. Contract durations are shortening. About 1.5 points of this year's revenue growth is the reseller-incentive reclassification under its new transaction model, and it does not recur next year. Net revenue retention sits slightly above the 100-110% range.
The construction number is the genuine one: growth north of 20% while the Architecture Billings Index stood at 46.6 in July, below the expansion line for nearly three and a half years. That is share taken, not a cycle. "The future of AI won't belong to the company with the best single model," chief executive Andrew Anagnost told investors on the August 27 call. "It will belong to the platform that combines the richest context with the right models to deliver the best outcomes for customers." Chief financial officer Janesh Moorjani said gross margins are flat this year but "will face compression from AI workloads over time."
What the shares priced
On August 27 the whole software complex re-rated on other companies' guidance — Salesforce, Okta and CrowdStrike all surged — and Adobe rose 6.3% and Autodesk 7.2% with no news of their own. That session supplied 61% of Adobe's thirty-day gain and more than all of Autodesk's. The next day Autodesk fell 3.6% after full-year earnings guidance of $12.52-12.60 straddled the $12.60 consensus. Over twelve months Adobe is down 17.6% and Autodesk 9.6%.
Adobe trades at 16.66x trailing and 11.95x forward earnings with a 9.2% free-cash-flow yield, against a five-year median trailing price-to-earnings near 42. Autodesk trades at 33.59x trailing and 20.73x forward — about 1.7x Adobe's forward multiple — on a 5.1% free-cash-flow yield.
The honest split: Autodesk's margin expansion and raised guidance are earned, minus the accounting point and a half; Adobe's move is arithmetic on cash flow from a deeply de-rated base, because nothing in its numbers yet shows AI paying for the seats it is meant to defend. Neither company's August gain was earned by either company.
Adobe's next quarter is the first to carry the freemium giveaway in full, and aggregators list it for September 10, though Adobe has not published the date itself. It will be presented by an interim finance chief: Dan Durn resigned four days after the June print and no permanent successor has been named.