

NetApp's Public Cloud Slipped to 9.9% of Revenue as Hardware Grew 14.3%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
NetApp's fourth quarter was read as proof that a storage-array maker had become a cloud and data-infrastructure company. Its own segment table says the recurring end of the business did not gain share in fiscal 2026: public cloud slipped to 9.9% of revenue from 10.1%, support held at 38.1%, and in the decisive quarter arrays grew faster than the company did.
The growth that arrived is the kind NetApp itself says costs margin. Product gross margin was 56.1% in the quarter against 61.3% two years earlier, and fiscal 2027 group gross margin is guided to 68.5–69.5% from 71.3% on component costs. NetApp reports the quarter its finance chief called the product-margin trough on 2 September, into consensus earnings sitting above the top of its own guide.
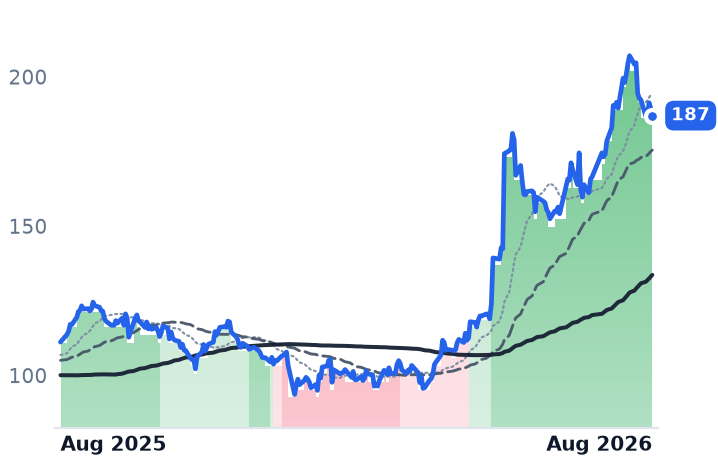
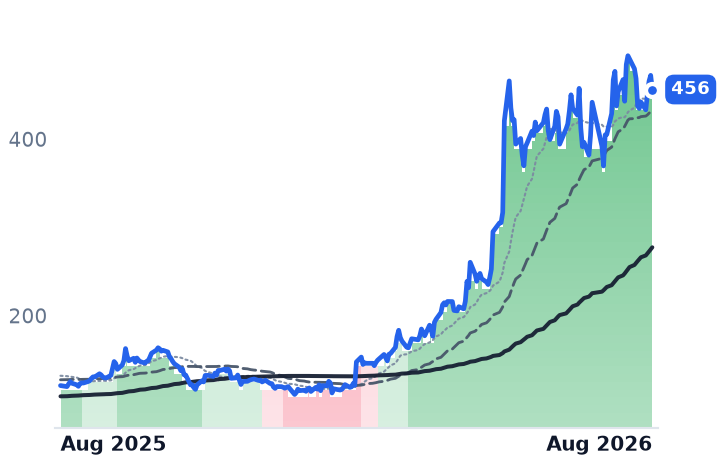
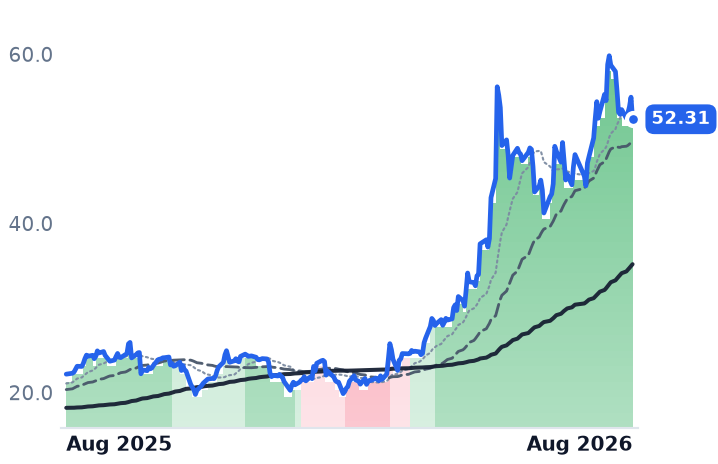
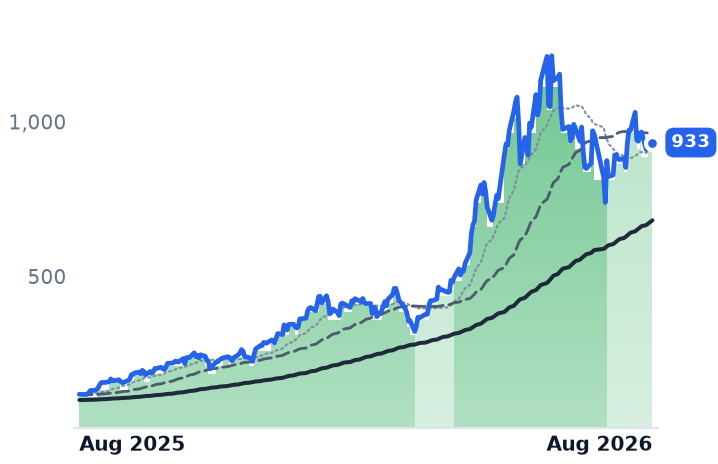
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
NTAP | NetApp | Enterprise Storage & Software | 🟢 Cont. Bull | +7.5% | +68.2% |
| Compared against · context, not the story | |||||
DELL | Dell Technologies | Enterprise Storage & Software | 🟢 Cont. Bull | +12.7% | +277.6% |
HPE | Hewlett Packard Enterprise | Enterprise Storage & Software | 🟢 Cont. Bull | +11.0% | +135.9% |
MU | Micron Technology | Memory (DRAM/NAND) | 🟢 Cont. Bull | +6.7% | +685.0% |
WDC | Western Digital | Data Storage Devices | 🟢 Cont. Bull | −13.8% | +473.3% |
STX | Seagate Technology | Data Storage Devices | 🟢 Cont. Bull | −2.6% | +399.4% |
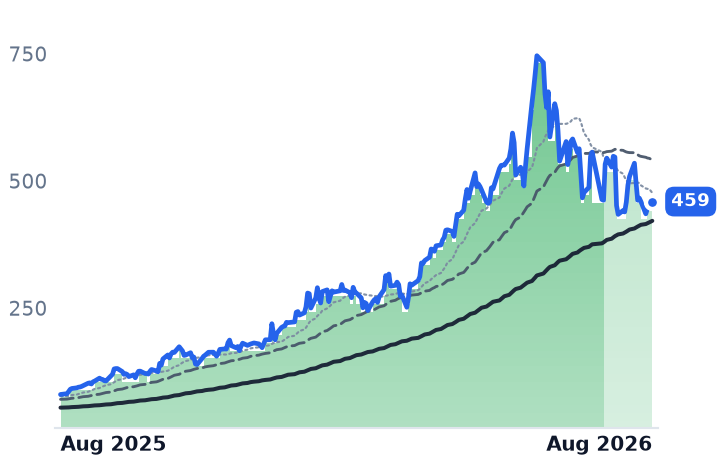
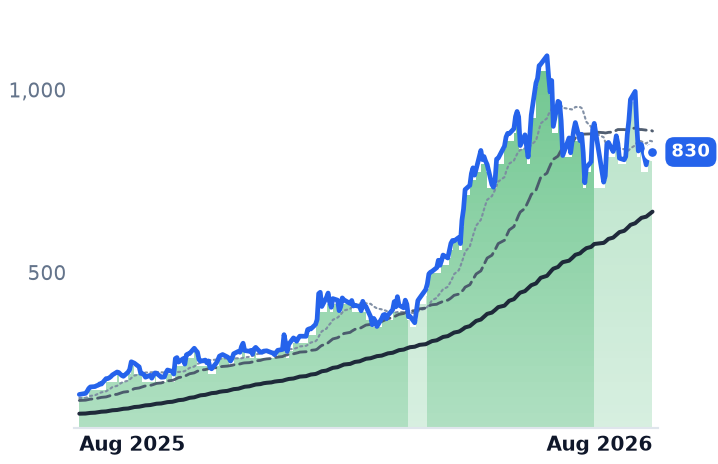
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NTAP | $36.7B | 29.1x | 20.7x | 5.3x | 4.9x | 7.5x | 6.9x | 19.1x | 5.1% |
DELL | $308.2B | 36.3x | 24.6x | 2.3x | 1.8x | 12.1x | 9.3x | 22.2x | 3.1% |
HPE | $73.1B | 50.7x | 16.1x | 1.9x | 1.6x | 5.7x | 4.9x | 22.2x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
WDC | $166.1B | 25.6x | 48.3x | 14.1x | 12.9x | 31.1x | 28.4x | 31.1x | 1.7% |
STX | $178.4B | 73.9x | 53.5x | 16.2x | 14.8x | 39.0x | 35.7x | 53.6x | 1.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NTAP | Revenue | +4.3% | +10.1% | +5.7% |
| EPS | +10.4% | +13.0% | +11.2% | |
DELL | Revenue | +16.2% | +55.3% | +14.9% |
| EPS | +27.3% | +89.4% | +21.3% | |
HPE | Revenue | +30.5% | +11.6% | +5.8% |
| EPS | +81.3% | +18.7% | +10.1% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
WDC | Revenue | +36.9% | +37.2% | +26.5% |
| EPS | +106.2% | +72.8% | +48.0% | |
STX | Revenue | +32.7% | +35.9% | +24.9% |
| EPS | +86.9% | +77.9% | +48.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
NetApp's fourth quarter was received as evidence that a storage-array maker had become a data-infrastructure and cloud company. Its own segment table says the quarter was carried by boxes. Product revenue — arrays, not licenses or cloud services — was 49.6% of the total in the three months reported on 28 May, up from 48.8% a year earlier, and grew 14.3% against total revenue growth of 12.5%.
That matters because of what NetApp told investors would happen next. The company guided fiscal 2027 group gross margin to 68.5–69.5%, down from 71.3% delivered in fiscal 2026 — roughly $150m of gross profit at the guided revenue range — and added to its own risk-factor list "our ability to manage our gross profit margins, including managing component costs." The segment doing the growing is the segment being taxed. NetApp reports first-quarter fiscal 2027 results after the close on 2 September.
The mix that did not move
For the full year, public cloud was 9.9% of revenue, at $688m of $6,925m, against 10.1% the year before; support was 38.1% against 38.2%; product was 46.1% against 46.3%. Public cloud gross margin genuinely improved, reaching 85.7% in the quarter from 79.3% a year earlier — but the segment threw off $156m of $1,374m in total segment gross profit, about a ninth. Stripping out Spot, the optimization business divested in March 2025, management shows cloud storage revenue of $540m, up 30%. That is a real line growing quickly inside a company where it does not yet move the average.
There is also nothing to check it against. NetApp discloses no annual recurring revenue of any kind. The nearest consumption disclosure is Keystone storage-as-a-service total contract value of $300m for the year, up 34% — a bookings figure worth roughly 4% of revenue. No capacity-shipped metric is published either, so price and volume cannot be separated from company filings. Billings grew 6.4% in the quarter against revenue up 12.5%, the usual signature of demand pulled forward.
An industry cycle, priced through
Product gross margin was 56.1% in the fourth quarter, against 55.4% a year earlier and 61.3% two years earlier. Chief financial officer Wissam Jabre told analysts on the 28 May call that product margin should trough in the July quarter and improve gradually as pricing changes flow through, tying the pressure to memory and component costs. Those costs are not NetApp's alone: NAND flash contract prices rose sharply through 2026 as memory makers moved wafer capacity toward high-bandwidth memory for artificial-intelligence accelerators.
Everpure, the all-flash array vendor formerly called Pure Storage, is the cleanest check. It reported on 26 August with revenue up 37.7% to $1.19bn, raised full-year guidance by more than $500m, burned $136m of operating cash flow on strategic NAND purchases, and said it is deliberately running near the low end of its 65–70% product gross-margin band while component costs escalate. Chief executive Charlie Giancarlo told analysts only some of the acceleration is price. IDC put first-quarter industry storage revenue at $9.2bn, up 22.7%, crediting artificial-intelligence demand, deferred refresh and component inflation at once. Dell and Hewlett Packard Enterprise shares rose more than NetApp's over the same three months, and on price to trailing gross profit Hewlett Packard Enterprise, at 5.71x, is cheaper than NetApp while Dell, at 12.06x, is dearer.
What the price has already paid for
The advance was not a grind. The shares went from $142.40 to $174.29 on 29 May, roughly 44% of the whole move's log-return in one session, and sit 9.7% below the 14 August high of $207.08. Price to trailing gross profit is 7.49x against roughly 5.3x when the uptrend began in May — about 42% of multiple expansion while gross-profit dollars grew 6.2%. Trailing earnings are capitalized at 29.1x on 5.4% annual revenue growth, and consensus fiscal 2027 earnings of $9.02 sit above the top of the company's own $8.70–9.00 guide, leaving the guided margin compression no room in estimates.
The business is genuinely better: revenue growth accelerated every quarter of fiscal 2026, non-GAAP operating margin reached 32%, all-flash revenue hit a record $1,216m, up 18%, and free cash flow funded $950m of buybacks. What the market appears to have bought, though, is a software mix shift the accounts do not show. The earnings the shares are capitalized on are hardware earnings arriving into the steepest input-cost cycle storage has seen in years, and the growth and the margin risk now sit in the same line — the diversification the cloud segment was supposed to provide is too small to hedge it.
George Kurian called fiscal 2026 "a record year for NetApp." It was, and the record was set in arrays. Whether July was the bottom of the product margin or the first leg of a longer descent is answerable on 2 September — and until then there is no recurring-revenue line to watch instead.