

Paycom and Paylocity Grow Faster Once Interest on Client Payroll Cash Is Stripped Out
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Payroll software vendors hold employers' withheld tax between collection and remittance and keep the interest. Falling yields are shrinking that line at both mid-market vendors — and both are growing faster underneath it than their headline guides suggest.
Paycom's interest on client funds was $113.0m in 2025, 5.5% of revenue, and is guided to about $105m this year even though average daily balances rose 9% to roughly $2.9bn. Paylocity's fell from about $120m to a guided $103m, which puts roughly 1.5 points of rate drag inside a 7% revenue guide; its adjusted profit excluding that interest grew 16.4% against 12.3% including it.
The two are not equally exposed: interest equals about 31% of Paylocity's operating income against roughly 12% at Paycom. What neither is being paid for is more employees — ADP's billed headcount grew 1%, and Paylocity built its year on flat client workforces.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
PAYC | Paycom Software | HR & Workforce Management | 🌱 Emerging Bull | +47.7% | +5.5% |
PCTY | Paylocity | HR & Workforce Management | 🔴 Cont. Bear | +15.5% | −11.9% |
| Compared against · context, not the story | |||||
ADP | Automatic Data Processing | HCM Software & Payroll | 🌱 Emerging Bull | +8.5% | −3.9% |
PAYX | Paychex | HCM Software & Payroll | 🔴 Cont. Bear | +9.7% | −5.4% |
WDAY | Workday | Enterprise Resource Planning | 🌱 Emerging Bull | +30.1% | −10.9% |
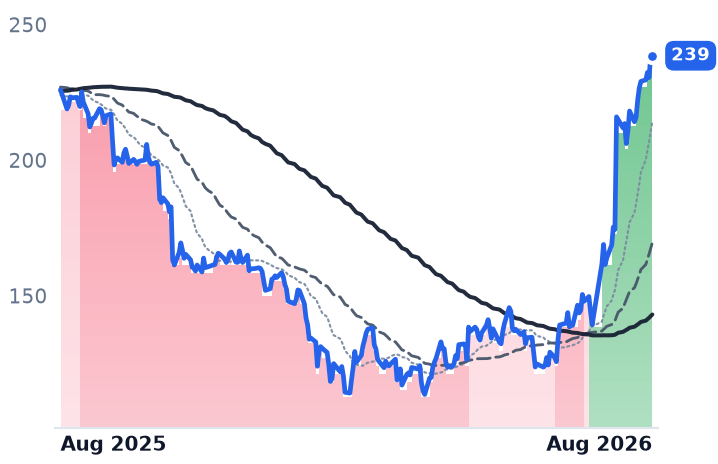
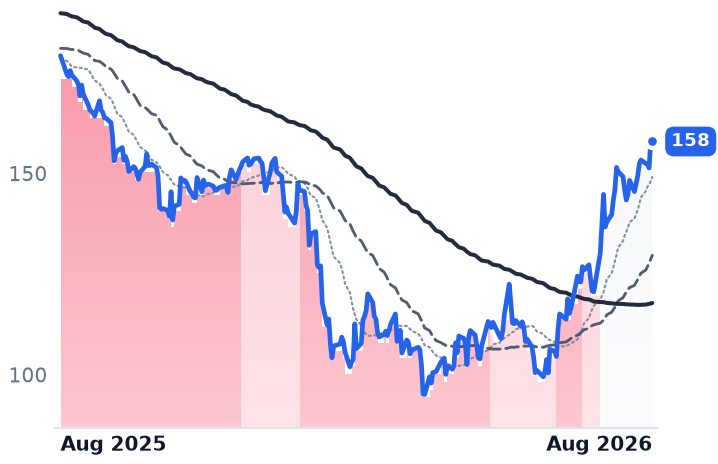
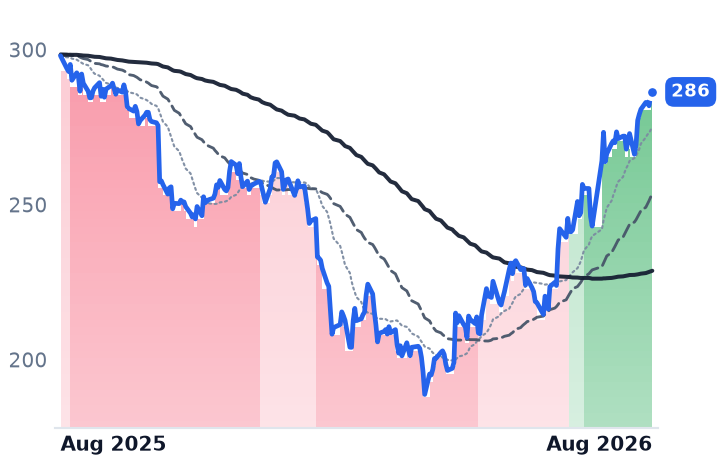
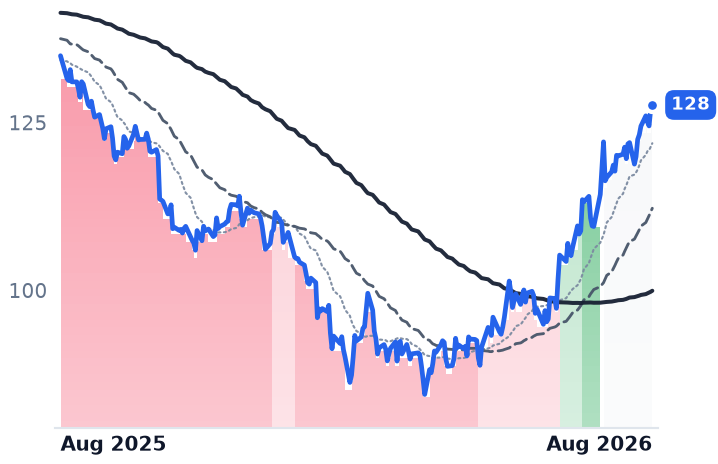
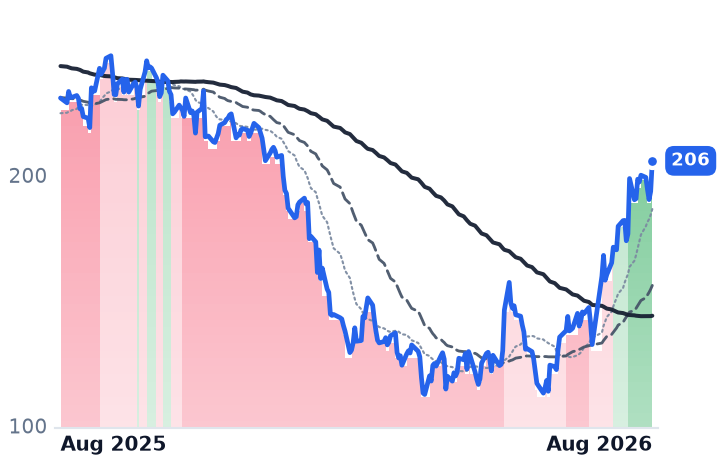
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PAYC | $10.8B | 25.3x | 19.7x | 5.0x | 4.9x | 6.3x | 6.1x | 12.8x | 7.0% |
PCTY | $8.5B | 31.6x | 17.9x | 4.8x | 4.5x | 6.9x | 6.5x | 16.6x | 5.3% |
ADP | $113.8B | 26.0x | 23.2x | 5.2x | 4.9x | 10.8x | 10.2x | 18.1x | 4.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PAYX | $45.2B | 25.9x | 21.3x | 6.9x | 6.6x | 9.3x | 8.9x | 16.1x | 5.1% |
WDAY | $50.7B | 39.3x | 18.0x | 5.0x | 4.8x | 6.3x | 6.0x | 35.3x | 5.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
PAYC | Revenue | +7.7% | +7.2% | +8.3% |
| EPS | +30.9% | +15.5% | +11.1% | |
PCTY | Revenue | +11.1% | +7.5% | +7.6% |
| EPS | +15.4% | +9.0% | +9.7% | |
ADP | Revenue | +7.0% | +5.9% | +5.7% |
| EPS | +11.0% | +10.7% | +9.2% | |
PAYX | Revenue | +16.5% | +5.5% | +5.5% |
| EPS | +10.1% | +8.6% | +7.5% | |
WDAY | Revenue | +13.4% | +11.8% | +11.0% |
| EPS | +26.5% | +18.6% | +17.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Two mid-market payroll software vendors reported within a day of each other in the first week of August, and both told investors to expect less money next year from the same source: the interest they earn on employers' cash while it sits with them. Paycom guided its client-fund interest to about $105m for 2026 against $113.0m earned in 2025. Paylocity, reporting a day earlier, put fiscal 2027 at roughly $103m against nearly $120m.
That line is where most readings of these businesses stop, because it looks like the rate trade unwinding. It isn't. Strip the interest out of both companies' guidance and the software underneath is growing faster than the reported number — which makes the shrinking interest line a headwind these two are absorbing rather than a crutch they are leaning on.
How the money sits
A payroll processor collects withholding from an employer on payday and remits it to taxing authorities when due. In between it holds the cash and keeps the yield. Paycom, the Oklahoma City vendor of a single-database human-capital platform sold to small and mid-sized US employers on a per-employee subscription, ran an average daily client balance of about $2.9bn in its second quarter, up 9%. Balances are rising; the interest is falling. The decline is yield, and Paycom's original 2026 outlook of roughly $103m was built on an assumption of two rate cuts before the company nudged it to about $105m on 5 August assuming rates hold.
Interest was 5.5% of Paycom's 2025 revenue and is about 4.8% of the 2026 guide. Back it out and the raised guide of $2.197bn–$2.212bn, a headline 7–8%, implies roughly 8.3% growth in everything else. Paylocity, the Schaumburg, Illinois vendor selling payroll and human-resources software to mid-market employers through a direct sales force, is the starker case: its fiscal 2027 revenue guide of $1.880bn–$1.895bn is about 7% growth, roughly 8.1% ex-interest. Its adjusted EBITDA excluding client-fund interest reached $534.9m against $459.6m, up 16.4%, while the all-in figure grew 12.3%.
The two are not equally levered to rates. Paylocity's interest equals about 31% of its $386.0m of operating income; at Paycom the share is roughly 12%. And the mature comparison runs the other way: at Automatic Data Processing, the $113.8bn payroll and human-resources outsourcer, interest on client funds rose 13.7% to $403.9m in the March quarter as balances grew 8.5% to $48.3bn and the average rate earned rose to 3.3%. Its laddered bond book is still rolling into higher coupons while the smaller vendors' shorter money reprices down.
The meter itself is flat
These contracts bill per employee per month, so headcount is the meter — and the meter is not moving. ADP's pays-per-control, the employees on client payrolls it bills for, grew 1% in fiscal 2026 and is guided to 0–1%. Paylocity chief financial officer Ryan Glenn told investors on the 4 August call that the company is assuming flat client workforce levels in fiscal 2027, "a slight degradation from recent trends". Paycom management described client employment growth as stable with no acceleration.
Growth is therefore coming from somewhere else. Paylocity ended the year with about 44,400 clients, up 7%, and revenue per client of roughly $37,200, up more than 5% — new logos, price and module attach, including the spend-management business it bought in Airbase. Recurring revenue accelerated to 12.4% in the fourth quarter.
Paycom's answer is its own cost line. Second-quarter revenue of $531.2m grew 9.8% while operating income of $168.5m grew 50.0%, taking margin from 23.2% to 31.7%. A 2025 data-center build now saves more than $100m a year in research spend and over $30m in third-party artificial-intelligence token fees; more than 500 roles went on 1 October 2025, concentrated in support and implementation, leaving 5,770 employees. Chief executive Chad Richison put it plainly on the 5 August call: "So our focus is product automation and that drives cost efficiencies in many areas, including labor." Diluted shares fell to 45.9m from 56.3m after $1.4bn of buybacks year to date.
What the shares have and have not earned
Paycom is up 74.4% over three months to $238.53 but only 5.7% over twelve, and a single session did the work: a 23.8% gap on 6 August, on 3.65m shares against a daily norm nearer 500,000, the day after the raise. Paylocity is up 42.4% over three months with no comparable session and remains down 12.0% on the year. ADP rose 30.3% and Paychex 33.6% over the same three months, both still lower year on year. All four were in downtrends in May; by late August Paycom and ADP had their 50-day averages above their 200-day, while Paylocity and Paychex had only flattened.
On valuation the pair sit below the incumbents. Paycom trades at 19.7 times forward earnings against 25.3 times trailing, on consensus earnings growth of 30.9% that is mostly the vanishing share count. Paylocity is the cheapest of the four at 17.9 times forward against 31.6 times trailing, but on forward earnings growth of only 9.0%. ADP is at 23.2 times forward and Paychex 21.3 times.
The verdict splits the pair. Paycom has earned the profit half of its move and none of the revenue half: growth has decelerated three years running, from 23.2% in 2023 to 8.9% in 2025, and the 2025 operating margin of 27.6% was below 2024's, so this year's surge is a recovery rather than a new peak. Its retention, at 91% annually, is the lowest of the group against Paylocity above 92% and ADP's record 92.1%. Paylocity has earned less on margin and more on the top line, but carries nearly triple Paycom's dependence on rates.
Both companies have now told investors that hiring will not help them. Both assume the Federal Reserve cuts twice. What is left is price, modules and the vendors' own payrolls — and a cost base can only be cut once.