

Manhattan Associates Booked $2.47bn of Contracted Revenue It Cannot Report Yet
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
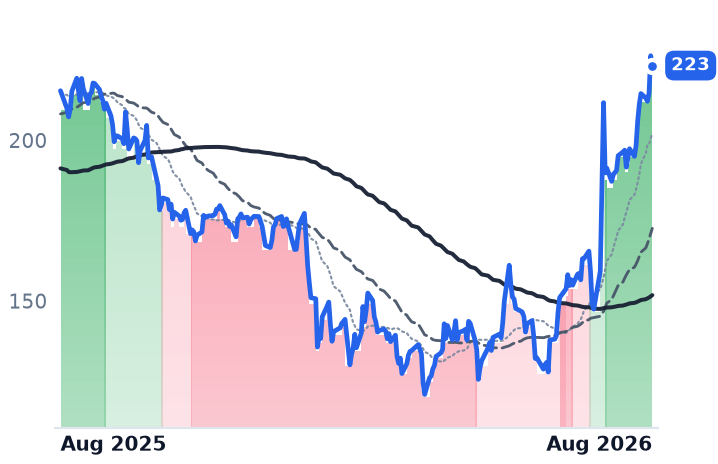
Manhattan Associates' backlog is growing more than twice as fast as its revenue, and its reported operating profit is going backwards at the same time. The Atlanta supply-chain software company has moved its warehouse and order-management customers off perpetual licenses onto cloud subscriptions, which spreads contracted money across years instead of recognizing it at signature: contracted-but-unrecognized revenue reached $2.47bn, up 23%, against June-quarter revenue of $297.8m, up 9.3%. Cloud revenue grew 26%.
Operating income fell 10.2%, carrying a restructuring charge of $8m and a heavier services mix. Investors settled the argument in two sessions: the shares now trade near 41 times this year's consensus earnings, against roughly 25 times in late February, for consensus earnings growth of about 10% this year. The meter is real. The price now assumes it converts on schedule.
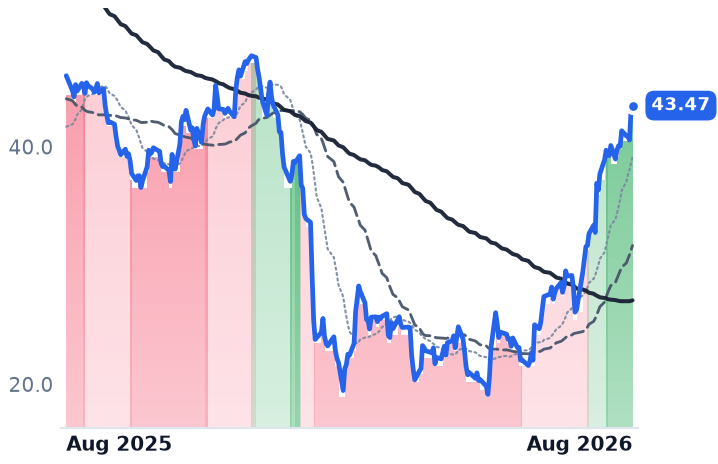
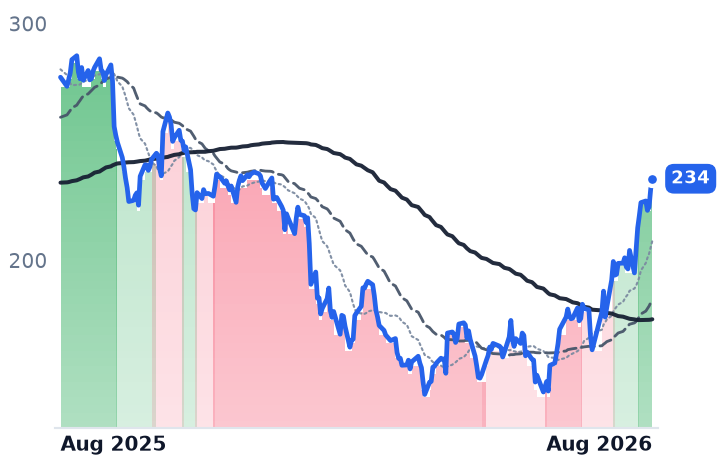
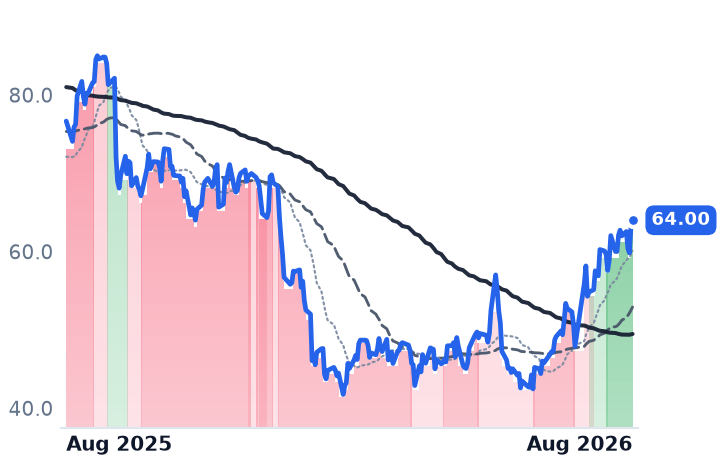
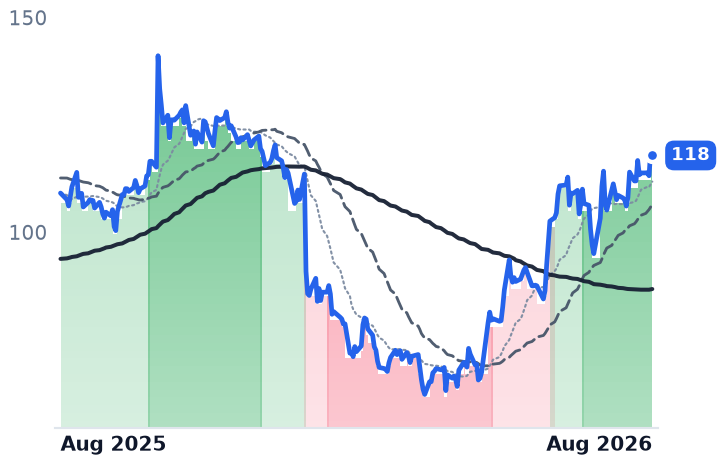
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MANH | Manhattan Associates | Industry-Specific Platforms | 🌱 Emerging Bull | +17.6% | +3.6% |
DSGX | The Descartes Systems | Industry-Specific Platforms | 🔴 Cont. Bear | +10.3% | −18.1% |
| Compared against · context, not the story | |||||
BSY | Bentley Systems, Incorporated | Software Development & Design | 🔴 Cont. Bear | +5.9% | −32.7% |
BLKB | Blackbaud | Industry-Specific Platforms | 🔴 Cont. Bear | +21.3% | −27.1% |
INTA | Intapp | Sales, Service & Customer Management | 🌱 Emerging Bull | +37.1% | −5.5% |
APPF | AppFolio | Industry-Specific Platforms | 🔴 Cont. Bear | +33.2% | −15.5% |
DOCU | DocuSign | Software Development & Design | 🔴 Cont. Bear | +17.9% | −16.5% |
AGYS | Agilysys | Industry-Specific Platforms | 🌱 Emerging Bull | +10.6% | +8.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MANH | $14.7B | 70.2x | 45.3x | 12.7x | 12.5x | 23.1x | 22.7x | 49.3x | 2.6% |
BSY | $13.0B | 43.3x | 31.8x | 7.9x | 7.7x | 9.6x | 9.3x | 27.2x | 3.8% |
BLKB | $2.4B | 16.4x | 10.3x | 2.1x | 2.1x | 3.5x | 3.5x | 10.6x | 13.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DSGX | $8.0B | 42.9x | 40.2x | 10.4x | 9.7x | 13.4x | 12.5x | 22.7x | 3.7% |
INTA | $3.4B | n/m | 26.4x | 5.6x | 5.1x | 7.3x | 6.6x | — | 4.5% |
APPF | $8.2B | 48.4x | 33.7x | 7.5x | 7.3x | 11.9x | 11.5x | 34.4x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DOCU | $14.5B | 46.5x | 16.8x | 4.3x | 4.1x | 5.4x | 5.2x | 25.1x | 8.3% |
AGYS | $3.4B | 76.6x | 47.0x | 9.9x | 9.1x | 15.7x | 14.4x | 50.1x | 2.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MANH | Revenue | +9.4% | +8.1% | +9.0% |
| EPS | +12.0% | +10.8% | +11.4% | |
BSY | Revenue | +13.6% | +10.4% | +10.2% |
| EPS | +18.6% | +12.3% | +16.3% | |
BLKB | Revenue | +4.5% | +4.7% | +4.7% |
| EPS | +18.9% | +14.3% | +14.9% | |
DSGX | Revenue | +15.0% | +13.1% | +12.8% |
| EPS | +15.8% | +25.2% | +15.6% | |
INTA | Revenue | +14.7% | +14.8% | +15.0% |
| EPS | +36.8% | +34.6% | +19.9% | |
APPF | Revenue | +18.6% | +17.1% | +16.2% |
| EPS | +32.7% | +21.4% | +22.2% | |
DOCU | Revenue | +8.4% | +9.2% | +8.0% |
| EPS | +6.9% | +22.1% | +12.8% | |
AGYS | Revenue | +16.5% | +18.2% | +17.3% |
| EPS | +26.9% | +56.8% | +27.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Manhattan Associates has spent years moving customers of its warehouse, order-management and point-of-sale software from perpetual licenses onto cloud subscriptions, and the conversion is far enough along that the company's fastest-growing number never touches the income statement. Contracted revenue not yet recognized — what the company calls remaining performance obligation — reached $2.47bn at the end of June, up 23% from a year earlier. Reported revenue grew 9.3%, to $297.8m.
That gap is arithmetic, not spin. A license sale lands largely at signature; the same customer on a subscription pays over a multi-year term, so the meter compounds while the profit-and-loss statement lags. What turns the mechanism into a story is that the market accepted the argument all at once. Manhattan's second-quarter report on 28 July beat consensus on both lines — adjusted earnings of $1.39 a share against $1.32 expected, revenue against $287.7m — and the shares gained roughly a third across the two sessions spanning it, with press coverage attributing about 27 points of that to 29 July alone. At $225.83 the stock sits at a 52-week high on about 41 times consensus 2026 earnings of $5.50, against roughly 25 times at its 27 February close of $135.43. A full year of de-rating was undone in a month, for consensus earnings growth of 10.3% this year and 11.5% next.
What the meter says
The bookings side earns its keep. Cloud revenue reached $127m, up 26%, in a third consecutive record-bookings quarter, and management raised full-year guidance to revenue of $1.160–1.166bn, cloud revenue of $505.5m and backlog of $2.62–2.68bn — 18–20% growth, which the company expects to land toward the high end. Conversions of existing on-premise customers made up more than 40% of new cloud bookings and new customers more than 25%, so the pipeline is not purely a migration of the installed base. Excluding the license runoff, revenue grew 13% rather than 9%.
The socket is contested. Manhattan sells warehouse management against Blue Yonder, SAP, Oracle and Körber, and ABI Research's ranking puts the top five vendors together at only 25–30% of that market — a fragmented field in which a stated win rate above 70% is a claim about deals seen, not share held.
What the accounts say
The same quarter that produced record backlog produced falling profit. Generally accepted accounting principles operating income dropped 10.2% to $66.2m; gross margin compressed to 53.2% from 56.8%. A restructuring charge of $8m, worth $0.11 a share, explains part of it, and management said the savings are being reinvested with no margin benefit this year. On an adjusted basis operating margin was 34.9%, and operating cash flow rose 22% to $91m. The balance sheet carries $186m of cash and no debt, with $275m of a $500m buyback authorization already spent this year. A currency tailwind of roughly one point in the first half is expected to reverse to a one-point headwind in the second.
The re-rating was not Manhattan's alone
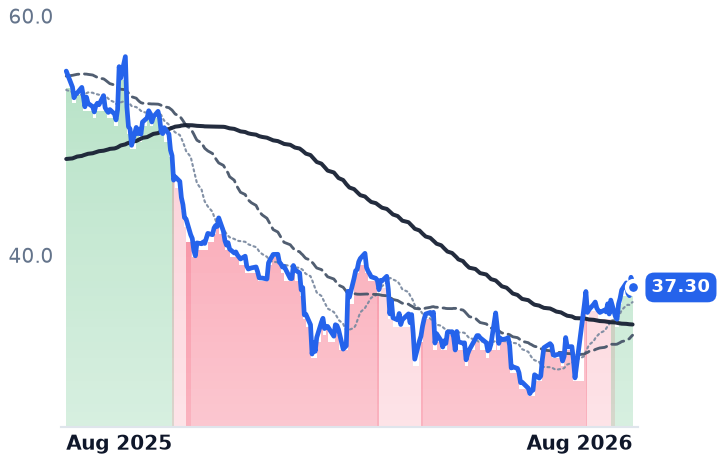
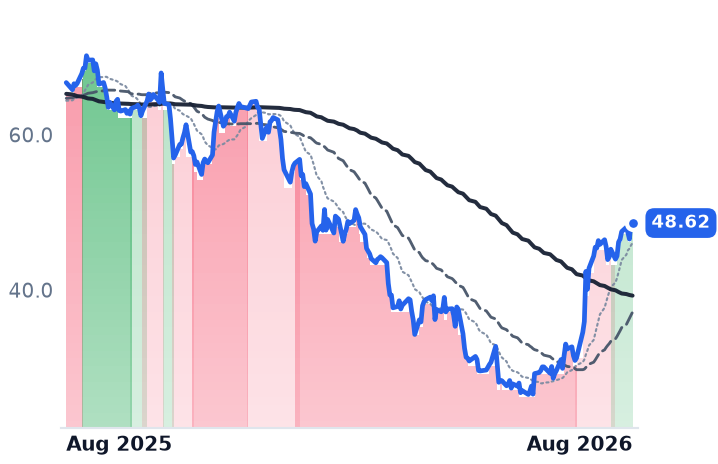
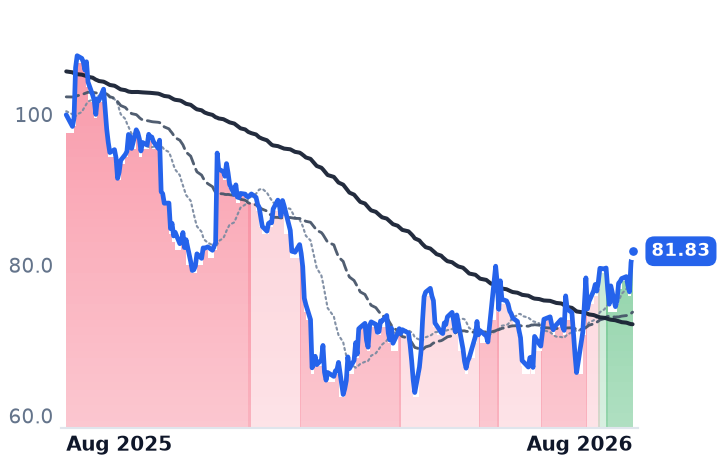
Eight specialized enterprise software names moved together after 29 July, and the ones with no transaction meter moved hardest: Intapp rose 39.7%, AppFolio 25.4%, Blackbaud 16.6% on revenue growth of 3.0%. Bentley Systems, which sells infrastructure-engineering software and grew 12.8%, rose 2.1%. Software broadly had fallen about 27% from October 2025 to mid-July on the belief that AI would erode software economics, then bounced roughly 15% from 22 July as earnings beat and Nvidia's Jensen Huang publicly dismissed the disruption thesis. Blackbaud, at 9.3 times forward earnings, rallied while promising very little: "organic total revenue growth of 4% to 6% annually," chief executive Michael Gianoni told investors on 29 July, alongside a target of double-digit annual earnings-per-share growth through 2030. Descartes Systems, whose customs-filing network bills per transaction, rose 2.8% and reports on 10 September.
The verdict
Manhattan earns the bookings half of its move: the backlog is contracted, the cloud line is compounding at 26%, and guidance went up rather than down through a soft retail spending cycle. What the business does not yet earn is the multiple. Roughly 41 times forward earnings is a growth-software price paid for around 10% consensus earnings growth, against 26.9 times for Bentley and 9.3 times for Blackbaud, and it was reached in a month in which the whole group re-rated for reasons that had nothing to do with warehouses. Backlog is a promise about future revenue; it is not evidence that reported margins stop compressing while services and reinvestment carry the mix.
Manhattan has not yet set a date for its third-quarter report. When it comes, the backlog figure will arrive in the same release as the earnings it is meant to justify — and for the first time in a year, it is the one holding up the price.