

Cloudflare Guided 14-15% of Revenue to Network Spending and Spent 7% Through June
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Cloudflare just beat the guidance that crashed its stock in May, and every growth metric improved — remaining performance obligations up 38% year on year, dollar-based net retention at 120%. The crack is in the cost line: gross profit grew more slowly than revenue, and the network spending that explains it has barely begun. Capital expenditure ran at 7% of revenue through June against a 14-15% full-year guide, which loads the entire step-up into the second half.
Akamai has already run the capex-heavy version of this experiment: spending near a third of revenue in its own June quarter, gross margin down to 55.8%. Cloudflare's shares fetch 60x trailing gross profit. The growth is earned; the re-rating is not yet.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | +14.0% | +44.4% |
| Compared against · context, not the story | |||||
AKAM | Akamai Technologies | Network & Application Delivery | 🟢 Cont. Bull | +3.6% | +41.9% |
FSLY | Fastly | Cloud Infrastructure & Platform | 🟢 Cont. Bull | +18.2% | +216.7% |
CRM | Salesforce | Customer Experience & CRM | 🔴 Cont. Bear | +33.8% | −0.1% |
CRWD | CrowdStrike | Cybersecurity & Threat Protection | ⚠️ Emerging Bear | +27.1% | −48.4% |
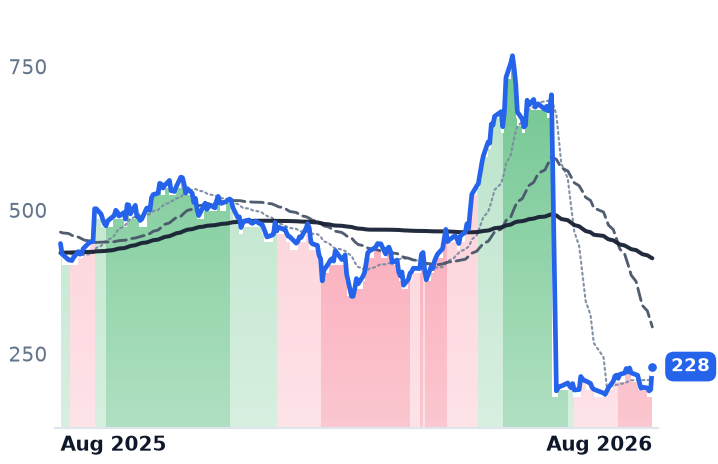
12-month price & trend
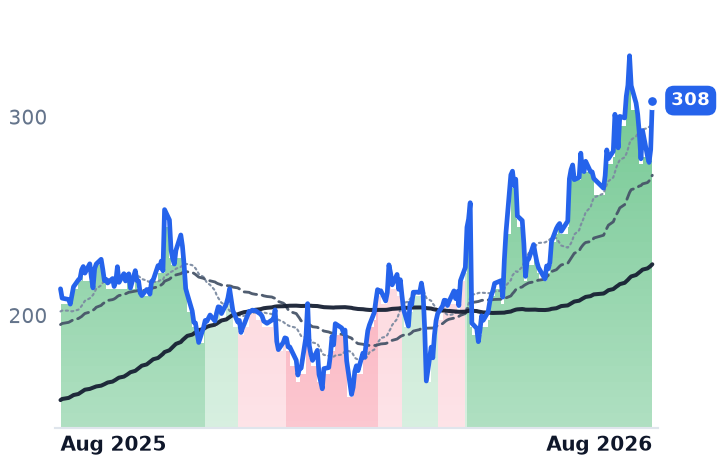
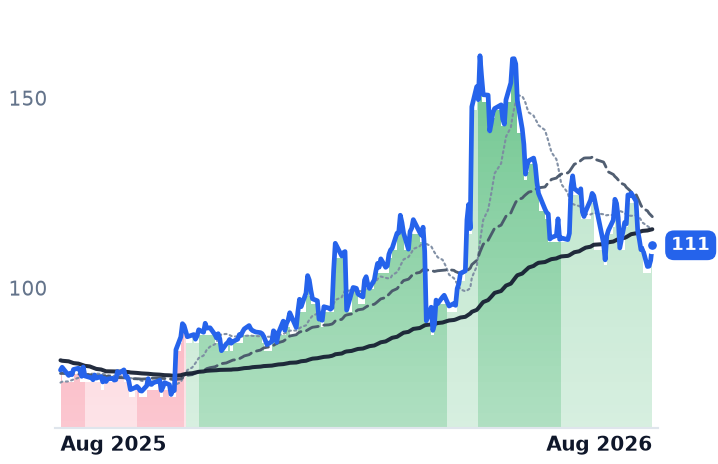
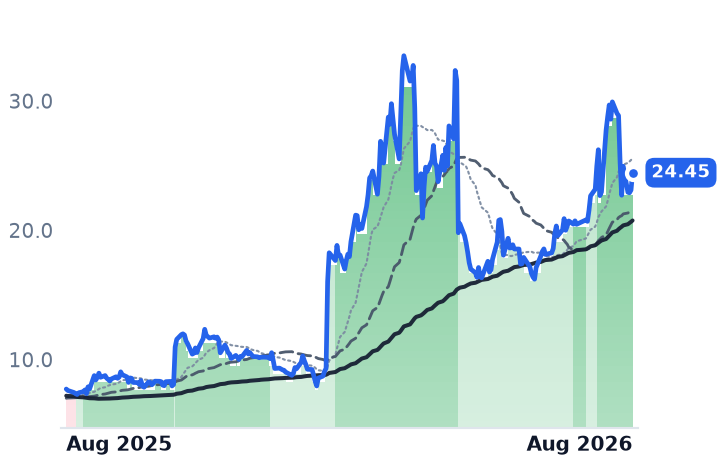
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NET | $109.4B | n/m | 244.5x | 43.6x | 38.1x | 60.0x | 52.6x | — | 0.3% |
AKAM | $15.7B | 38.0x | 16.1x | 3.6x | 3.5x | 6.4x | 6.2x | 18.3x | 4.0% |
FSLY | $3.9B | n/m | 47.5x | 5.7x | 5.3x | 9.2x | 8.6x | n/m | 1.1% |
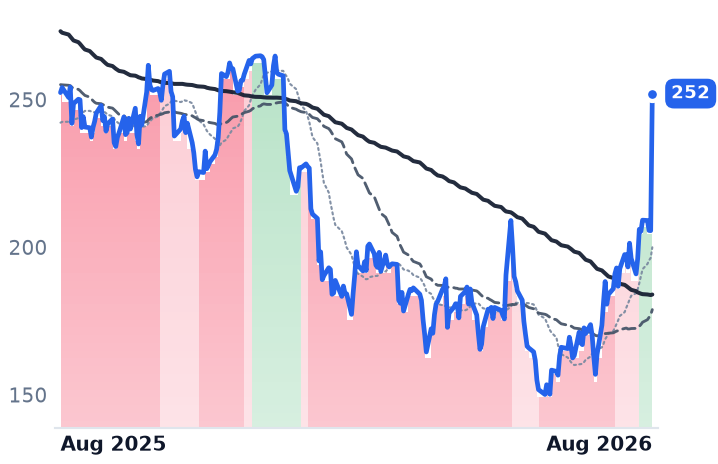
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRM | $168.4B | 18.7x | 14.5x | 3.8x | 3.7x | 5.0x | 4.7x | 12.4x | 9.0% |
CRWD | $232.1B | — | 185.2x | 43.0x | 39.0x | 57.2x | 51.9x | 667.4x | 0.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NET | Revenue | +33.7% | +28.7% | +27.5% |
| EPS | +38.0% | +32.5% | +35.3% | |
AKAM | Revenue | +7.2% | +12.8% | +10.8% |
| EPS | −4.6% | +6.1% | +13.9% | |
FSLY | Revenue | +20.9% | +12.0% | +11.2% |
| EPS | +897.9% | +11.2% | +17.0% | |
CRM | Revenue | +9.3% | +11.1% | +9.4% |
| EPS | +17.4% | +20.2% | +10.4% | |
CRWD | Revenue | +22.2% | +23.7% | +21.9% |
| EPS | −1.2% | +32.6% | +26.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Cloudflare, which runs a global network selling content delivery, bot and denial-of-service mitigation, Zero Trust access and a serverless developer platform, told investors it will spend 14-15% of revenue on that network in 2026. Through the June quarter it had spent 7%. Essentially the entire step-up falls into the two quarters ahead, and it lands in the one line of the income statement that has already turned against the company.
Gross profit grew 30.2% in the June quarter while revenue grew 35.9% — cost of revenue is outrunning sales. That gap is the argument at Cloudflare's price. The shares have re-rated steadily since early May and took another leg on 27 August inside a market-wide software repricing led by Salesforce and CrowdStrike, none of it Cloudflare news. What buyers are paying for is the proposition that Cloudflare can carry the coming wave of machine traffic at software margins. The second half is when that proposition meets the invoice.
The quarter that answered May
On 8 May the shares fell 23.6% in a single session, the largest one-day fall in the company's history, after a first-quarter beat was paired with June-quarter guidance of only $664-665m and a cut of more than 1,100 jobs, about 20% of staff, at charges now put at $165m. Revenue came in at $696.1m, roughly $31m above that guide, and the full year was raised to $2.864-2.870bn.
Underneath, the contract metrics improved across the board. Remaining performance obligations reached $2.732bn, up 38% — faster than revenue. Dollar-based net retention hit 120%, six points better than a year earlier. Customers paying more than $100,000 a year reached 4,698, up 27%, with a record 986 net additions over twelve months; large customers are now 73% of revenue. "We delivered a stellar second quarter, highlighted by revenue accelerating to $696.1 million, up 36% year-over-year, and record growth in total paying customers, large customers, and developers on our platform," co-founder and chief executive Matthew Prince told investors on 6 August.
Where the margin went
Reported gross margin was 71.76%, against 74.88% a year earlier — but up half a percentage point from March, and on the company's non-GAAP measure 73.1%, which management called the first sequential improvement in eight quarters, attributing the annual decline to a mix shift between paid and free traffic that it said was stabilising. Free cash flow was $56.4m, 8% of revenue, against a $302m gap between the GAAP operating loss and the non-GAAP operating income in the same quarter.
Management has been explicit that it will not buy its way into inference: it says it is refusing the commodity server business in favor of a network run at roughly ten times better utilisation. Akamai, the content delivery pioneer led by co-founder Tom Leighton, took the other road and has published the bill. Its June-quarter revenue grew 5.4% to $1.100bn while gross profit fell slightly and margin dropped to 55.8% from 59.1%; capital expenditure was $347m, 32% of revenue, with the full year guided near 40%, buybacks suspended and $3.5bn of zero-coupon convertibles raised against more than $2.8bn of multi-year artificial-intelligence compute commitments. Akamai told investors those contracts carry 60-70% cash gross margins and 20-30% operating margins after depreciation, with costs landing before revenue.
Fastly, the smallest of the three at a $3.9bn market value, is the counter-case: revenue up 23.3% to $183.3m, its fastest in four years, a record 63.3% gross margin, and capex guided to 10-12% of revenue. Its growth is narrow — the top ten customers supply 37% of revenue and produced 87% of sequential growth, and net retention was 117%.
What the price already assumes
Cloudflare trades at 60.0x trailing gross profit, against 50.5x when its uptrend began on 5 May and 37.4x in late February. Over six months the shares rose 79% while trailing gross profit grew 12.9%; roughly three-quarters of the move was the multiple. On management's own full-year guide of $1.25-1.26 in non-GAAP earnings per share, the forward price-to-earnings ratio is near 245x. Akamai fetches 6.44x trailing gross profit and 16.1x forward earnings; Fastly 9.24x. Over twelve months all three rose together — Fastly most of all — but since 5 May they separated: Cloudflare up 26.1%, Akamai down 5.7%, Fastly down 24.4%.
The operating business earns the first half of that. Backlog growing faster than revenue, retention climbing and record large-customer adds are not price increases dressed up; they are expansion. What nothing in the disclosure yet earns is the rest. No revenue figure or customer count exists for Workers, AI Gateway, pay-per-crawl — under which customers now return more than a billion payment-required responses to crawlers a day — or the Monetization Gateway announced on 1 July, whose agent wallets can claim a handle but cannot yet be funded. Nearly 2 million developers joined the Workers platform in the June quarter, more than in all of 2025, taking the total above 7.4 million. Adoption is documented. Monetisation is asserted.
So the margin question is live in the direction that matters, and it resolves on schedule. Third-quarter results are due 29 October, the first print in which the deferred network spending has to appear — or the guide has to come down.