

Accenture Retired Its AI Bookings Disclosure at $2.2bn. Cognizant Never Had One.
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The two largest listed systems integrators have re-rated hard on an artificial-intelligence services story that neither of them now quantifies. Accenture stopped breaking out advanced-AI bookings after one final quarter, arguing the technology is embedded in everything it sells; Cognizant has never published a figure.
What is left is proxy evidence, and it points the wrong way. Cognizant's trailing-twelve-month bookings grew 5% to $29.1bn on a book-to-bill near 1.3, but bookings signed in the June quarter fell 6% — growth carried by seven contracts worth $100m or more, meaning longer duration rather than more work. Accenture's last disclosed new bookings were $19.3bn, down 2%, with revenue growth decelerating to 5.6% and headcount up 1%.
Cognizant has a sixth straight quarter of adjusted operating-margin expansion to show for it. Accenture has disclosed nothing at all since June 18.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
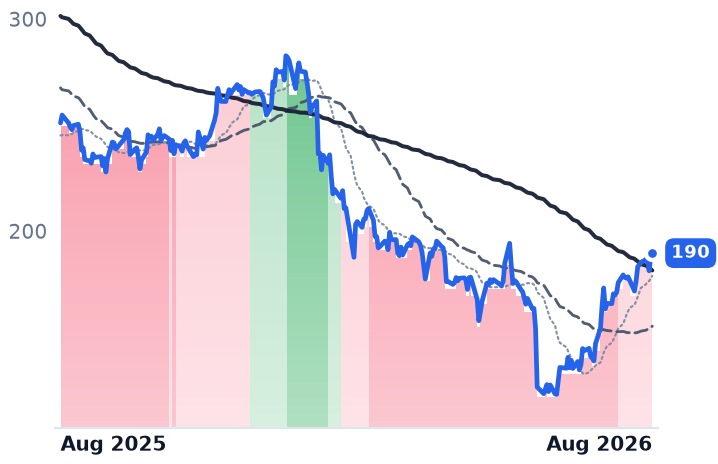
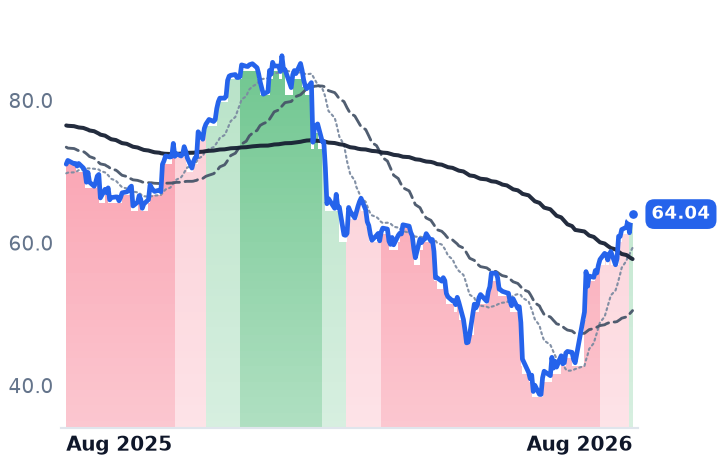
ACN | Accenture | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | +9.5% | −24.5% |
CTSH | Cognizant Technology Solutions | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | +14.4% | −9.9% |
| Compared against · context, not the story | |||||
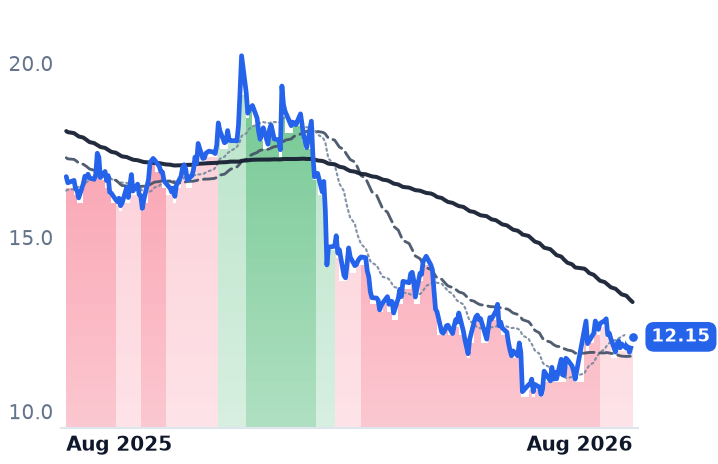
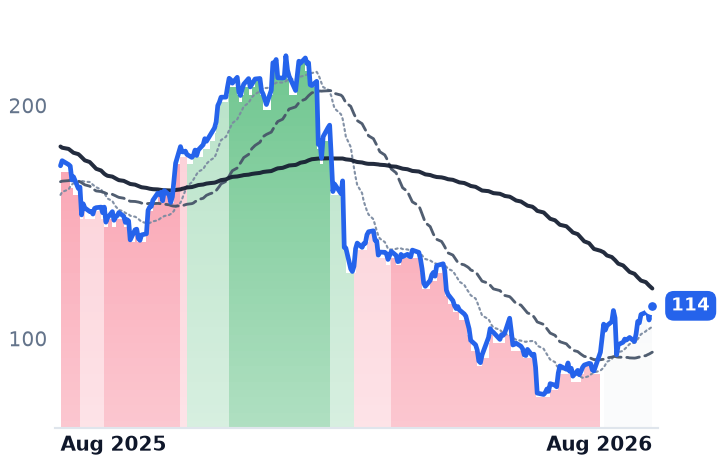
INFY | Infosys | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −3.6% | −27.5% |
EPAM | EPAM Systems | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | +7.4% | −34.5% |
WIT | Wipro | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −7.3% | −34.8% |
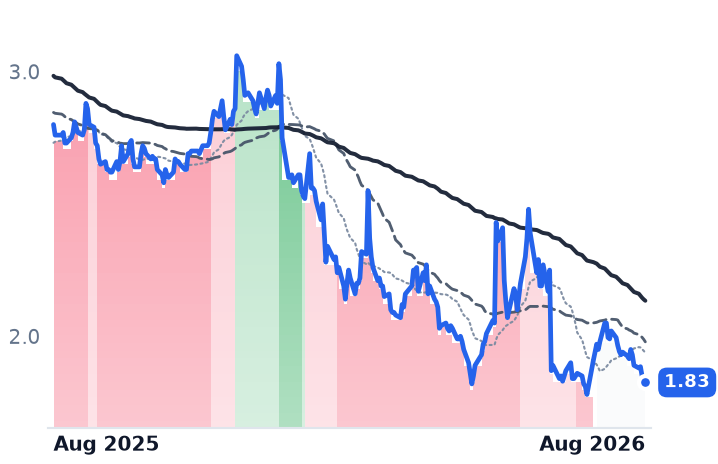
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ACN | $116.0B | 15.0x | 13.7x | 1.6x | 1.6x | 5.0x | 4.9x | 9.0x | 10.8% |
CTSH | $28.8B | 13.7x | 11.1x | 1.3x | 1.3x | 4.2x | 4.1x | 7.5x | 9.0% |
INFY | $48.4B | 14.3x | 15.0x | 2.3x | 2.4x | 7.7x | 7.9x | 9.2x | 8.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EPAM | $5.8B | 14.9x | 8.4x | 1.0x | 1.0x | 3.6x | 3.6x | 7.5x | 8.4% |
WIT | $18.9B | 14.2x | — | 1.9x | — | 6.4x | — | 9.5x | 8.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ACN | Revenue | +6.0% | +4.1% | +5.3% |
| EPS | +7.6% | +5.9% | +7.3% | |
CTSH | Revenue | +5.2% | +4.7% | +5.2% |
| EPS | +10.8% | +9.8% | +10.5% | |
INFY | Revenue | +1.6% | +4.2% | +3.6% |
| EPS | +2.3% | +4.4% | +4.4% | |
EPAM | Revenue | +3.9% | +3.5% | +5.0% |
| EPS | +15.1% | +7.3% | +7.6% | |
WIT | Revenue | +5.4% | +4.3% | +2.6% |
| EPS | +4.6% | +3.1% | +3.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Accenture agreed this week to buy two more consulting businesses: McCoy & Partners, a Dutch specialist in SAP transformation work, on August 25, and COMWARE, a Tokyo technology-services provider bringing more than 180 professionals, on August 27. Both go into Accenture Edge, the mid-market unit. The Dublin-headquartered firm, which bills large enterprises for cloud, cybersecurity, data and application-modernization programs largely by consultant time, spent the best week of its year buying billable heads.
That is worth noting because the re-rating those purchases landed inside — Accenture's shares are up 38% from their July 15 low, Cognizant's 48% — rests on a proposition neither company will now quantify. Accenture told investors that the first quarter of fiscal 2026 would be the last in which it broke out advanced-AI bookings, on the grounds that the technology is embedded in nearly everything it sells. The final figure was $2.2bn, double the prior year, atop roughly $11.5bn booked cumulatively against $4.8bn of cumulative advanced-AI revenue. Cognizant has never disclosed a generative-AI bookings number at all. The central question — is AI adding contract value faster than it removes billable hours — is no longer answerable from either firm's reporting.
The meter, not the order book
The available proxy is Cognizant's, and it splits. The Teaneck, New Jersey outsourcer, which serves financial services, healthcare, products and communications clients from an offshore-heavy delivery base, reported trailing-twelve-month bookings of $29.1bn, up 5%, a book-to-bill near 1.3 — while bookings signed in the June quarter itself fell 6%. The quarter carried seven deals with total contract value of $100m or more. Longer contracts, not more of them.
What is being sold inside those contracts is also changing shape. Fixed-price and transaction-based work has grown for three consecutive years, and some clients now ask for AI-infused rate cards that embed pre-training and inference costs. "Human effort, platforms, software, frontier services, all bundled for an output which is not effort-based, but outcome-based," chief executive Ravi Kumar S told investors on the July 29 call. He also supplied the demand check: one in four Global 2000 companies have paused AI deployments, and roughly two-thirds have not yet realized measurable productivity gains.
Infosys, the Bangalore-based offshore provider, names the mechanism outright. Management confirmed real deflation on large-deal renewals, with clients demanding productivity give-backs at renewal and increasingly mid-contract, and guided fiscal 2027 constant-currency revenue to 1.5–3% — roughly half a point organic once a 1.7% acquisition contribution is stripped out. Its AI-first revenue reached 8.2% of the total, up from 5.5% two quarters earlier. Real, scaling, and not enough: total revenue grew 2.9%. Infosys trades at 15.0x forward earnings against 14.3x trailing, the market pricing earnings down.
What Accenture has actually shown
Accenture's May-quarter revenue of $18.72bn grew 5.6%, decelerating from 8.3% in February. New bookings were $19.3bn, down 2%. Gross margin was flat near 32.8%. Headcount rose 1%, to 798,739. Fourth-quarter revenue is guided to $17.75bn–$18.4bn. The one place AI leverage shows is unit economics: Accenture's staff generated about $91,500 of revenue each over the past year, up 5.7% on near-flat headcount, against Cognizant's $60,700, up 1.8% on a workforce 12,900 larger than a year ago. Accenture bought that leverage with 11,000 job cuts under a restructuring charged at $865m, chief executive Julie Sweet saying the firm is "exiting on a compression timeline" people for whom reskilling is not a viable path.
The shares have moved on none of this. Accenture has published nothing since June 18; the trigger was the late-July rotation out of AI infrastructure names, already documented here. The sell-side arrived after: Citi lifted its Accenture target to $190 from $135 on August 24 and TD Cowen to $173 from $151 on August 26 — the first already spent at Friday's $189.61 close, the second below it. Accenture's forward multiple has expanded from roughly 10x in late July to 13.7x, against 15.0x trailing and a 10.8% free-cash-flow yield; Cognizant sits at 11.1x forward against a 14–15x reference and 13.7x trailing. Both are cheap against their own history. Neither is cheap because anything improved.
Cognizant earns part of its move: a sixth consecutive quarter of adjusted operating-margin expansion to 16.0%, full-year adjusted earnings guidance raised to $5.70–$5.82, financial-services revenue up 12%, headcount down 900 sequentially, and its trend measures crossed into positive territory on August 26. Accenture earns almost none of it, because it has said nothing. That the offshore ADRs sat out — Infosys up 10%, Wipro flat — argues this is a re-rating of two US-listed names rather than an industry demand recovery.
Accenture's fiscal year closed August 31. The fourth-quarter print lands in late September, date not yet confirmed; last year's equivalent came on September 25. It will be the firm's first word in three months, and the first full-year bookings number with no AI line in it to check.