

Manhattan Associates Booked $2.47bn of Contracted Revenue It Cannot Report Yet
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
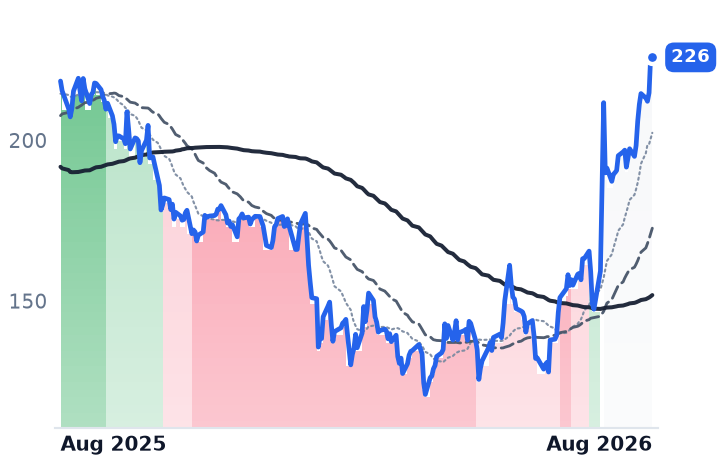
Manhattan Associates' backlog is growing more than twice as fast as its revenue, and its reported operating profit is going backwards at the same time. The Atlanta supply-chain software company has moved its warehouse and order-management customers off perpetual licenses onto cloud subscriptions, which spreads contracted money across years instead of recognizing it at signature: contracted-but-unrecognized revenue reached $2.47bn, up 23%, against June-quarter revenue of $297.8m, up 9.3%. Cloud revenue grew 26%.
Operating income fell 10.2%, carrying a restructuring charge of $8m and a heavier services mix. Investors settled the argument in two sessions: the shares now trade near 41 times this year's consensus earnings, against roughly 25 times in late February, for consensus earnings growth of about 10% this year. The meter is real. The price now assumes it converts on schedule.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MANH | Manhattan Associates | Specialized Enterprise Solutions | 🔴 Cont. Bear | +6.7% | +3.4% |
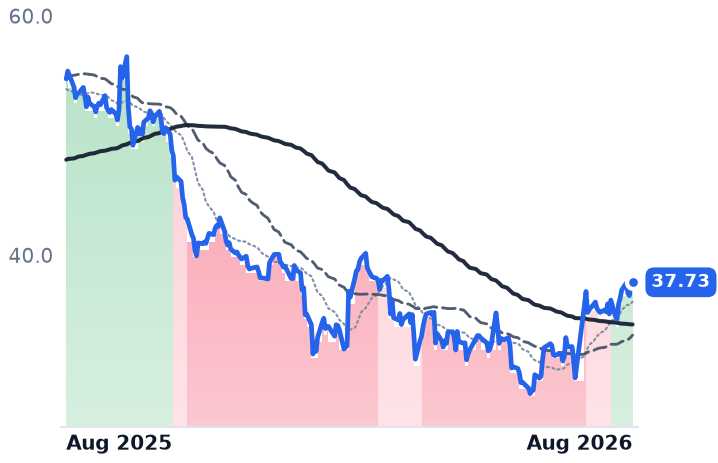
DSGX | The Descartes Systems | Specialized Enterprise Solutions | 🔴 Cont. Bear | +2.8% | −19.5% |
| Compared against · context, not the story | |||||
BSY | Bentley Systems, Incorporated | Specialized Enterprise Solutions | 🔴 Cont. Bear | +2.1% | −31.1% |
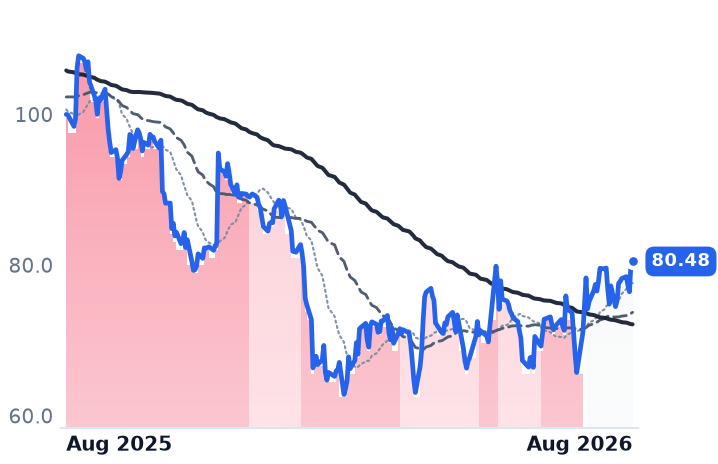
BLKB | Blackbaud | Specialized Enterprise Solutions | 🔴 Cont. Bear | +16.6% | −25.3% |
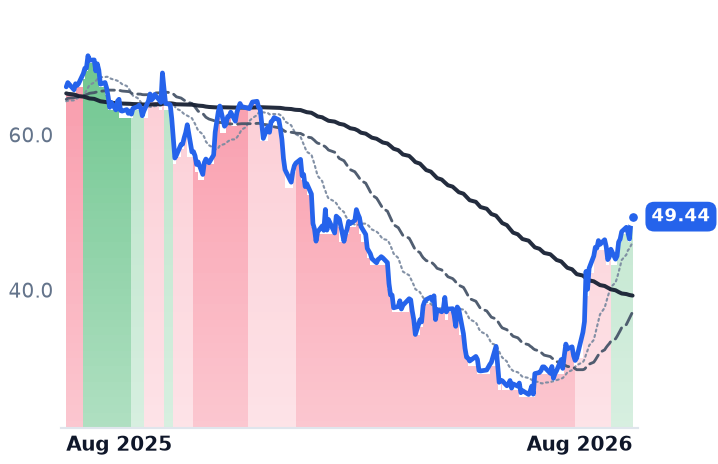
INTA | Intapp | Specialized Enterprise Solutions | 🔴 Cont. Bear | +39.7% | −5.0% |
APPF | AppFolio | Specialized Enterprise Solutions | 🔴 Cont. Bear | +25.4% | −15.1% |
DOCU | DocuSign | Specialized Enterprise Solutions | 🔴 Cont. Bear | +11.7% | −14.0% |
AGYS | Agilysys | Specialized Enterprise Solutions | 🌱 Emerging Bull | +5.2% | +10.2% |
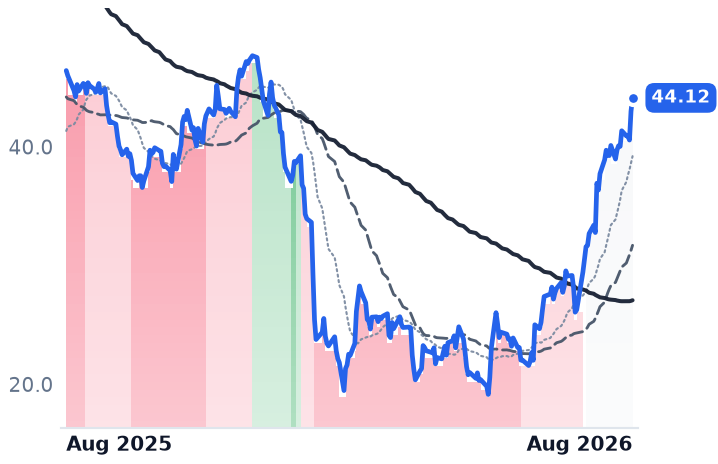
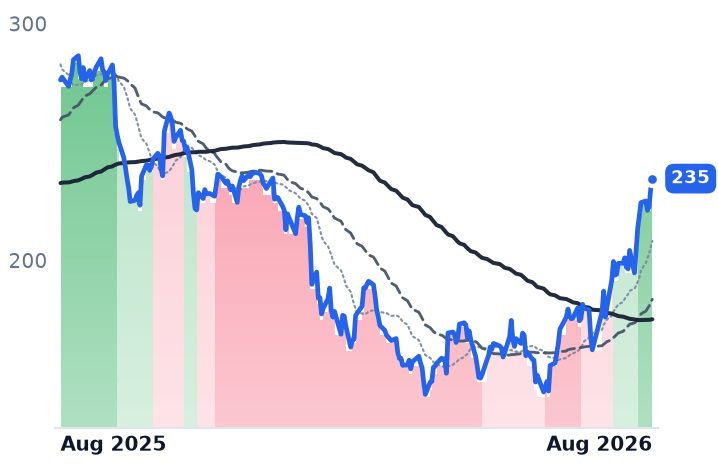
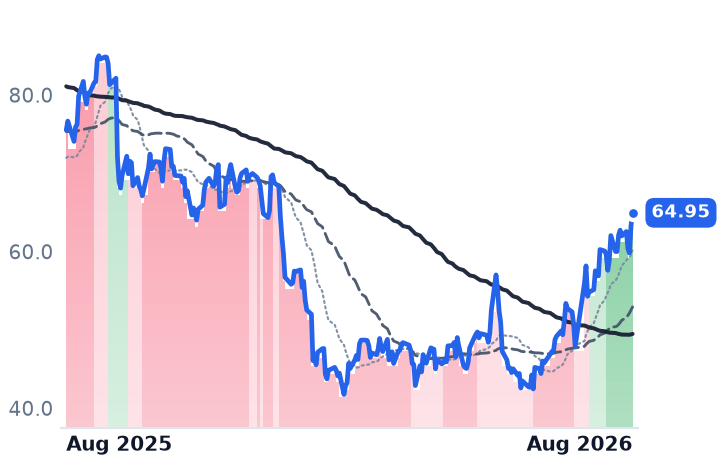
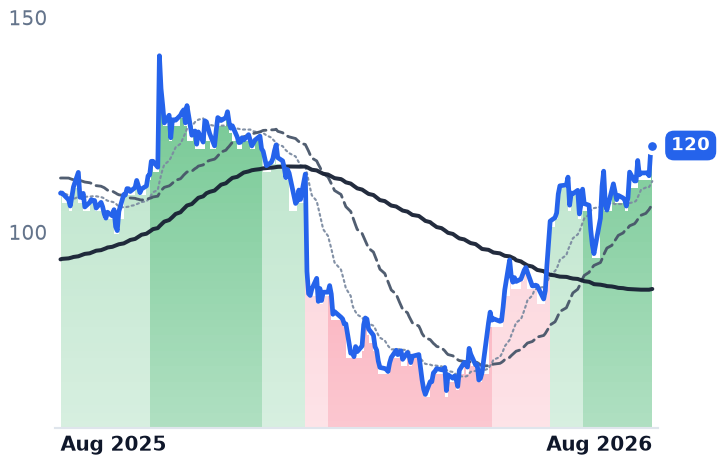
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MANH | $13.1B | 63.8x | 40.9x | 11.6x | 11.3x | 21.3x | 20.6x | 44.7x | 3.0% |
BSY | $11.0B | 40.9x | 26.9x | 6.9x | 6.5x | 8.4x | 7.9x | 24.1x | 4.5% |
BLKB | $2.2B | 15.0x | 9.3x | 1.9x | 1.9x | 3.2x | 3.2x | 10.4x | 12.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DSGX | $6.9B | 39.3x | 34.8x | 9.1x | 8.5x | 12.6x | 11.8x | 20.3x | 4.1% |
INTA | $1.6B | n/m | 17.0x | 2.9x | 2.8x | 3.9x | 3.7x | n/m | 7.5% |
APPF | $7.7B | 48.8x | 31.2x | 7.4x | 6.8x | 11.7x | 10.9x | 36.2x | 3.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DOCU | $11.5B | 38.4x | 13.3x | 3.5x | 3.3x | 4.4x | 4.1x | 17.2x | 9.7% |
AGYS | $1.9B | 61.9x | 31.2x | 6.1x | 5.2x | 10.0x | 8.6x | 37.4x | 3.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MANH | Revenue | +8.2% | +8.5% | +8.9% |
| EPS | +10.3% | +11.5% | +15.7% | |
BSY | Revenue | +13.6% | +10.4% | +10.1% |
| EPS | +18.1% | +12.1% | +16.1% | |
BLKB | Revenue | +4.5% | +4.6% | +3.2% |
| EPS | +18.8% | +13.8% | −37.2% | |
DSGX | Revenue | +15.0% | +10.8% | +11.3% |
| EPS | +16.1% | +24.5% | +16.0% | |
INTA | Revenue | +14.7% | +14.1% | +14.6% |
| EPS | +36.9% | +25.7% | +26.0% | |
APPF | Revenue | +18.5% | +17.3% | +17.8% |
| EPS | +33.8% | +22.1% | +24.5% | |
DOCU | Revenue | +8.4% | +8.9% | +7.6% |
| EPS | +6.9% | +19.5% | +12.6% | |
AGYS | Revenue | +16.5% | +14.4% | +15.3% |
| EPS | +26.9% | +31.0% | +27.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Manhattan Associates has spent years moving customers of its warehouse, order-management and point-of-sale software from perpetual licenses onto cloud subscriptions, and the conversion is far enough along that the company's fastest-growing number never touches the income statement. Contracted revenue not yet recognized — what the company calls remaining performance obligation — reached $2.47bn at the end of June, up 23% from a year earlier. Reported revenue grew 9.3%, to $297.8m.
That gap is arithmetic, not spin. A license sale lands largely at signature; the same customer on a subscription pays over a multi-year term, so the meter compounds while the profit-and-loss statement lags. What turns the mechanism into a story is that the market accepted the argument all at once. Manhattan's second-quarter report on 28 July beat consensus on both lines — adjusted earnings of $1.39 a share against $1.32 expected, revenue against $287.7m — and the shares gained roughly a third across the two sessions spanning it, with press coverage attributing about 27 points of that to 29 July alone. At $225.83 the stock sits at a 52-week high on about 41 times consensus 2026 earnings of $5.50, against roughly 25 times at its 27 February close of $135.43. A full year of de-rating was undone in a month, for consensus earnings growth of 10.3% this year and 11.5% next.
What the meter says
The bookings side earns its keep. Cloud revenue reached $127m, up 26%, in a third consecutive record-bookings quarter, and management raised full-year guidance to revenue of $1.160–1.166bn, cloud revenue of $505.5m and backlog of $2.62–2.68bn — 18–20% growth, which the company expects to land toward the high end. Conversions of existing on-premise customers made up more than 40% of new cloud bookings and new customers more than 25%, so the pipeline is not purely a migration of the installed base. Excluding the license runoff, revenue grew 13% rather than 9%.
The socket is contested. Manhattan sells warehouse management against Blue Yonder, SAP, Oracle and Körber, and ABI Research's ranking puts the top five vendors together at only 25–30% of that market — a fragmented field in which a stated win rate above 70% is a claim about deals seen, not share held.
What the accounts say
The same quarter that produced record backlog produced falling profit. Generally accepted accounting principles operating income dropped 10.2% to $66.2m; gross margin compressed to 53.2% from 56.8%. A restructuring charge of $8m, worth $0.11 a share, explains part of it, and management said the savings are being reinvested with no margin benefit this year. On an adjusted basis operating margin was 34.9%, and operating cash flow rose 22% to $91m. The balance sheet carries $186m of cash and no debt, with $275m of a $500m buyback authorization already spent this year. A currency tailwind of roughly one point in the first half is expected to reverse to a one-point headwind in the second.
The re-rating was not Manhattan's alone
Eight specialized enterprise software names moved together after 29 July, and the ones with no transaction meter moved hardest: Intapp rose 39.7%, AppFolio 25.4%, Blackbaud 16.6% on revenue growth of 3.0%. Bentley Systems, which sells infrastructure-engineering software and grew 12.8%, rose 2.1%. Software broadly had fallen about 27% from October 2025 to mid-July on the belief that AI would erode software economics, then bounced roughly 15% from 22 July as earnings beat and Nvidia's Jensen Huang publicly dismissed the disruption thesis. Blackbaud, at 9.3 times forward earnings, rallied while promising very little: "organic total revenue growth of 4% to 6% annually," chief executive Michael Gianoni told investors on 29 July, alongside a target of double-digit annual earnings-per-share growth through 2030. Descartes Systems, whose customs-filing network bills per transaction, rose 2.8% and reports on 10 September.
The verdict
Manhattan earns the bookings half of its move: the backlog is contracted, the cloud line is compounding at 26%, and guidance went up rather than down through a soft retail spending cycle. What the business does not yet earn is the multiple. Roughly 41 times forward earnings is a growth-software price paid for around 10% consensus earnings growth, against 26.9 times for Bentley and 9.3 times for Blackbaud, and it was reached in a month in which the whole group re-rated for reasons that had nothing to do with warehouses. Backlog is a promise about future revenue; it is not evidence that reported margins stop compressing while services and reinvestment carry the mix.
Manhattan has not yet set a date for its third-quarter report. When it comes, the backlog figure will arrive in the same release as the earnings it is meant to justify — and for the first time in a year, it is the one holding up the price.