

Atlassian Bundles Rovo Free, Then Sells the Tier Upgrade Its Credit Caps Force
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Atlassian's answer to the question hanging over per-seat software — whether AI agents eat the seats you bill for — is to give the AI away and charge for the plan above. Rovo carries no separate line item, no disclosed revenue, and as of May 2026 no billing for usage over the included credit allowance; the monetization is edition upgrade.
The underlying year was strong: fiscal 2026 revenue of $6.57bn grew 26%, cloud accelerated to 31% in the June quarter, and gross margin expanded 381 basis points to 86.9% while ServiceNow's and Elastic's compressed. But fiscal 2027 is guided to roughly 13% revenue growth with gross margin down to 84.5% on Rovo hosting costs, and consensus earnings for that year are flat. The shares now fetch nearly nine times trailing gross profit against about four in late February.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
TEAM | Atlassian | Developer Tools & DevOps | 🔴 Cont. Bear | +85.0% | +9.1% |
| Compared against · context, not the story | |||||
MNDY | monday.com | Other | 🌱 Emerging Bull | +12.1% | −46.6% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +31.8% | +1.4% |
CRM | Salesforce | Customer Experience & CRM | 🔴 Cont. Bear | +37.7% | +2.8% |
NOW | ServiceNow | Specialized Enterprise Solutions | 🌱 Emerging Bull | +24.7% | −22.3% |
ESTC | Elastic | Data & Analytics Platforms | 🌱 Emerging Bull | +53.7% | +12.8% |
GTLB | GitLab | Developer Tools & DevOps | 🌱 Emerging Bull | +33.1% | −7.6% |
ASAN | Asana | Other | 🌱 Emerging Bull | +21.3% | −29.1% |
WDAY | Workday | Enterprise Resource Planning | 🌱 Emerging Bull | +22.5% | −10.0% |
FIG | Figma | Design & Content Creation | 🔴 Cont. Bear | +17.0% | −59.3% |
ADBE | Adobe | Design & Content Creation | 🔴 Cont. Bear | +11.1% | −17.3% |
SNOW | Snowflake | Data & Analytics Platforms | 🌱 Emerging Bull | +17.0% | +37.3% |
DDOG | Datadog | Data & Analytics Platforms | 🌱 Emerging Bull | −9.6% | +69.4% |
TWLO | Twilio | Communications & Messaging Platforms | 🟢 Cont. Bull | +27.6% | +125.7% |
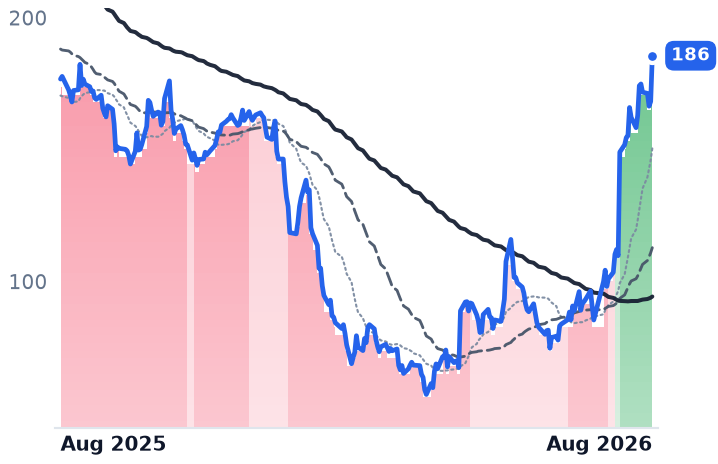
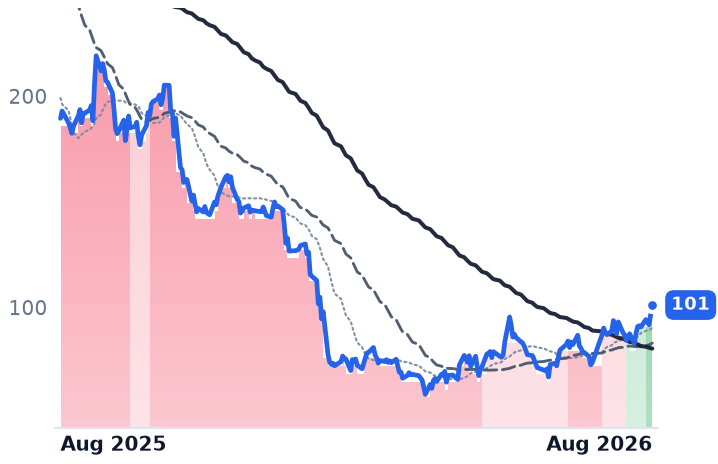
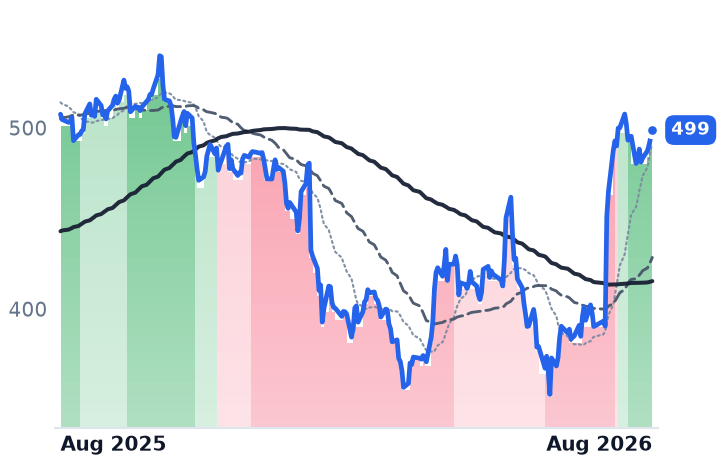
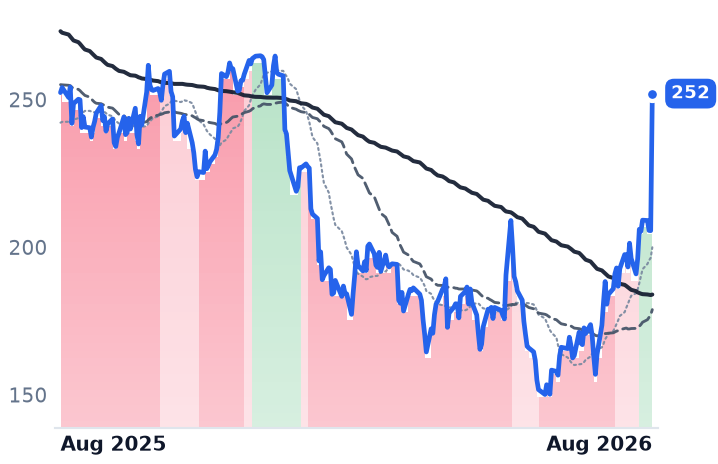
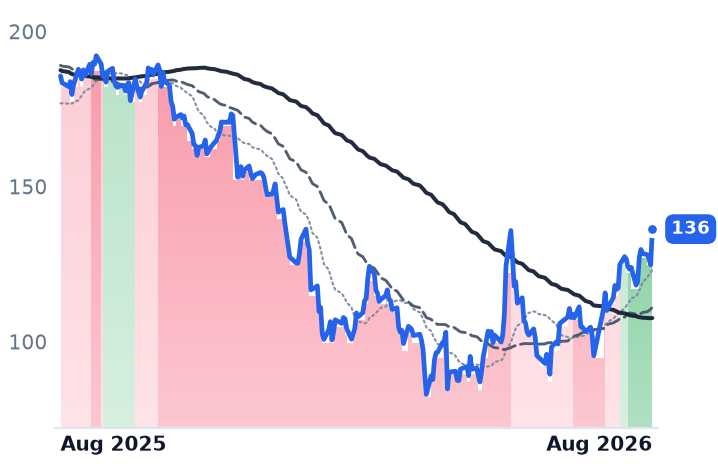
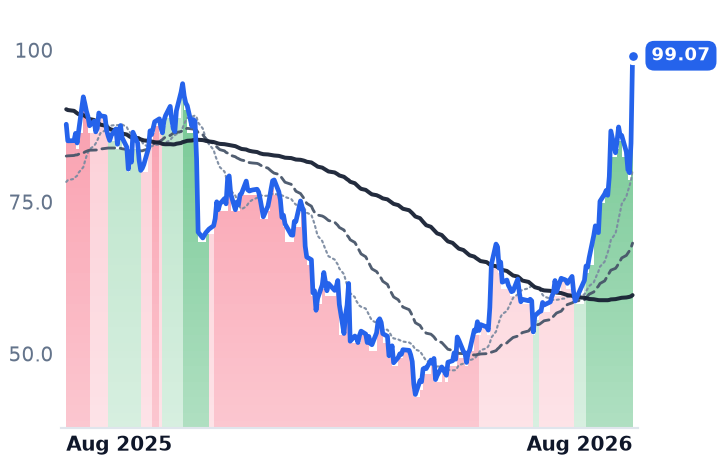
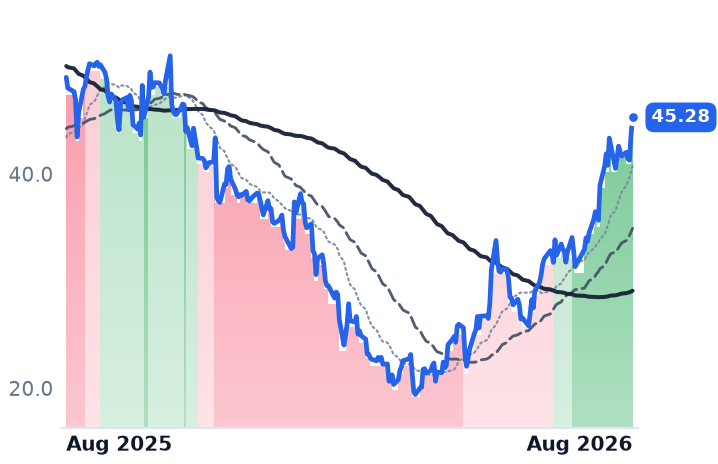
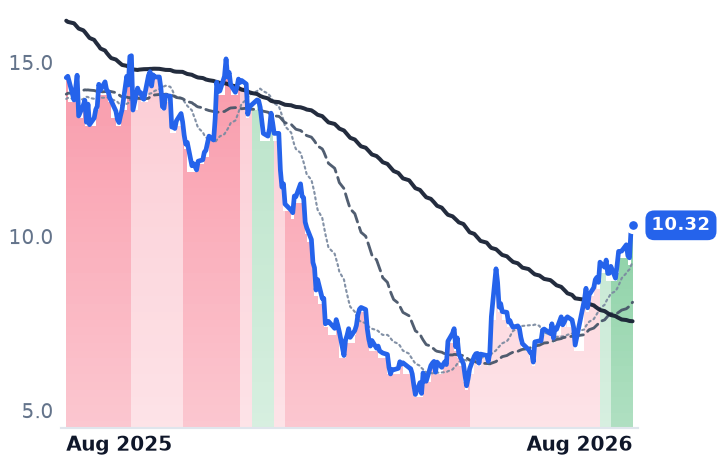
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TEAM | $50.0B | n/m | 34.6x | 7.6x | 6.7x | 9.0x | 7.9x | 331.1x | 2.6% |
MNDY | $3.8B | 38.0x | 16.6x | 2.8x | 2.6x | 3.2x | 2.9x | 34.1x | 7.8% |
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRM | $168.4B | 18.7x | 14.5x | 3.8x | 3.7x | 5.0x | 4.7x | 12.4x | 9.0% |
NOW | $132.8B | 79.8x | 31.6x | 9.0x | 8.2x | 12.1x | 11.0x | 39.8x | 3.4% |
ESTC | $10.3B | 27.5x | 30.7x | 5.7x | 5.2x | 7.6x | 6.9x | 158.5x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GTLB | $7.0B | n/m | 51.3x | 7.0x | 6.3x | 8.1x | 7.3x | n/m | 3.7% |
ASAN | $2.3B | n/m | 25.7x | 2.8x | 2.6x | 3.2x | 3.0x | n/m | 4.9% |
WDAY | $50.7B | 39.3x | 18.0x | 5.0x | 4.8x | 6.3x | 6.0x | 35.3x | 5.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FIG | $14.9B | n/m | 106.9x | 11.6x | 10.2x | 14.7x | 12.8x | n/m | 1.5% |
ADBE | $109.4B | 15.7x | 11.3x | 4.3x | 4.1x | 4.9x | 4.6x | 11.2x | 9.7% |
SNOW | $114.0B | n/m | 170.0x | 22.7x | 18.7x | 33.7x | 27.8x | n/m | 1.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DDOG | $86.5B | 488.6x | 96.0x | 21.8x | 19.4x | 27.4x | 24.3x | 331.7x | 1.3% |
TWLO | $36.6B | 32.1x | 40.7x | 6.6x | 6.1x | 13.5x | 12.6x | 100.6x | 3.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TEAM | Revenue | +24.7% | +15.4% | +14.7% |
| EPS | +55.5% | −0.1% | +21.6% | |
MNDY | Revenue | +19.8% | +15.2% | +14.9% |
| EPS | +27.8% | +22.3% | +19.1% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% | |
CRM | Revenue | +9.3% | +11.1% | +9.4% |
| EPS | +17.4% | +20.2% | +10.4% | |
NOW | Revenue | +22.4% | +18.7% | +18.6% |
| EPS | +17.1% | +23.2% | +21.4% | |
ESTC | Revenue | +17.6% | +15.0% | +14.5% |
| EPS | +30.3% | +28.2% | +18.8% | |
GTLB | Revenue | +25.6% | +17.8% | +15.3% |
| EPS | +40.9% | −8.9% | +25.2% | |
ASAN | Revenue | +9.2% | +8.9% | +7.9% |
| EPS | −272.8% | +45.4% | +26.1% | |
WDAY | Revenue | +13.4% | +11.8% | +11.0% |
| EPS | +26.5% | +18.6% | +17.3% | |
FIG | Revenue | +40.5% | +23.8% | +24.1% |
| EPS | −24.4% | +26.7% | +34.5% | |
ADBE | Revenue | +12.0% | +9.1% | +8.8% |
| EPS | +17.2% | +12.7% | +14.2% | |
SNOW | Revenue | +29.4% | +31.1% | +26.0% |
| EPS | +72.3% | +59.6% | +42.0% | |
DDOG | Revenue | +31.7% | +22.3% | +22.9% |
| EPS | +25.3% | +17.0% | +22.2% | |
TWLO | Revenue | +19.4% | +11.7% | +10.6% |
| EPS | +23.5% | +14.5% | +14.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Atlassian's artificial-intelligence assistant does not have a price. Rovo Search, Chat and Agents are bundled into every paid Jira, Confluence and Jira Service Management subscription, and each licensed seat earns a monthly pool of credits set by plan tier — 25 on Standard, 70 on Premium and 150 on Enterprise, with a Rovo chat or agent request costing ten. As of May 2026 the company was not billing anything for usage above that allowance, and has promised at least 90 days' notice and an explicit customer opt-in before it does.
That makes Atlassian — the Sydney-founded vendor of Jira project tracking, Confluence knowledge pages and Jira Service Management desks, sold by the seat to more than 350,000 customers — the clearest test of the question hanging over all per-seat software: what happens to a seat meter when the software starts doing the work the seat was hired for. Its own risk register names the exposure. Its answer is not a meter but a ladder.
The upgrade is the product
Chief executive Mike Cannon-Brookes named the mechanism on the August 6 call: "the Teamwork Collection with approximately 10x as many Rovo credits included is a great motivator, inducement for upgrade in terms of hitting those limits." Customers on that bundle carry four to five times more paid seats per instance than stand-alone Jira or Confluence accounts. One product, Rovo Dev Standard, is priced outright at $20 per user per month; no revenue or customer figure has been attached to it.
What Atlassian publishes instead is adoption: Rovo in use at over 80% of the Fortune 500, Rovo-assisted actions up 50% sequentially, adopters growing annual recurring revenue more than twice as fast as non-adopters. It publishes no absolute paid-seat count and no net expansion rate. monday.com, which sells per-seat work management to overlapping buyers, discloses that its AI revenue doubled sequentially to roughly 1% of recurring revenue and 17% of net new, and that net dollar retention was 109%. An industry report from May 2026 recorded Atlassian's first-ever decline in enterprise seat counts; management's June-quarter language of broad-based seat expansion contradicts it, and no outside reader can adjudicate, because the number does not exist in the disclosure.
A very good year, guided in half
The business momentum is real. Quarterly revenue growth accelerated through fiscal 2026 to 27.6% in the June quarter, cloud grew 31% and remaining performance obligations rose 44% to $4.82bn. Operating income swung to $211.7m from a $28.5m loss. Most striking, gross margin expanded 381 basis points to 86.9% — where ServiceNow's fell 680 basis points to 70.7% and Elastic's slipped to 74.5%. Inference has not reached Atlassian's cost of revenue.
Next year it does. Fiscal 2027 is guided to about 13% revenue growth, recurring-revenue growth of 18% against 23%, and gross margin down to 84.5% explicitly on Rovo usage and hosting. Data Center revenue is guided to fall 17%, the reversal of a pull-forward Atlassian created itself when it announced in September 2025 that most Data Center products end in March 2029.
What the price now assumes
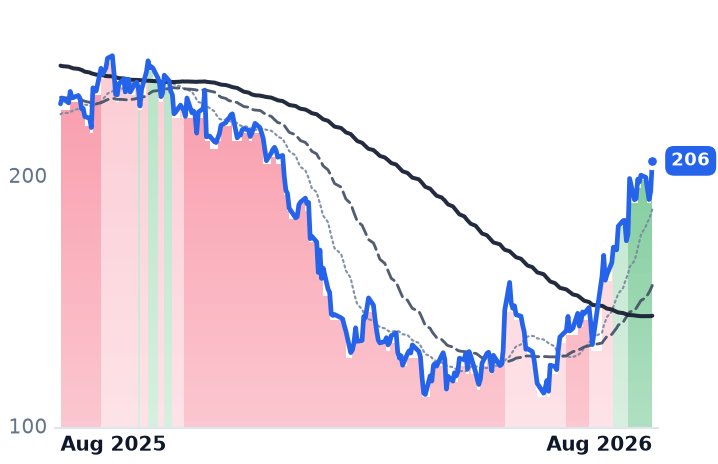
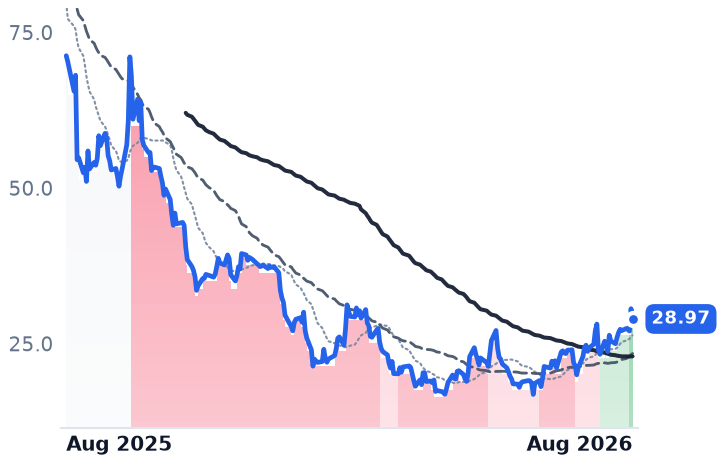
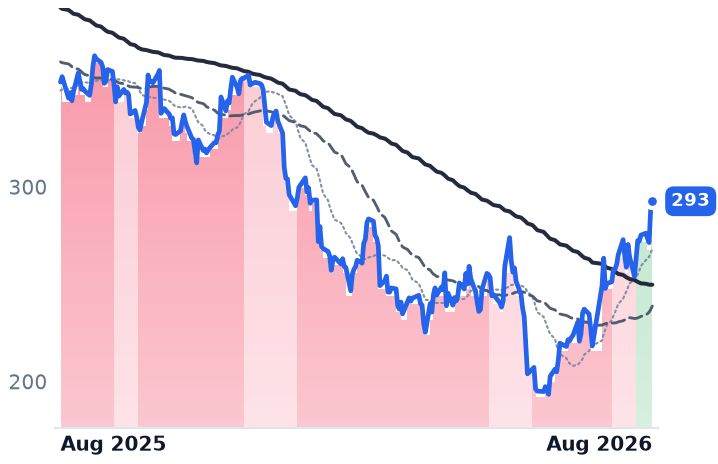
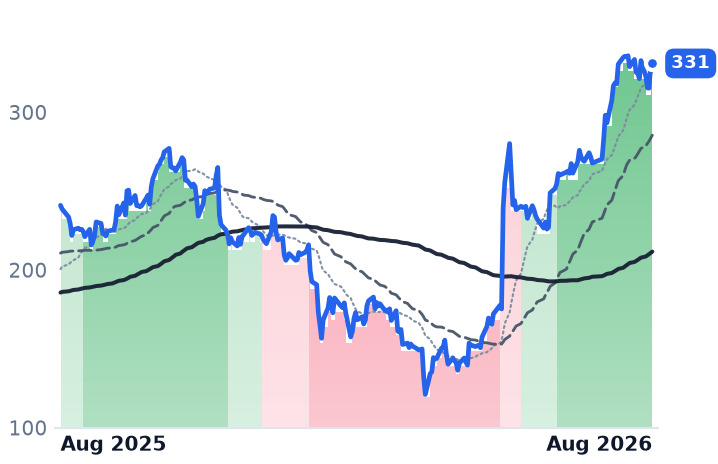
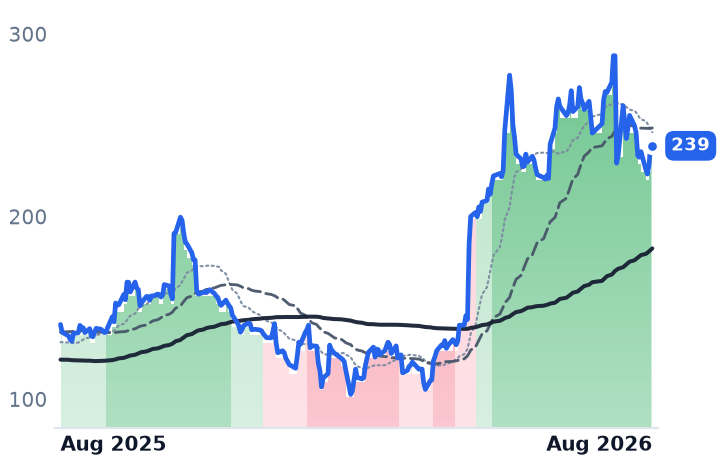
The shares rose 85% between July 29 and August 28. The August 7 earnings reaction supplied 35.8% and the August 27 sector session — Salesforce up 22.6%, ServiceNow 9.2%, the software complex outrunning the Nasdaq — another 10.3%. The remaining 21 sessions compounded to 23.5%, against a run of target increases beginning with Bank of America's upgrade to Buy at $175 and RBC's $215 initiation on August 22.
Price per dollar of trailing gross profit went from about 4.1 times at the end of February to 8.97 times — a 118% expansion while trailing gross profit grew 29%. monday.com trades near a third of that on faster growth; Microsoft, whose GitHub and Copilot stack competes for the same developer budget, trades at 17 times on a 68% gross margin. Forward earnings of 34.6 times rest on consensus 2027 earnings per share of $5.498, fractionally below the $5.505 just delivered.
The business earns the re-rating's first leg: accelerating cloud, a GAAP profit swing, and expanding margin in a quarter when peers' margins broke. What it does not earn is the second leg, priced for a year the company itself describes as half as fast and no more profitable, with the AI bill arriving in cost of revenue while the AI revenue arrives nowhere.
The September quarter is the first reported under that guide. It will show cloud growth, recurring revenue and margin. It will not show how many seats Atlassian sold.