

Palo Alto Grew 14% Organically While CrowdStrike and Fortinet Grew 26%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The largest single session of Palo Alto Networks' advance this year was delivered by a competitor's earnings, and the company's own numbers land Tuesday. CrowdStrike's July-quarter report on August 26 lifted the entire listed security complex the next day; Palo Alto rose with it, then gave back a piece of the gain alone while the group held.
The last financial statement Palo Alto filed, on June 2, showed revenue up 31.1% but only about 14% once CyberArk and Chronosphere are stripped out — the slowest organic growth of the three big security platforms, against 25.8% at CrowdStrike and 25.6% at Fortinet. Its forward-contracted metrics look better than its income statement, and its fiscal 2026 guide of $20.9bn to $21.0bn in remaining performance obligation is the number September 1 either confirms or cuts.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🌱 Emerging Bull | +18.0% | +94.1% |
| Compared against · context, not the story | |||||
CRWD | CrowdStrike | Cybersecurity & Threat Protection | ⚠️ Emerging Bear | +27.1% | −48.4% |
FTNT | Fortinet | Network Security Appliances | 🌱 Emerging Bull | +8.3% | +109.2% |
OKTA | Okta | Identity & Access Management | 🌱 Emerging Bull | +26.3% | +86.7% |
ZS | Zscaler | AI & Data Intelligence | 🔴 Cont. Bear | +21.3% | −33.5% |
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | +14.0% | +44.4% |
S | SentinelOne | Cybersecurity & Threat Protection | 🌱 Emerging Bull | +14.1% | +20.0% |
SAIL | SailPoint | Identity & Access Management | 🔴 Cont. Bear | +28.7% | −1.5% |
RBRK | Rubrik | Other | 🌱 Emerging Bull | +33.7% | +3.4% |
TENB | Tenable | Cybersecurity & Threat Protection | 🌱 Emerging Bull | +20.9% | +22.5% |
QLYS | Qualys | Cybersecurity & Threat Protection | 🌱 Emerging Bull | +38.7% | +38.5% |
CHKP | Check Point Software Technologies | Cybersecurity & Threat Protection | 🔴 Cont. Bear | −0.5% | −27.6% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +31.8% | +1.4% |
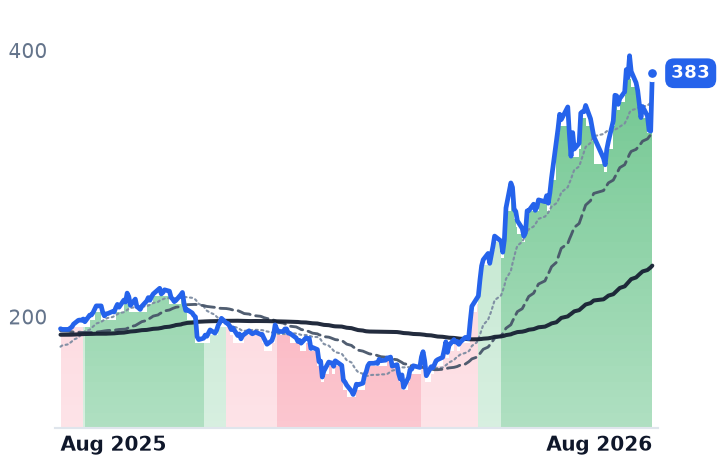
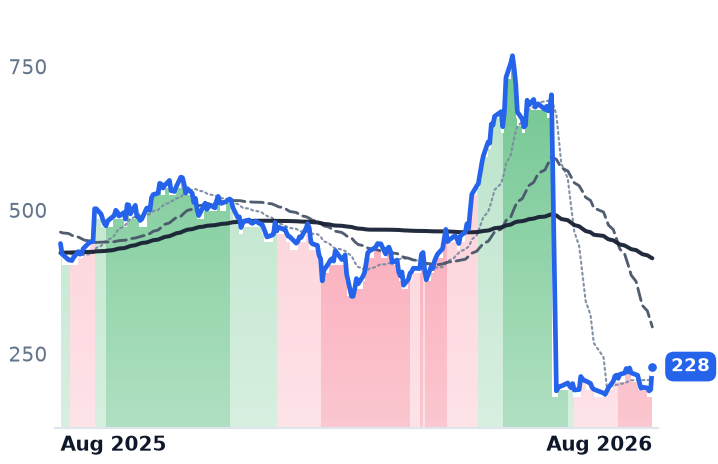
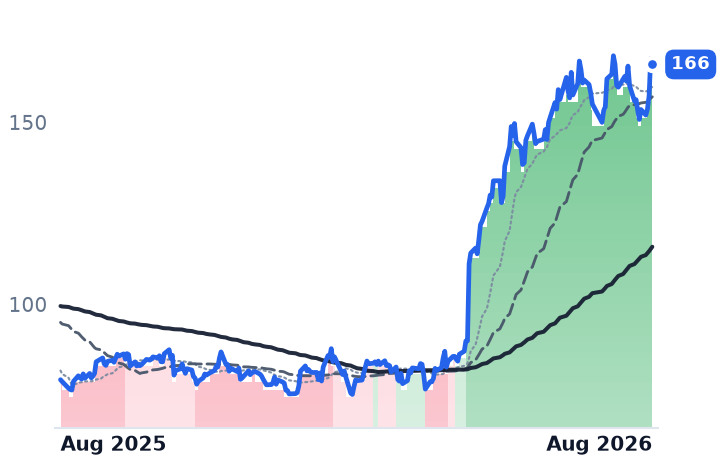
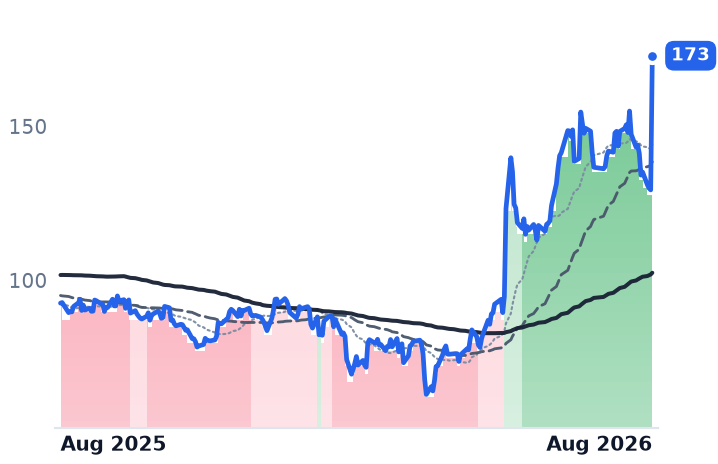
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PANW | $302.1B | 311.5x | 90.2x | 28.5x | 21.8x | 39.6x | 30.4x | 132.4x | 1.4% |
CRWD | $232.1B | — | 185.2x | 43.0x | 39.0x | 57.2x | 51.9x | 667.4x | 0.7% |
FTNT | $122.1B | 58.1x | 48.3x | 16.2x | 15.0x | 20.2x | 18.7x | 41.3x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKTA | $28.7B | 102.3x | 45.0x | 9.3x | 9.0x | 12.0x | 11.5x | 71.1x | 3.4% |
ZS | $29.7B | n/m | 40.1x | 9.4x | 7.6x | 12.2x | 9.9x | 251.1x | 3.2% |
NET | $109.4B | n/m | 244.5x | 43.6x | 38.1x | 60.0x | 52.6x | — | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
S | $7.2B | n/m | 61.3x | 6.9x | 6.0x | 9.3x | 8.1x | n/m | 0.6% |
SAIL | $11.6B | n/m | — | 10.3x | — | 15.6x | — | 890.2x | 1.6% |
RBRK | $20.6B | n/m | 322.3x | 14.5x | 12.5x | 17.9x | 15.5x | n/m | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TENB | $2.4B | n/m | 11.0x | 2.3x | 2.2x | 3.0x | 2.8x | 23.3x | 11.1% |
QLYS | $3.2B | 15.9x | 11.9x | 4.6x | 4.4x | 5.6x | 5.3x | 11.4x | 9.2% |
CHKP | $12.9B | 12.3x | 11.9x | 4.7x | 4.6x | 5.5x | 5.4x | 14.3x | 10.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
PANW | Revenue | +24.3% | +21.2% | +14.2% |
| EPS | +15.3% | +8.9% | +17.6% | |
CRWD | Revenue | +22.2% | +23.7% | +21.9% |
| EPS | −1.2% | +32.6% | +26.5% | |
FTNT | Revenue | +20.1% | +11.4% | +11.1% |
| EPS | +27.8% | +9.4% | +13.3% | |
OKTA | Revenue | +12.0% | +10.0% | +9.5% |
| EPS | +24.3% | +11.7% | +10.9% | |
ZS | Revenue | +25.2% | +16.9% | +16.7% |
| EPS | +29.0% | +11.2% | +17.6% | |
NET | Revenue | +33.7% | +28.7% | +27.5% |
| EPS | +38.0% | +32.5% | +35.3% | |
S | Revenue | +22.4% | +19.9% | +17.6% |
| EPS | +723.4% | +83.7% | +43.0% | |
RBRK | Revenue | +48.7% | +28.4% | +21.5% |
| EPS | −90.5% | −278.6% | +106.1% | |
TENB | Revenue | +8.4% | +7.1% | +6.9% |
| EPS | +27.0% | +10.5% | +10.1% | |
QLYS | Revenue | +8.6% | +7.0% | +6.6% |
| EPS | +8.6% | +9.2% | +5.3% | |
CHKP | Revenue | +3.2% | +6.0% | +5.6% |
| EPS | −7.5% | +9.6% | +9.1% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
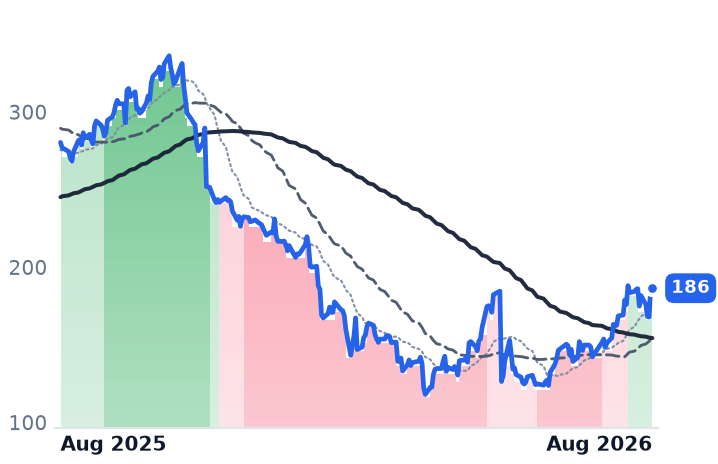
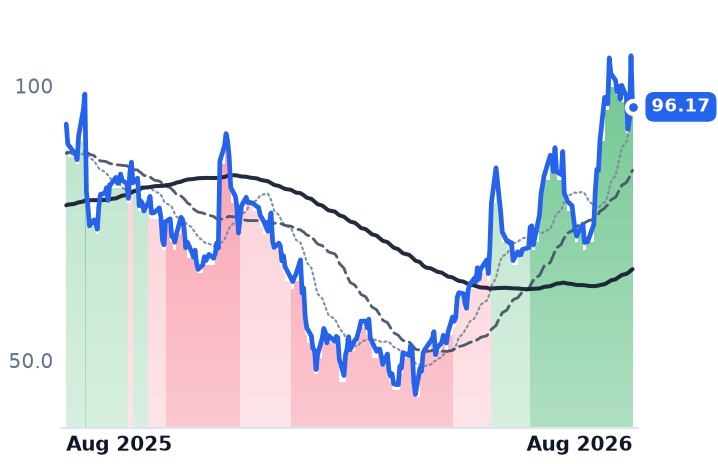
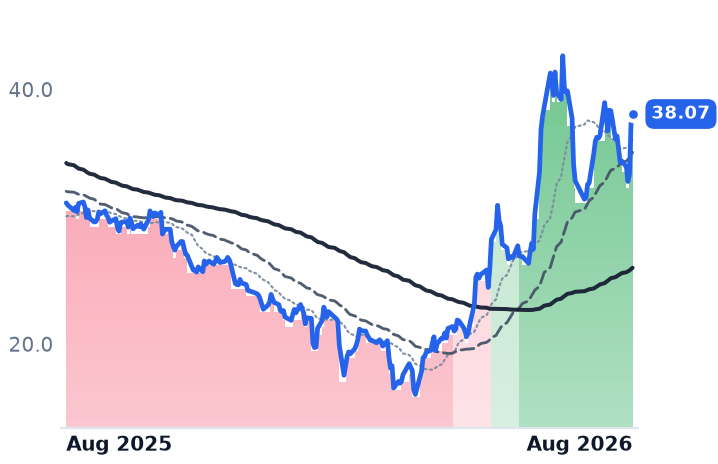
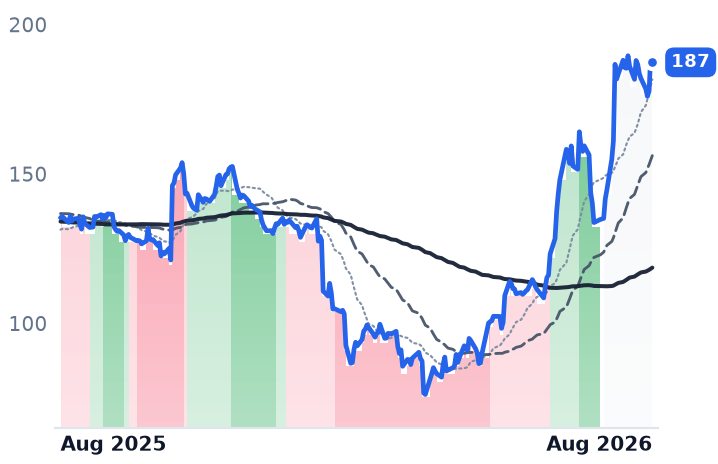
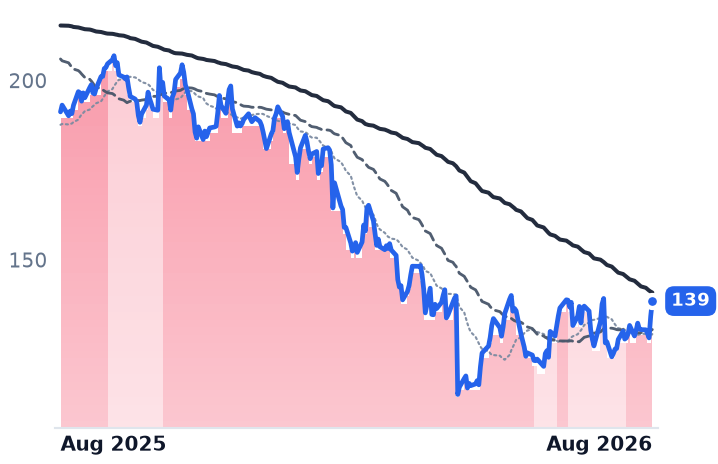
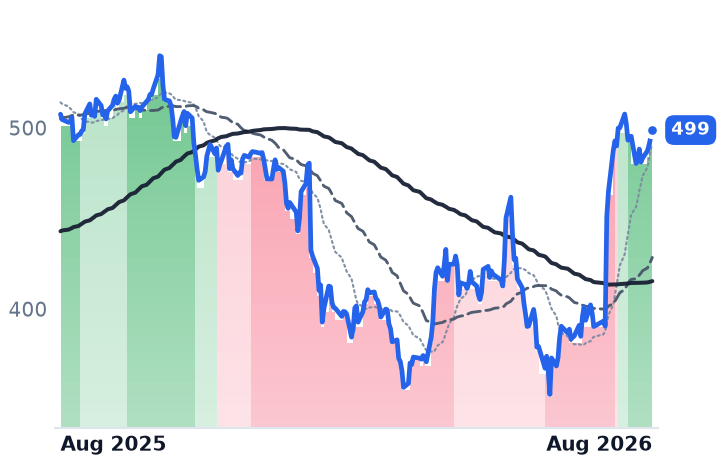
The biggest single day of Palo Alto Networks' advance this year was delivered by another company's earnings. On August 27 the shares rose 12.8% — the session after CrowdStrike reported July-quarter revenue of $1.47bn against $1.44bn expected and adjusted earnings of 31 cents against 29 cents, with Nvidia's results the same week adding to the impulse. The whole listed security complex moved together: Okta up 33.7%, CrowdStrike up 21.3%, Zscaler up 11.0%, Fortinet up 6.6%. The next session Palo Alto fell 3.2% to $370.68 while Check Point rose 3.2% and Tenable rose 2.1% — it gave back roughly a quarter of the move on its own.
That matters because Palo Alto has not published a financial statement since June 2, covering the quarter that ended in April, and the shares have roughly doubled since May 1 on no company disclosure at all. The company reports fiscal fourth-quarter and full-year results after the US close on Tuesday, September 1, with a webcast at 1:30pm Pacific. Consensus looks for about $0.98 a share on roughly $3.35bn of revenue, against a fiscal 2026 guide of $11.415bn to $11.425bn in revenue and $20.9bn to $21.0bn of remaining performance obligation.
What the last disclosure actually said
Palo Alto sells hardware and software firewalls plus a widening stack of security subscriptions to large enterprises and governments. April-quarter revenue of $3.002bn grew 31.1%, but $388m of it came from CyberArk and Chronosphere, the identity and observability businesses acquired in February, leaving organic growth near 14%. Gross margin fell to 67.6% from 74.2% two quarters earlier as purchase-accounting amortization landed in cost of revenue, producing a GAAP operating loss of $183m.
The contracted metrics point the other way. Next-generation-security annual recurring revenue reached $8.1bn, up 60%, while remaining performance obligation grew 36% to $18.4bn; net of the acquisitions, the recurring base still grew faster than the backlog — roughly 28% against 22%. A recurring line outrunning contracted obligations is what displacing incumbent products looks like; backlog outrunning the recurring line is what stretching contract length looks like. Palo Alto discloses neither average contract duration nor the size of its customer-financing book, so the second reading cannot be ruled out from public filings. Cash held up: adjusted free cash flow was $910m against $578m, and the trailing-twelve-month margin 38.5% — though the 37.5% fiscal-year guide implies a step down in the July quarter.
"Q3 was a standout quarter for Palo Alto Networks, with accelerating organic bookings growth as customers turn to us to secure their AI deployments at scale," chairman and chief executive Nikesh Arora said with those results.
The other two grew faster
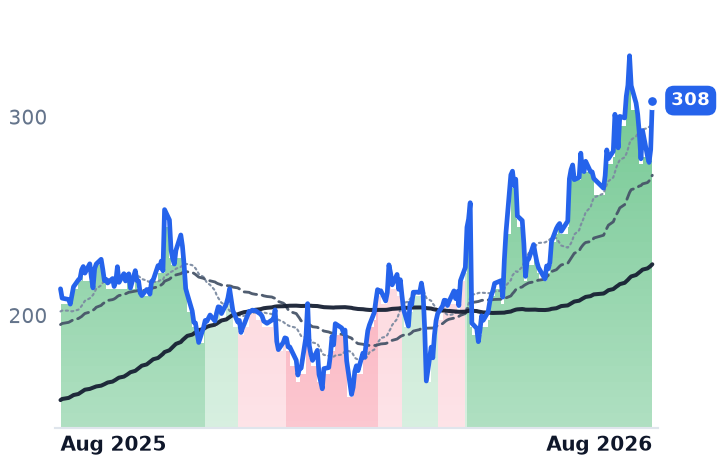
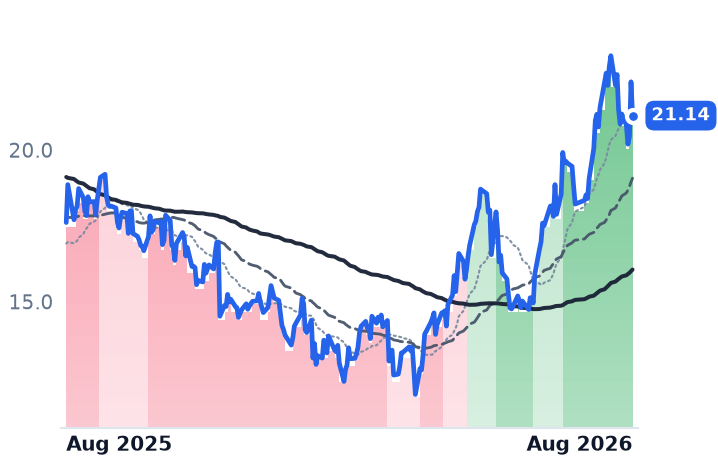
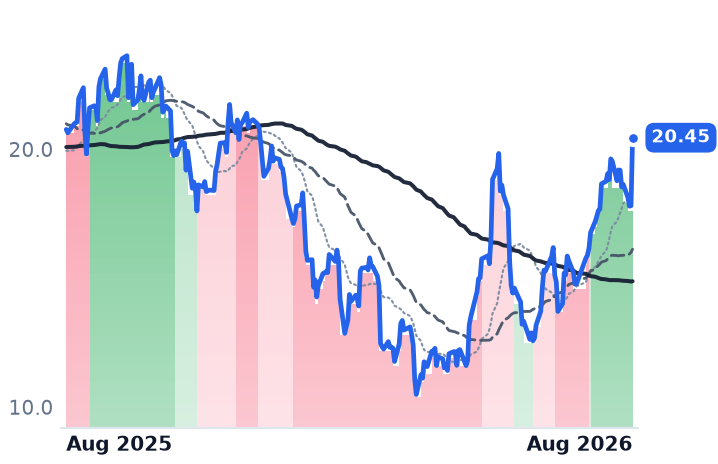
CrowdStrike, which sells the cloud-native Falcon platform by subscription, posted a fifth consecutive quarter of acceleration to 25.8% growth, record net new annual recurring revenue of $333m, up 51%, and raised its fiscal 2027 net-new-ARR growth outlook to 34%. "We are in an arms race. AI is driving more cyber attacks. AI is driving more cyber spending," chief executive George Kurtz told investors on the August 26 call. It is also selling into CyberArk's socket: identity ARR of $585m, up 34%, with privileged account security up thirty-five times year on year.
Fortinet, whose FortiGate firewalls run on in-house silicon, grew June-quarter revenue 25.6% to $2.048bn with billings up 33% and product revenue up 52% to $773m at a record 38% non-GAAP operating margin. Its management told investors customers now view it as a platform provider comparable to Palo Alto and CrowdStrike. The firewall base is not quietly decaying; it is re-accelerating, and not only for Palo Alto.
The budget impulse behind all of this is external and datable. Anthropic's Mythos model release in June reset enterprise perception of AI-enabled attack capability — CNBC wrote on June 5 that it "rejuvenated the cybersecurity sector" — and Arora said "Mark my words, Mythos has increased the terminal value of the entire cybersecurity industry," citing 1,200 inbound companies and more than 800 customer meetings in six weeks.
What the price now assumes
At $302bn of market value, Palo Alto costs about $40 for every dollar of gross profit it earned over the past year and about $30 against the coming year's — roughly double the $20 it cost in early May. Fortinet costs about $20 trailing and $19 forward; CrowdStrike about $57 and $52. Its 311x trailing price-to-earnings ratio is amortization noise, not a valuation signal, since the quarter was a GAAP loss.
The sector's re-rating is earned by the sector: two of the three delivered accelerating numbers and one of them raised its forward guide. What Palo Alto has not yet earned is the portion of its own multiple that assumes it is the share gainer rather than a passenger. Consensus prices about 21% compounding into fiscal 2027; the last organic print was 14%. The displacement evidence is real and it is one quarter old, resting on a decomposition the company itself does not publish.
For four months the shares have moved on a rival's earnings, a chipmaker's, and one AI model release. Tuesday afternoon, Palo Alto has to supply its own.