

Half of Symbotic's $22.5bn Backlog Is Orders From a Venture It Owns 35% Of
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Symbotic's June quarter improved on every reported line — revenue up 21.7% year on year, gross margin up more than four points, a swing to operating profit — and the shares lost a sixth of their value the next session. What got repriced was the order book's counterparties.
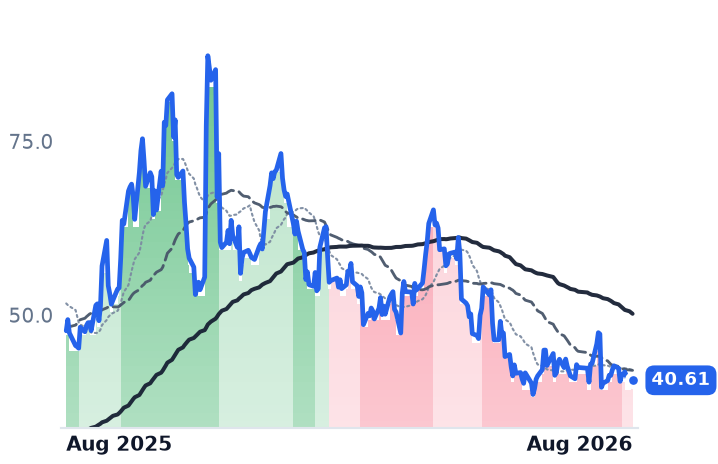
Roughly $11.6bn of the $22.5bn backlog is orders from GreenBox, a joint venture Symbotic part-owns and which has signed no unrelated customer more than two years after it was formed. Walmart supplied over 84% of fiscal 2025 revenue. Gross-profit dollars have risen sharply while the shares fell, taking price-to-gross-profit from roughly 73x in May to 46x. The de-rating is a verdict on whose orders those are, not on whether the machines work.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
SYM | Symbotic | Industrial Automation & Controls | ⚠️ Emerging Bear | −4.1% | −14.9% |
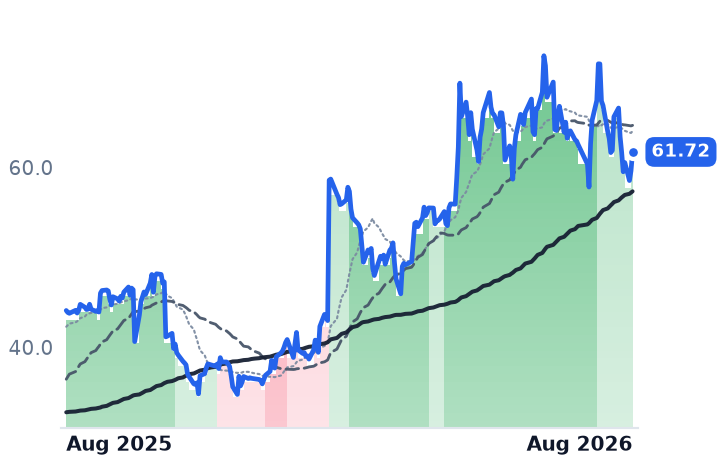
CGNX | Cognex | Precision Motion & Sensors | 🟢 Cont. Bull | +2.3% | +40.0% |
| Compared against · context, not the story | |||||
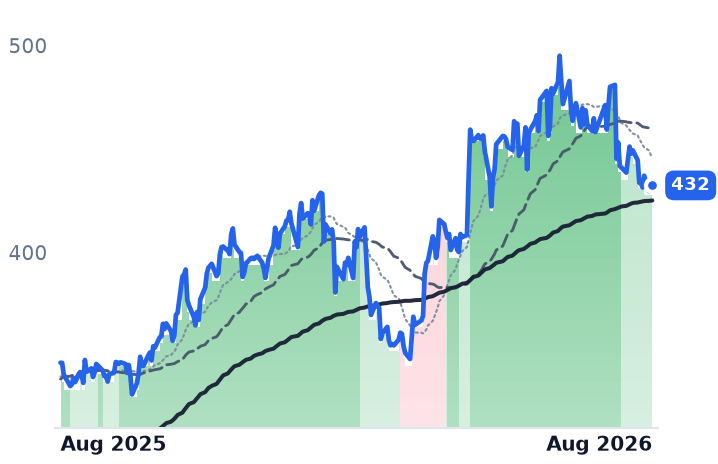
ROK | Rockwell Automation | Industrial Automation & Controls | 🟢 Cont. Bull | −8.2% | +24.7% |
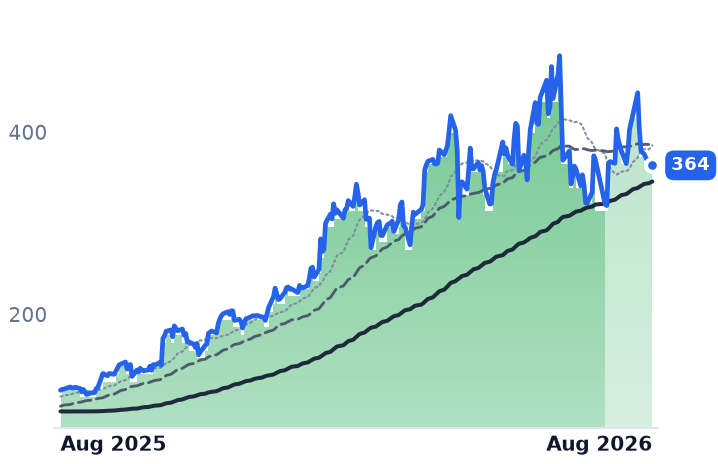
TER | Teradyne | Semiconduct Equipment | 🟢 Cont. Bull | +13.4% | +211.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SYM | $26.1B | 423.9x | 73.3x | 9.8x | 9.4x | 45.6x | 43.7x | 401.6x | 2.8% |
CGNX | $10.3B | 58.8x | 36.7x | 9.4x | 9.0x | 13.7x | 13.0x | 36.0x | 2.6% |
ROK | $48.6B | 40.9x | 33.1x | 5.4x | 5.4x | 9.9x | 9.9x | 29.2x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TER | $59.4B | 51.8x | 41.2x | 13.3x | 11.5x | 22.4x | 19.4x | 40.7x | 1.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SYM | Revenue | +23.6% | +31.3% | +24.4% |
| EPS | +128.1% | +35.8% | +13.5% | |
CGNX | Revenue | +16.7% | +9.3% | +9.3% |
| EPS | +74.6% | +19.5% | +13.6% | |
ROK | Revenue | +10.0% | +5.5% | +6.4% |
| EPS | +31.5% | +12.1% | +12.1% | |
TER | Revenue | +67.0% | +21.3% | +24.5% |
| EPS | +158.9% | +27.6% | +31.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Symbotic builds and installs AI-driven robotic systems that store, retrieve and sort cases inside very large retail and wholesale distribution centers. On August 5 it reported a fiscal third quarter that improved on every reported line. Revenue reached $720.8m, up 21.7% from a year earlier. Gross margin was 22.3% — the fourth straight quarterly improvement, and more than four points better than the year-ago June quarter. The company swung to a $32.9m operating profit from a $20.2m loss. The next session the shares fell 16.2%, from $47.26 to $39.60, on close to 5m shares, several times recent daily volume.
The reason is not in the income statement. It is in who the orders are with. Symbotic held its disclosed backlog at $22.5bn and told investors only about 15% of it converts to revenue over the next twelve months. Roughly $11.6bn of that total — over half — is orders from GreenBox, a joint venture 35% owned by Symbotic and 65% by SoftBank. Goldman Sachs analyst Mark Delaney, downgrading the stock to sell, noted GreenBox has signed no unrelated customer more than two years after its formation and called it "the type of circular transaction that investors are increasingly scrutinizing."
The cash mechanism
The accounting consequence is specific. Symbotic can fund its 35% share of the venture with cash or with forgone profit on the systems it ships to it, so those shipments generate limited initial cash — which is why Goldman expects cash-flow growth to lag reported adjusted profit. That is roughly what the quarter showed: cash fell to $1.7bn from $2.0bn and free cash flow was negative on payment timing, with management asking investors to judge cash generation annually rather than quarterly.
The rest of the revenue base is Walmart, which supplied more than 84% of fiscal 2025 revenue. Symbotic has since bought Walmart's Advanced Systems and Robotics business for $200m in cash plus up to $350m contingent on orders, alongside a commercial agreement under which Walmart committed to deploy systems for 400 store-based pickup and delivery sites. That order is not in the $22.5bn. Management said full contract conversion is not expected until early 2028, after a first prototype about six months out, a redesigned second unit, and a third install.
Why counterparty quality carries weight here: the fiscal 2024 restatement was a percentage-of-completion problem. Symbotic found errors in which costs were expensed before milestones were achieved, accelerating revenue, plus unbillable cost overruns on certain deployments, and put the correction at $30m–$40m of system revenue and profit.
"We are well on track to deliver against our key objectives for our fiscal year," chairman and chief executive Rick Cohen said in the August 5 release, adding that the company sees "increasing opportunities to broaden the scope of our work with existing and prospective customers."
The cycle is not the problem
Automation demand is running. Rockwell Automation raised full-year organic growth guidance to 7.5%–9.5%, citing semiconductors, data centers and warehouse automation, and Teradyne doubled revenue year on year. Underneath, though, the warehouse-robot order book is thinner than its dollar value: North American buyers ordered nearly 18,000 units worth about $1.2bn in the first half of 2026, with units up 2% and order value up 7% — price and mix doing most of the work.
Cognex, the machine-vision maker that reported a day later, is the structural counter-case: 70.6% gross margin, June-quarter free cash flow of $68m against $40m a year earlier, and roughly 80% of trailing free cash flow returned to shareholders. Its shares fell too, 13.7% since August 5, but nothing in its cash statement is in question.
What the de-rating buys
Symbotic's twelve-month share decline is entirely multiple compression. Trailing gross profit rose 44.6% to $571m over that span while the stock fell 15.4%, taking price-to-gross-profit from about 73x in May to 46x. The earned part of the business case is real and improving — margin is rising, deployments number 77 in progress and 56 operational, and software and services grew far faster than systems, though they are only about 7% of revenue. What nothing yet resolves is whether an order book contracted mostly with a venture Symbotic co-owns and a customer that is most of its revenue behaves like a normal backlog when it converts. Management has guided fourth-quarter profit margin flat despite higher revenue, and pinned the next margin step to a storage redesign scaling in the second half of 2027.
Symbotic reports its fiscal fourth quarter on November 23, and management has asked to be judged on annual cash flow rather than quarterly. That invitation comes with a deadline attached: the fiscal year ends with that print.