

Equinix Guides Its Cost of Capital Up 150 Basis Points as Digital Realty Pays in Stock
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.5
The two largest listed data-center landlords are financing the same shortage in opposite currencies, and only one of them has told investors what it will cost. Equinix, whose 273 interconnection campuses house the traffic exchange between clouds and carriers, is funding a doubled capital plan with retained cash and debt: dilution of just 1.1% over the year, but leverage rising a full turn to about 4.6x and blended cost of capital guided up roughly 150 basis points. Digital Realty is doing the reverse, issuing shares — the count rose 4.6% — while net debt fell to 4.7x earnings.
Both businesses are accelerating. Digital Realty's revenue grew 28.9% in the June quarter; Equinix's interconnection line reached $453m. And both stocks are cheaper than in mid-May on sales and gross profit despite rising over twelve months, because the revenue outran the price.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
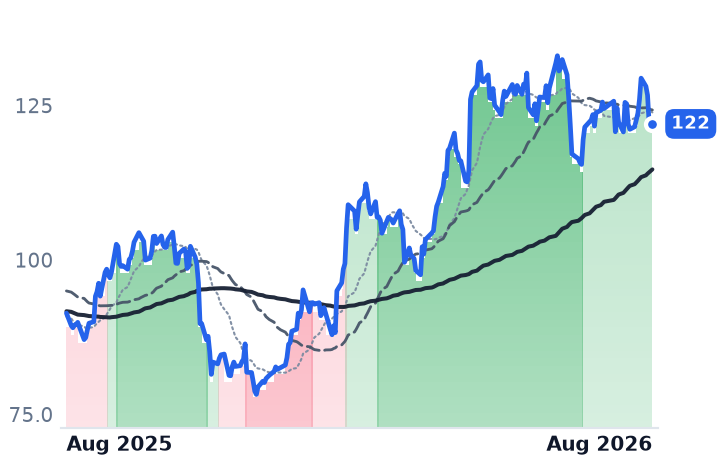
DLR | Digital Realty Trust | Data Center Operators | 🟢 Cont. Bull | −1.3% | +16.6% |
EQIX | Equinix | Data Center Operators | 🟢 Cont. Bull | +3.0% | +37.0% |
| Compared against · context, not the story | |||||
AMT | American Tower | Tower & Fiber Infrastructure | 🔴 Cont. Bear | +2.5% | −14.6% |
CCI | Crown Castle | Tower & Fiber Infrastructure | 🔴 Cont. Bear | −0.3% | −24.6% |
SBAC | SBA Communications | Tower & Fiber Infrastructure | 🔴 Cont. Bear | +4.4% | −17.1% |
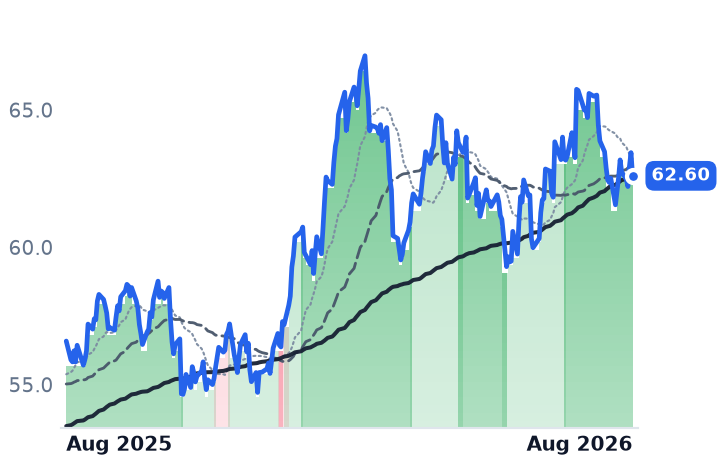
IRM | Iron Mountain Incorporated | Records & Storage Management | 🟢 Cont. Bull | −2.9% | +33.5% |
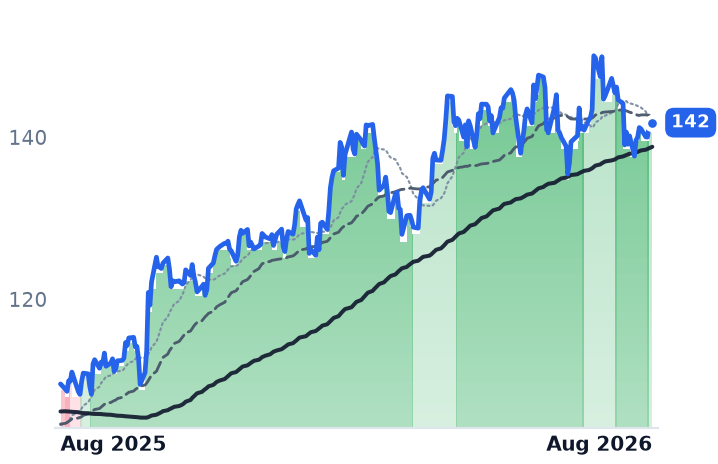
O | Realty Income | Single-Tenant Net Lease | 🟢 Cont. Bull | −3.3% | +10.6% |
PLD | Prologis | Industrial Logistics | 🟢 Cont. Bull | −2.3% | +29.4% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +3.4% | +19.7% |
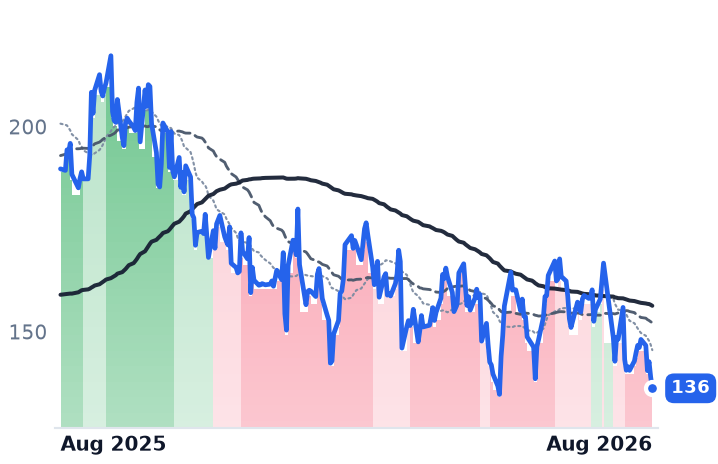
VST | Vistra | Retail-Focused Operators | 🔴 Cont. Bear | −8.4% | −28.2% |
NRG | NRG Energy | Retail-Focused Operators | 🔴 Cont. Bear | −11.3% | −21.6% |
TLN | Talen Energy | Wholesale Generators | 🟢 Cont. Bull | −3.6% | −11.7% |
VRT | Vertiv | Advanced Power Systems | 🟢 Cont. Bull | −2.8% | +108.1% |
GEV | GE Vernova | Power Generation & Propulsion | 🟢 Cont. Bull | −7.2% | +58.0% |
CEG | Constellation Energy | Wholesale Generators | 🔴 Cont. Bear | +5.0% | −11.8% |
12-month price & trend


| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DLR | $63.4B | 78.8x | 60.9x | 9.3x | 8.9x | 67.3x | 64.7x | 23.4x | 2.2% |
EQIX | $94.0B | 61.1x | 55.5x | 9.6x | 9.1x | 18.5x | 17.7x | 25.9x | 1.5% |
AMT | $84.9B | 25.0x | 26.1x | 7.8x | 7.7x | 10.6x | 10.5x | 18.3x | 4.7% |


| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCI | $34.8B | 32.2x | 41.4x | 8.4x | 8.6x | 13.2x | 13.6x | 21.0x | 6.9% |
SBAC | $19.4B | 19.6x | 23.7x | 6.7x | 6.8x | 10.6x | 10.6x | 17.0x | 5.4% |
IRM | $33.1B | 79.6x | 44.8x | 4.4x | 4.1x | 8.1x | 7.6x | 20.9x | -1.5% |

| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
O | $52.2B | 40.3x | 36.3x | 8.8x | 9.2x | 12.8x | 13.4x | 12.2x | 4.2% |
PLD | $120.4B | 28.7x | 35.1x | 13.1x | 14.0x | 45.1x | 48.1x | 18.6x | 4.4% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VST | $54.4B | 27.0x | 18.7x | 3.4x | 2.4x | 26.3x | 18.7x | 11.3x | 2.5% |
NRG | $21.2B | — | 11.3x | — | 0.6x | — | — | 10.5x | 1.6% |
TLN | $17.2B | n/m | 18.4x | 4.9x | 3.9x | 10.9x | 8.7x | 36.8x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
GEV | $267.6B | 28.5x | 33.0x | 6.5x | 5.8x | 32.0x | 28.6x | 28.5x | 4.6% |
CEG | $107.0B | 29.0x | 24.7x | 3.5x | 3.2x | 20.0x | 18.4x | 15.8x | 0.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DLR | Revenue | +17.5% | +11.0% | +14.5% |
| EPS | −23.3% | −6.4% | +22.7% | |
EQIX | Revenue | +11.1% | +10.7% | +11.5% |
| EPS | +16.3% | +10.3% | +9.9% | |
AMT | Revenue | +4.1% | +3.3% | +6.1% |
| EPS | +36.1% | +1.1% | +11.6% | |
CCI | Revenue | −5.1% | +1.3% | +2.4% |
| EPS | +106.9% | +46.8% | +4.8% | |
SBAC | Revenue | +1.5% | +2.5% | +3.6% |
| EPS | −21.8% | +8.2% | +10.1% | |
IRM | Revenue | +17.0% | +8.8% | +8.0% |
| EPS | +24.2% | +11.7% | +12.6% | |
O | Revenue | +7.4% | +4.9% | +9.9% |
| EPS | +26.1% | +10.1% | −2.4% | |
PLD | Revenue | +5.6% | +9.4% | +7.5% |
| EPS | +33.6% | −5.2% | +13.2% | |
VST | Revenue | +16.7% | +9.7% | +5.4% |
| EPS | +80.8% | +18.5% | +18.5% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.5% | +15.8% | |
TLN | Revenue | +84.0% | +16.0% | +4.9% |
| EPS | +247.2% | +49.2% | +17.7% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
GEV | Revenue | +24.0% | +14.6% | +14.9% |
| EPS | +319.0% | −19.6% | +41.4% | |
CEG | Revenue | +37.2% | +2.5% | +5.3% |
| EPS | +28.9% | +10.4% | +26.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Vacancy in the largest North American data-center markets ended last year at 1.4%, a record low, and 0.3% in Northern Virginia. Record space under construction is 88% pre-leased before it opens. Asking prices for 3-to-10-megawatt requirements rose 12.5% in a year. That is the whole mechanism: leases signed at the pricing of five years ago are expiring into a market with almost nothing available, so rent resets sharply upward without a single new customer being won.
The question is not whether the two landlords that dominate the listed market are capturing it. It is what they are paying to build the next tranche.
Two ways to buy a megawatt
Digital Realty is the wholesale developer — 309 facilities leased in large blocks to cloud and enterprise tenants, with about 3.0 gigawatts in service. Its June-quarter revenue reached $1.92bn, up 28.9% year on year, an acceleration from 16.2% in the prior quarter. Operating margin widened to 25.9% from 14.2% a year earlier. Backlog of signed-but-not-commenced leases hit a record $1.9bn at full share, roughly 30% of in-place data-center revenue. Renewals above one megawatt repriced 66.7% higher in cash terms.
The construction pipeline is $20bn, double the first half of the year, covering 1.4 gigawatts that is 63% pre-leased at an expected 11.5% stabilized yield. Paying for it has meant shares. Digital Realty bought Blackstone out of three fully leased Northern Virginia sites for $3.5bn, of which $2.3bn was stock, and is buying Columbia Capital and more of South Africa's Teraco with equity too. Diluted shares rose from 345.7m to 361.5m. Yet core funds from operations per share still grew 14%, and leverage fell to 4.7x with a 2.9% average coupon and a maturity wall that peaks in 2029, not next year.
Equinix sells the opposite product: cabinets, power density and cross-connects inside neutral campuses where networks meet. Revenue grew 16.4%, the fourth straight quarterly acceleration. Interconnection revenue reached $453m, up 11.3%, on a record 9,700 net new interconnections. Monthly recurring revenue per cabinet reached $2,538, up 6%, and churn fell to 1.8%. Adjusted funds from operations per share rose 18% alongside the largest guidance raise in the company's history.
Equinix is doubling capital spending to $5-6bn this year and $5-7bn annually through 2029. It will fund that with a 50% payout ratio and debt — barely 1.1% dilution — and has told investors the consequence: leverage up about one turn, and blended cost of capital up roughly 150 basis points. That is the line the bond market now presses on.
The duration test, and what it showed
In the week the 30-year Treasury yield touched 5.32%, its highest since 2007, both landlords fell — Digital Realty 4.5%, Equinix 3.0%. But the actual bond proxies did not: American Tower rose 1.2%, Realty Income 0.3%, Prologis was flat, and the S&P 500 fell 1.5%. Over twelve months the three listed tower REITs fell between 15% and 26% while these two compounded. Whatever is moving them, it is not the yield curve alone.
What has moved is the price of the revenue. Both stocks are higher over a year — Digital Realty 16.8%, Equinix 38.5% — and both are flat-to-slightly-down over three months while sales compounded. Equinix now trades at 20.7 times trailing gross profit and 19.8 times forward, against 21.6 times in mid-May. Digital Realty is at 10.3 times sales against 11.1 times then. Growth is outrunning the multiple, not following it. Consensus still models 16.9% revenue growth at Digital Realty this year, below the 28.9% it just reported.
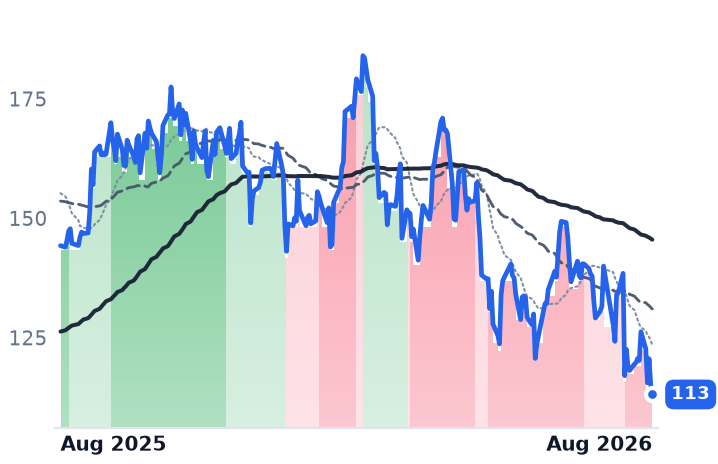
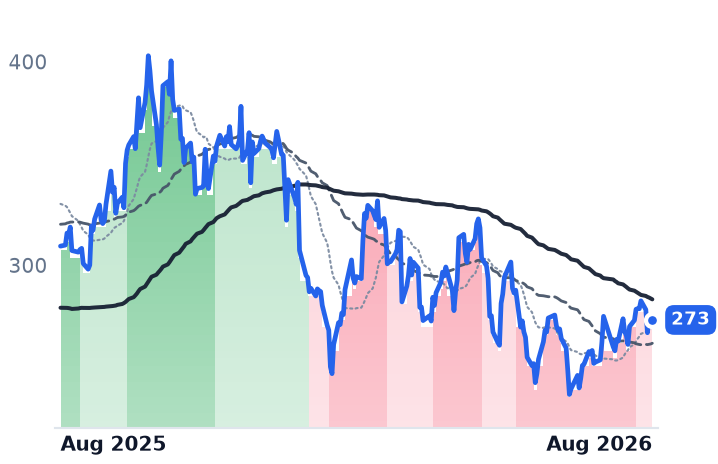
Digital Realty's shares only regained a firm uptrend in mid-August; they spent late November through January in a sustained decline. The year was not a straight line.
The competitive floor differs too. Digital Realty bids for hyperscale megawatts against CyrusOne, owned by KKR and Global Infrastructure Partners, and QTS, owned by Blackstone — permanently capitalized private balance sheets that never answer to a quarterly share price. Equinix's defense is the ecosystem itself: eight of the ten largest AI model providers run workloads on its platform, and a cross-connect is worth what the other tenants in the building are worth.
The setup
Where it stands — Both landlords are accelerating into a 1.4% vacancy market, and both are cheaper per dollar of revenue than three months ago. Would confirm — Digital Realty's backlog rising above $1.9bn with cash renewal spreads holding in the raised 9-11% range. Would invalidate — Equinix's blended cost of capital rising more than the guided 150 basis points, or AFFO per share growth falling below 9%. Watch next — Third-quarter results in late October, where Equinix guided softly despite raising the full year. Valuation — Equinix at 20.7x trailing gross profit and 19.8x forward, versus 21.6x in mid-May; Digital Realty near 23.4x 2026 core FFO guidance.