

Ideal Power Sold $5,800 Last Quarter and Led the 800-Volt Power Group Higher
Prompt v1.5
The listed companies tied to the 800-volt direct-current architecture Nvidia wants inside 2027 data centers gained ground over the past month — and every dollar of that gain came from two firms with nothing inside a server rack. Ideal Power, a 17-person developer of bidirectional solid-state switches, booked $5,800 of revenue in the June quarter and rose 17%. Ultralife, a military battery maker whose revenue fell 1.3% year on year, rose 28% on a record defense backlog.\n\nThe three companies actually shipping rack power all fell. Vicor grew core revenue 49% and lifted backlog 145% to $379.7m; Bel Fuse accelerated revenue growth to 25.2% and raised guidance. Both declined anyway. Only Navitas, down 27% on revenue with no trailing gross profit, has business results that match its share price. Meaningful 800-volt revenue is gated to 2027 silicon.
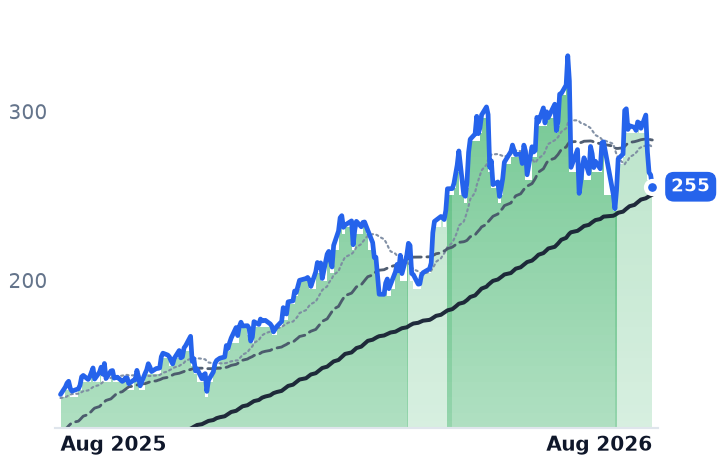
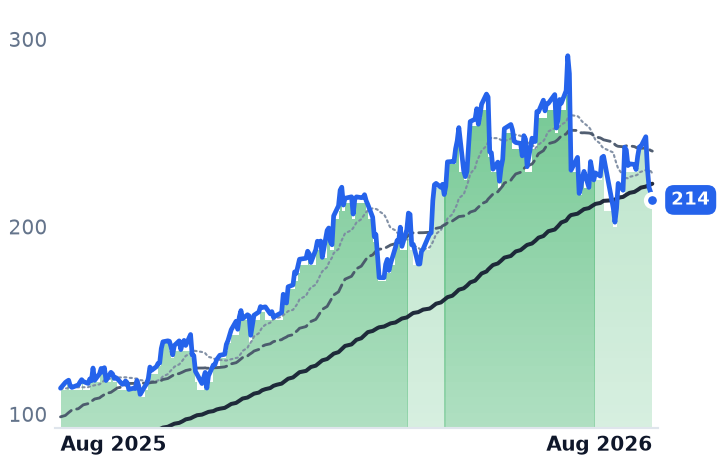
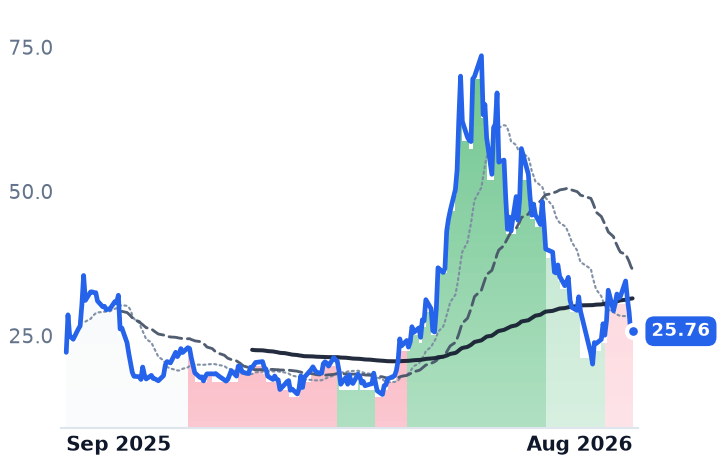
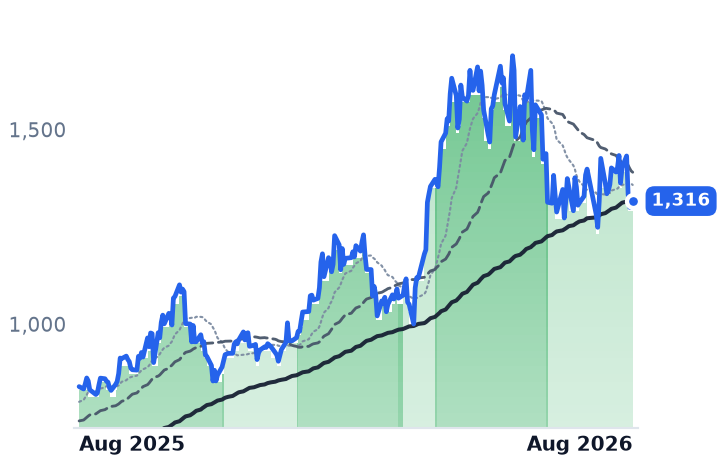
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
IPWR | Ideal Power | Semiconductors | 🌱 Emerging Bull | +26.3% | −5.0% |
ULBI | Ultralife | Electrical Equipment & Parts | 🔴 Cont. Bear | +30.8% | −2.8% |
VICR | Vicor | Power Conversion & Control | 🟢 Cont. Bull | +4.4% | +293.6% |
NVTS | Navitas Semiconductor | Analog & Power Management | 🟢 Cont. Bull | +29.6% | +101.7% |
BELFB | Bel Fuse | Power Conversion & Control | 🟢 Cont. Bull | +1.8% | +92.9% |
BELFA | Bel Fuse | Hardware, Equipment & Parts | 🟢 Cont. Bull | +2.1% | +88.2% |
NVDA | NVIDIA | Processors & Accelerators | 🟢 Cont. Bull | +9.0% | +20.6% |
WOLF | Wolfspeed | Analog & Power Management | 🌱 Emerging Bull | +17.7% | +16.6% |
MPWR | Monolithic Power Systems | Analog & Power Management | 🟢 Cont. Bull | +2.7% | +56.8% |
DELL | Dell Technologies | Enterprise Servers | 🟢 Cont. Bull | +12.7% | +241.6% |
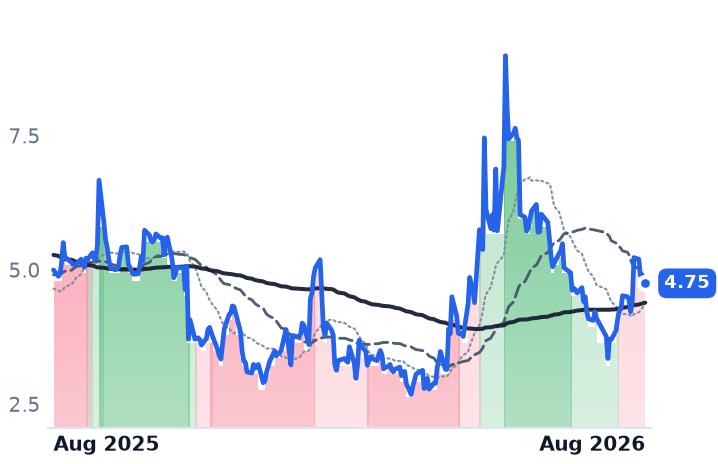
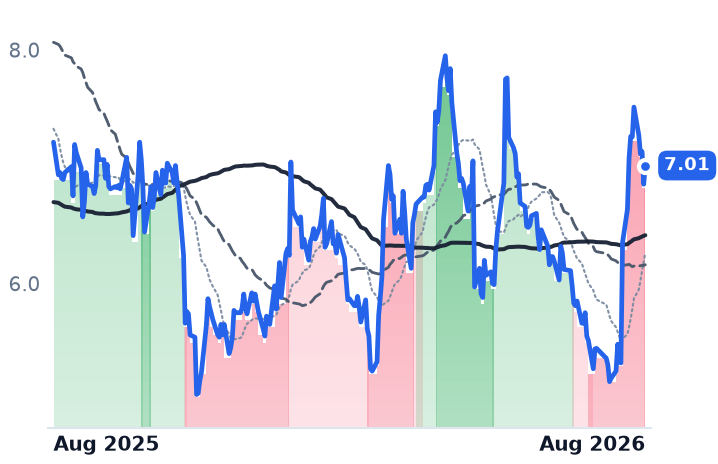
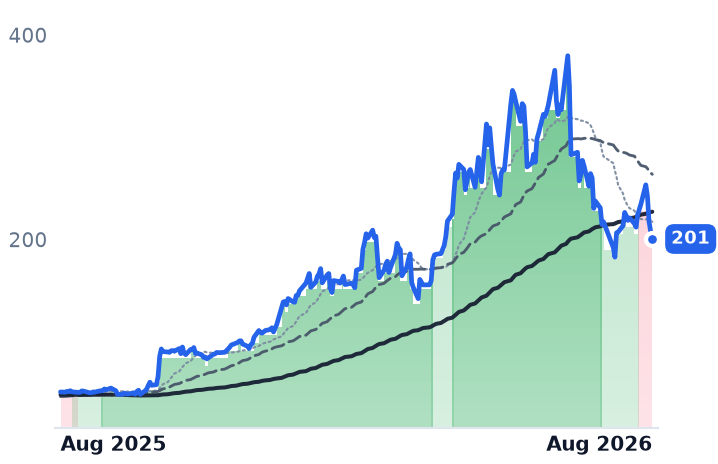
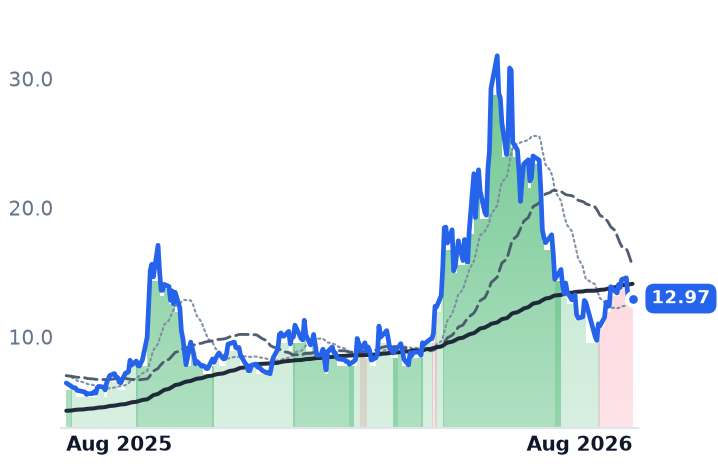
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IPWR | $40.6M | n/m | — | — | 50.7x | — | — | 0.0x | -23.4% |
ULBI | $260.4M | n/m | 18.2x | 1.4x | 1.2x | 5.8x | 4.9x | n/m | 0.8% |
VICR | $8.3B | 45.5x | 43.2x | 14.7x | 12.9x | 24.3x | 21.2x | 44.8x | 0.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVTS | $2.4B | n/m | — | 60.4x | 49.9x | 421.8x | 348.3x | n/m | -3.1% |
BELFB | $2.9B | 57.6x | 21.8x | 3.7x | 3.5x | 9.4x | 8.8x | 18.1x | 2.8% |
BELFA | $2.8B | 57.6x | 17.6x | 3.7x | 3.4x | 9.4x | 8.5x | 18.1x | 2.8% |

| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
WOLF | $1.1B | n/m | — | 1.7x | 1.7x | — | — | n/m | -32.4% |
MPWR | $65.7B | 73.9x | 46.2x | 17.6x | 15.2x | 31.8x | 27.4x | 54.2x | 0.9% |

| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DELL | $373.9B | 32.2x | 21.7x | 2.5x | 1.9x | 12.5x | 9.7x | 21.6x | 2.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
IPWR | Revenue | +1500.0% | +0.0% | +975.0% |
| EPS | −31.5% | −18.8% | −20.3% | |
ULBI | Revenue | +6.2% | — | — |
| EPS | +22.9% | — | — | |
VICR | Revenue | +41.7% | +46.9% | +25.4% |
| EPS | +91.8% | +53.2% | +33.3% | |
NVTS | Revenue | +7.5% | +65.0% | +66.1% |
| EPS | −16.4% | +25.7% | −32.2% | |
BELFB | Revenue | +24.4% | +12.8% | +11.0% |
| EPS | +62.1% | +14.8% | +15.0% | |
BELFA | Revenue | +24.2% | +12.4% | +11.2% |
| EPS | +61.2% | +13.8% | +14.3% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% | |
MPWR | Revenue | +55.8% | +51.2% | +24.7% |
| EPS | +64.5% | +58.9% | +25.5% | |
DELL | Revenue | +16.2% | +73.9% | +20.9% |
| EPS | +27.3% | +159.7% | +19.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Two companies with no product inside an artificial-intelligence server rack led the market's 800-volt power theme over the past month. Neither sells a converter, a magnetic or a power stage into a graphics-processor tray. One of them is barely a business yet.
Ideal Power, an Austin-based developer of a bidirectional solid-state switch it calls B-TRAN, recorded revenue of $5,800 in the second quarter against a net loss of $3.4m. It employs 17 people. The shares rose 17.3% over the past month, which values the company at roughly 2,660 times trailing sales — a number that means nothing except that revenue is not the thing being priced. What is being priced is a $400m sales "pipeline", split about evenly between automotive and data centers, and a co-developed intelligent circuit breaker for an unnamed US hyperscaler aimed at Nvidia's Rubin Ultra generation. Prototypes are due at the end of the fourth quarter of 2026. The company raised $27.7m in May, holds $41.3m of cash and guides to burning about $10.4m this year.
Ultralife, the month's best performer at 28%, makes lithium batteries and military communications gear and carries a market value near $118m. Its June-quarter revenue fell 1.3% to $47.9m. Gross margin rose 590 basis points to 28.9%, but 230 of those points came from a one-off refund of tariffs collected under the International Emergency Economic Powers Act (IEEPA). The genuine news was order flow: backlog reached a record $117.5m, up 39%, and roughly $130m by early August on defense pull-through. At 2.65 times trailing gross profit, 0.89 times book and 8.3 times forward earnings, the market is plainly not paying for artificial-intelligence content here. It is a defense restocking story that happens to sit in the same neighborhood.
The suppliers that ship fell instead
Vicor, which makes the modular direct-current converters that step a rack bus down to the volt-level rails a processor draws, had the best quarter of its cycle. Stripping the prior year's $45m patent settlement, core revenue grew 49.3% to $143.4m. Gross margin expanded 280 basis points sequentially to 58.0%, far above the 52.6% it earned across 2025. One-year backlog rose 145% to $379.7m, and full-year guidance went above $600m. The shares fell 24.9% over three months. Price per dollar of trailing gross profit has compressed from about 43.8 times in May to 33.9 times — still nearly four times the 9.1 times of a year ago. Its litigation is live: the US International Trade Commission opened a new Section 337 investigation in February naming Monolithic Power Systems, the rival that took the H100 socket Vicor lost.
Bel Fuse, a maker of magnetics, alternating-to-direct-current power supplies and Cinch connectors, is the sharpest disconnect. Revenue growth accelerated to 25.2%, gross margin rose 120 basis points and operating income grew 47.4% — roughly twice the pace of sales. Data solutions revenue reached $58m, up 55%, on the start of a high-performance-computing ramp. Defense, at $66.5m, is still the bigger line. The stock fell 8.8% in the month after that beat-and-raise, leaving 26.0 times forward earnings against consensus for 45% earnings growth this year.
Navitas is the one name whose decline the numbers support. The gallium-nitride and silicon-carbide designer is one of ten silicon suppliers named in Nvidia's 800-volt reference architecture, and by far the smallest. June-quarter revenue was $10.5m, down 27.3%. Across four quarters it has produced minus $0.6m of gross profit on $36.5m of revenue. Diluted shares are up 18.6% year on year, including $373m raised at $21.89 — some 40% above where the stock now trades. Even after a 46.5% three-month fall it is held at 92.7 times trailing sales.
Why good quarters did not pay
The gating fact is timing. Full-scale 800-volt deployment arrives with Nvidia's Kyber racks in 2027; Navitas dates its sidecar racks to mid-2027. That is five or six quarters of waiting, and long-dated revenue is what a discount rate punishes. In late July the PHLX Semiconductor Index shed more than $1trn over three sessions as 30-year Treasury yields touched 19-year highs. Vicor and Navitas both slipped into downtrends by 20 August, their 50-day averages crossing below their 200-day, after trading in clear uptrends in May. Bel Fuse's uptrend weakened over the same weeks.
So the theme did not stall. It rotated — out of the companies reporting the revenue and into the two that have none to report.
The setup
Where it stands — Ultralife and Ideal Power carried the group's month while Vicor, Bel Fuse and Navitas fell despite two beat-and-raise quarters. Would confirm — Bel Fuse third-quarter sales landing at or above the $205-225m guided range with gross margin holding 39-41%. Would invalidate — Vicor's one-year backlog falling below $379.7m, or book-to-bill dropping under 1.0. Watch next — Ideal Power's hyperscaler circuit-breaker prototypes, due at the end of the fourth quarter of 2026. Valuation — Vicor is at 33.9x trailing gross profit and 26.6x forward, against 43.8x in May and 9.1x a year ago.