

FactSet, Cast as AI's First Casualty, Is Buying Faster Sales Growth With Its Margin
Prompt v1.5
The seat-billed financial data terminal was supposed to be the first thing artificial intelligence deleted. FactSet, which rents that terminal to analysts for roughly $12,000-24,000 a year, instead reported a fifth straight quarter of accelerating subscription growth — organic annual subscription value up 7.1% to $2.49bn — with client and user counts rising and full-year guidance raised, not cut. The catch sits below the top line: operating margin fell from 33.2% to 26.7% as the company spent into its own AI products, so demand is being bought rather than harvested.
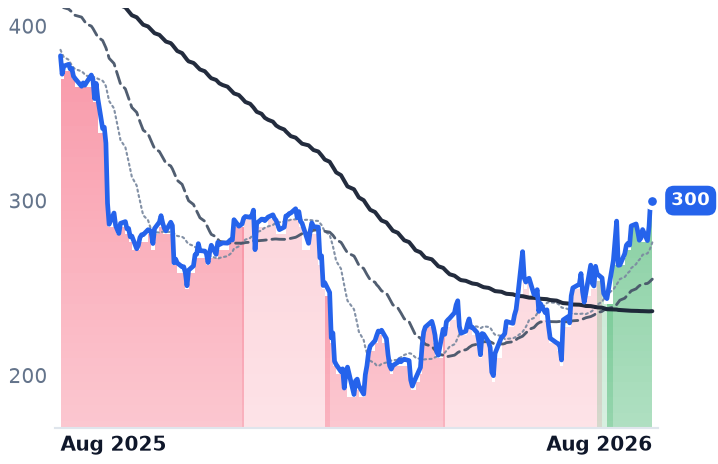
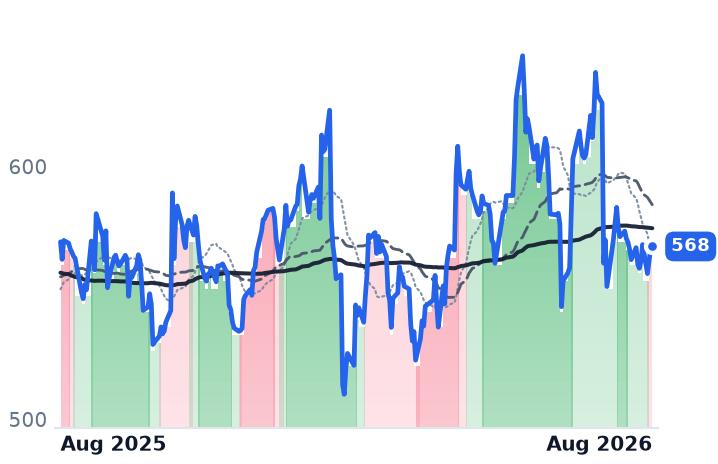
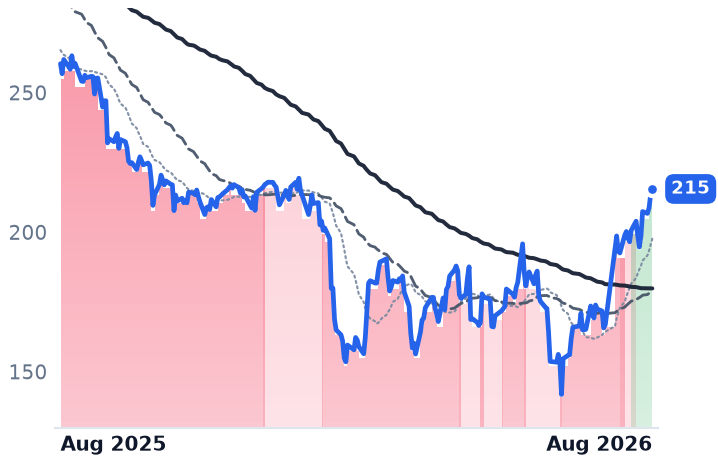
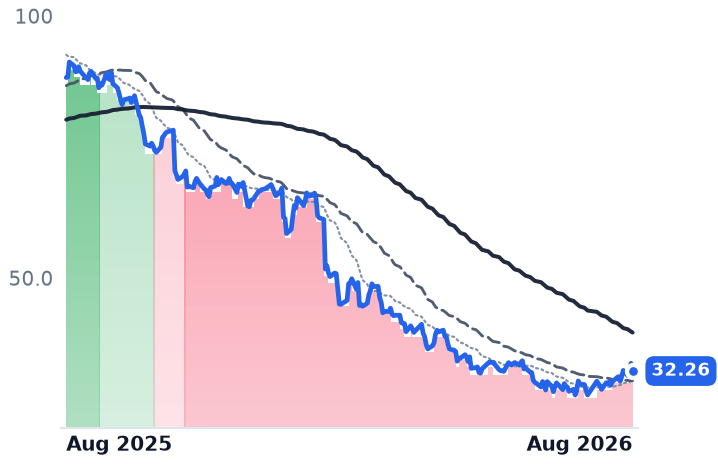
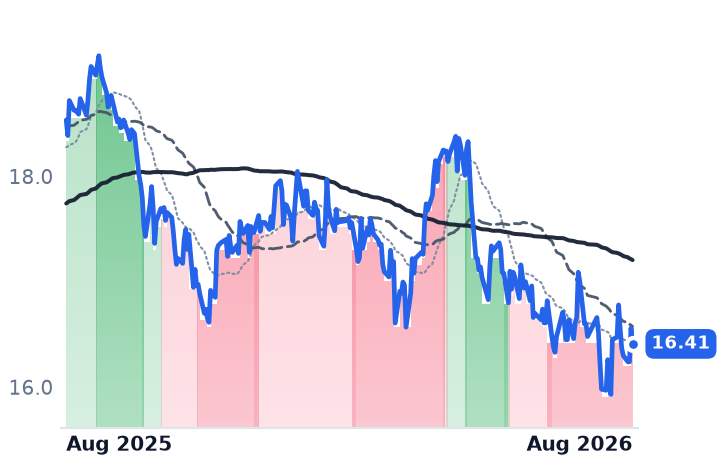
The three big investment-data vendors are not one trade. FactSet and Morningstar, both billed by subscription, have rallied hard off May lows; MSCI, which earns a royalty on $2.8trn of exchange-traded fund assets tracking its indices, posted the best numbers of the three — revenue up 12.2%, a 56.2% operating margin — and fell 9% in a month on an expense forecast. Morningstar's growth engine turns out to be credit ratings, not data.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
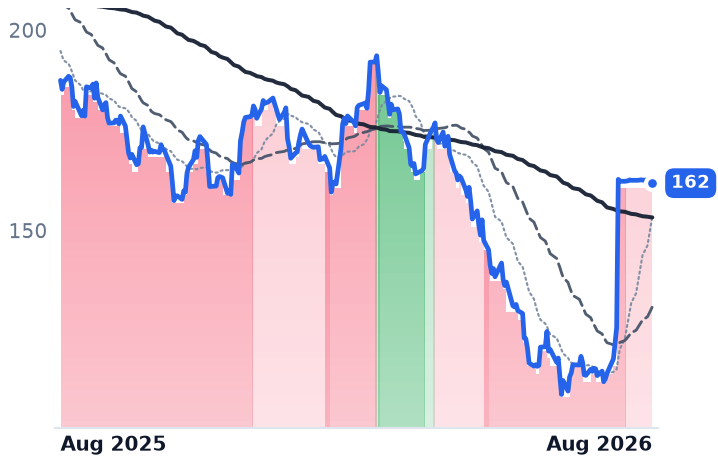
FDS | FactSet Research Systems | Investment Intelligence | 🌱 Emerging Bull | +21.5% | −21.7% |
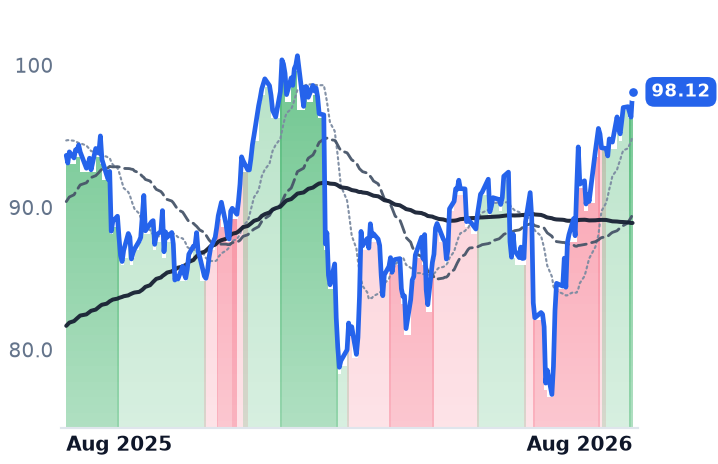
MSCI | MSCI | Investment Intelligence | 🟢 Cont. Bull | +1.2% | −0.3% |
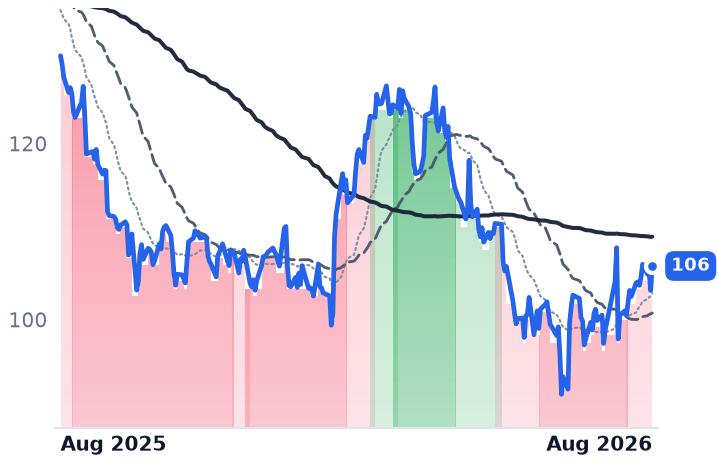
MORN | Morningstar | Investment Intelligence | 🔴 Cont. Bear | +30.1% | −17.2% |
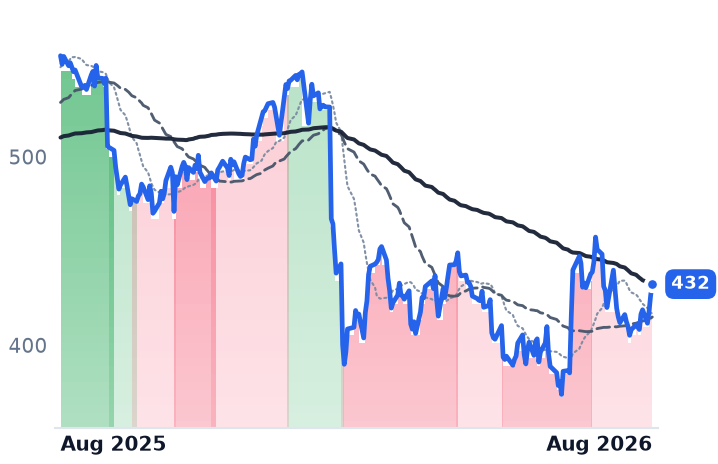
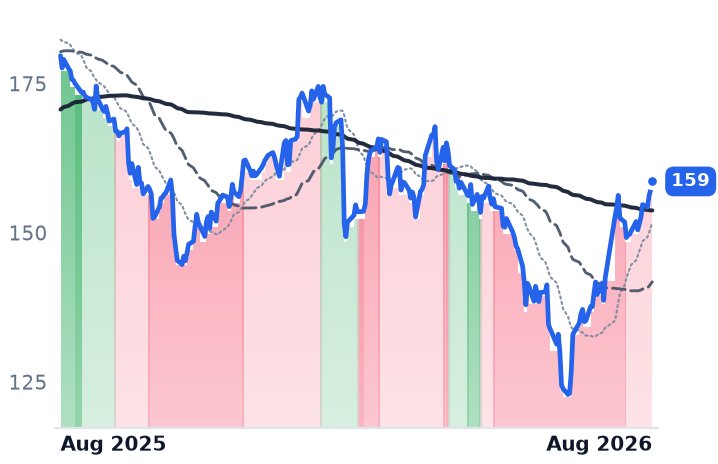
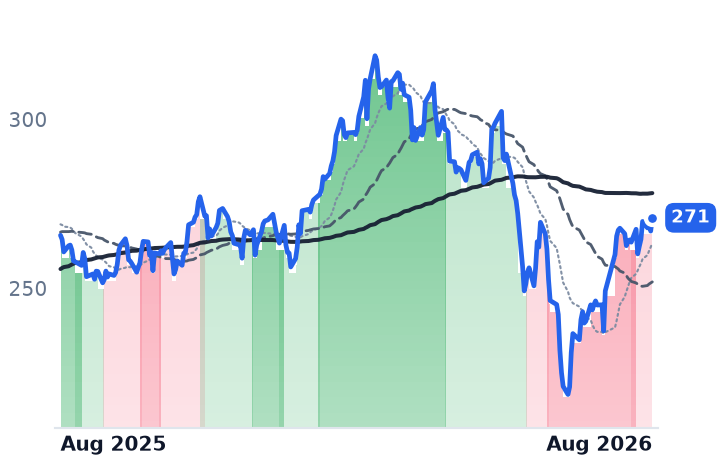
SPGI | S&P Global | Credit Ratings | 🔴 Cont. Bear | +0.3% | −21.9% |
CSGP | CoStar | Real Estate Data Platforms | 🔴 Cont. Bear | +13.2% | −63.4% |
STWD | Starwood Property Trust | Commercial Real Estate Finance | 🔴 Cont. Bear | −1.1% | −11.5% |
ICE | Intercontinental Exchange | Derivatives Trading Venues | 🔴 Cont. Bear | +14.4% | −11.7% |
CME | CME | Derivatives Trading Venues | ⚠️ Emerging Bear | +14.1% | +1.9% |
MKTX | MarketAxess | Institutional Trading Platforms | 🔴 Cont. Bear | +44.1% | −13.7% |
NDAQ | Nasdaq | Equity Exchange | ⚠️ Emerging Bear | +8.7% | +4.8% |
TW | Tradeweb Markets | Institutional Trading Platforms | 🔴 Cont. Bear | +9.1% | −18.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FDS | $11.6B | 22.4x | 16.7x | 4.7x | 4.4x | 9.2x | 8.7x | 14.1x | 6.1% |
MSCI | $46.6B | 34.1x | 32.5x | 13.6x | 13.2x | 16.4x | 16.0x | 25.1x | 3.3% |
MORN | $9.1B | 21.2x | 18.6x | 3.5x | 3.4x | 5.5x | 5.4x | 12.1x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPGI | $139.6B | 28.6x | 26.9x | 8.8x | 9.4x | 12.4x | 13.2x | 17.9x | 4.0% |
CSGP | $13.1B | 176.3x | 23.8x | 3.7x | 3.5x | 4.8x | 4.6x | 31.1x | 2.4% |
STWD | $6.0B | 24.3x | 9.8x | 3.0x | 2.8x | 3.9x | 3.7x | 16.6x | 7.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ICE | $87.3B | 21.9x | 19.2x | 6.5x | 7.9x | 8.9x | 10.8x | 15.3x | 5.6% |
CME | $99.2B | 23.3x | 22.5x | 14.7x | 14.1x | 17.9x | 17.3x | 18.7x | 4.2% |
MKTX | $5.8B | 19.4x | 20.7x | 6.7x | 6.5x | 9.9x | 9.6x | 12.6x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NDAQ | $51.4B | 26.5x | 22.3x | 5.9x | 8.7x | 9.9x | 14.7x | 18.8x | 3.8% |
TW | $22.1B | 24.8x | 25.9x | 10.0x | 9.4x | 14.7x | 13.9x | 13.3x | 4.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FDS | Revenue | +6.7% | +6.1% | +6.0% |
| EPS | +4.5% | +10.2% | +10.4% | |
MSCI | Revenue | +12.4% | +9.0% | +8.7% |
| EPS | +14.3% | +14.3% | +13.6% | |
MORN | Revenue | +10.1% | +5.8% | +5.8% |
| EPS | +39.1% | +14.0% | +13.9% | |
SPGI | Revenue | −2.9% | +5.4% | +7.1% |
| EPS | +6.1% | +12.5% | +12.8% | |
CSGP | Revenue | +15.3% | +10.3% | +11.5% |
| EPS | +62.3% | +25.4% | +26.9% | |
STWD | Revenue | +13.4% | +8.8% | −22.1% |
| EPS | −1.3% | +14.9% | +1.4% | |
ICE | Revenue | +11.5% | +5.8% | +6.5% |
| EPS | +17.0% | +8.8% | +11.9% | |
CME | Revenue | +7.7% | +5.1% | +6.5% |
| EPS | +9.6% | +5.5% | +7.3% | |
MKTX | Revenue | +5.6% | +6.8% | +7.3% |
| EPS | +8.3% | +9.2% | +10.7% | |
NDAQ | Revenue | +12.9% | +8.9% | +8.5% |
| EPS | +20.0% | +13.6% | +13.3% | |
TW | Revenue | +14.0% | +11.8% | +10.2% |
| EPS | +16.7% | +13.8% | +13.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
FactSet Research Systems sells the workstation an equity analyst opens each morning: data, models, screens and order workflows, billed per seat at roughly $12,000 to $24,000 a year. That is comfortably below a Bloomberg Terminal's roughly $32,000 per user, and it is precisely the product a competent AI research assistant is supposed to render unnecessary. That fear drove the Norwalk, Connecticut company's shares to multi-year lows earlier this year.
The disclosures point the other way. Organic annual subscription value — the contracted run-rate, the only clean demand measure for a business billed in seats — reached $2.49bn at 31 May, up 7.1%, the fifth consecutive quarter in which that growth rate accelerated. Retention held above 95%, and enterprise renewals lengthened by 30% on average in the quarter. Users and clients rose rather than shrank: 241,352 users at the end of February, a net 1,489 more in three months, plus 98 net new clients. Management raised the fiscal 2026 subscription-value target on 31 March, to $130-160m of net additions from $100-150m, and reaffirmed it on 1 July.
The bill arrives on the margin line
What FactSet is not doing is converting that demand into profit. Quarterly revenue grew 6.4% to $622.9m; operating income fell 14.3%. Operating margin went from 33.2% to 26.7% and gross margin from 52.1% to 49.9%, the arithmetic of embedding AI features into a product whose price per seat cannot rise as fast as the cost of running it. More than 90% of FactSet's fifty largest clients now use four or more of its AI products — adoption that shows up in the subscription line and in the cost line, not yet in earnings.
The shares have repaired about half the de-rating. Against consensus fiscal 2026 earnings of $17.79 a share, FactSet traded at 21.0x a year ago, 11.9x at its 15 May low and 16.9x now — still a fifth below where it started. Consensus models 6.5% revenue growth this year, below the organic subscription growth just reported, an unusual position for a company the market has been treating as structurally impaired. The average sell-side target has been cut toward $305 even as the stock rose to $301.59; Jefferies lifted its target to $253 and kept a Hold.
The one with the best numbers fell
MSCI licenses the benchmarks that index funds are built on, so it is paid a fee on assets, not on analysts. Its asset-based fee run rate hit a record $948m, up 25%, on roughly $40bn of second-quarter ETF inflows and $2.8trn of ETF assets tracking its indices. Revenue grew 12.2% to $867m at a 56.2% operating margin — the strongest of the three by both measures. The shares fell 10.1% in the 21 July session anyway, because the company raised its full-year expense guidance to $1,340-1,370m from $1,305-1,335m for the First Street acquisition and incentive pay. That single day is the entire month's decline. The result is a stock unchanged over twelve months on a forward multiple of 28.8x, identical to a year ago, while consensus 2026 earnings for it rose about 14% — a full year of growth accruing to the holder as nothing. Trailing, 31x compares with a ten-year average near 41.6x. The soft spot is sustainability data, where management guided net new sales to roughly zero for two quarters; private-assets subscriptions are growing past 16%.
Morningstar, the smallest at $8.0bn, is the one whose improvement is real and whose source is misread. Revenue rose 9.6% to $663.2m and operating margin widened from 20.7% to 24.2%. But Morningstar Credit — the DBRS ratings business — grew 23.4% to $104.9m on structured-finance issuance and supplied about a third of all revenue growth from a sixth of revenue, while PitchBook, its seat-billed private-markets platform, grew 4.9% amid corporate churn. The fastest-improving investment-data company is being carried by the debt-issuance cycle.
What the month actually was
Morningstar's 24% month is one gap: the sessions spanning its 28 July results moved the stock 16.4%, and stripping that plus its next-best day leaves about 2%. FactSet's is not — it round-tripped a July spike, then built 14.6% through August, and even without its two best August sessions retains roughly 4% of drift. On 19 August, when FactSet gained 5.7% with no company news beyond a routine $1.16 dividend, thirty-year Treasury yields fell 10 basis points to 5.18% and the S&P 500 rose 0.4%. That is multiple repair on a long-duration subscription stream, not a fresh disclosure.
Underneath all three, the industry pool is still growing: global spending on financial market data rose 6.5% to a record $49.2bn in 2025, with AI integration cited as a driver of demand rather than a substitute for it.
The setup
Where it stands — FactSet's subscription growth is accelerating while its margin compresses; MSCI's numbers are the group's best and its shares the worst. Would confirm — FactSet's fiscal fourth-quarter organic subscription value growth prints at or above 7.1% in September. Would invalidate — Adjusted operating margin lands below the reaffirmed 34-35.5% range, or client and user counts turn negative. Watch next — FactSet reports fiscal fourth-quarter and full-year results in late September; MSCI reports third-quarter results in October. Valuation — FactSet 19.5x trailing and 16.9x forward, against 21.0x on the same estimate a year ago and 11.9x in May.