

Appalachian Gas Producers Beat on Volumes and Lost on Price
Prompt v1.3
Three Appalachian shale gas producers — EQT, Range Resources and Expand Energy — reported second-quarter results in which volumes came in above guidance and spending below it, and each followed with a corporate action: EQT signed a 10-year, 325 million cubic feet a day contract to fuel a 2-gigawatt power plant, Expand agreed to buy gas marketer Twin Eagle for $1.25bn and repurchased about 4% of its stock, and Range beat consensus earnings by 21%.
The commodity did the opposite. Front-month Henry Hub gas fell to $2.78 per million British thermal units, and the Energy Information Administration now forecasts a record 3,985 billion cubic feet in storage at end-October, 5% above the five-year average.
The fundamentals split. Only Range grew revenue, up 19.1% with operating margin widening to 39.1% from 26.8%; EQT's revenue fell 29.2%. And the same consensus that models 40%-plus earnings growth this year models an earnings decline in 2027 for all three.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
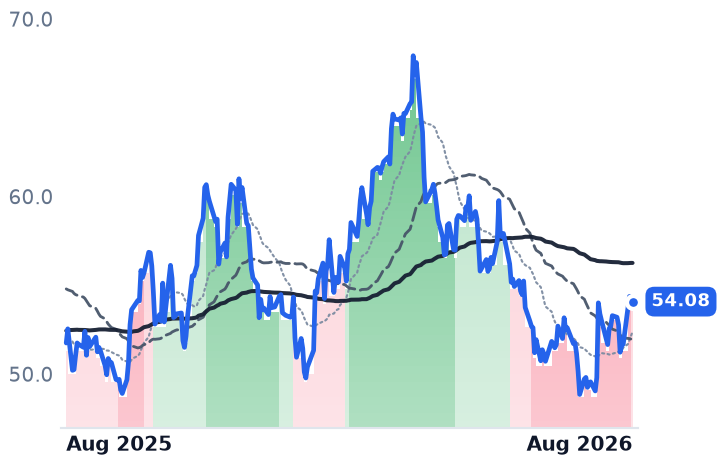
EQT | EQT | Appalachian Shale | ⚠️ Emerging Bear | +10.5% | +5.2% |
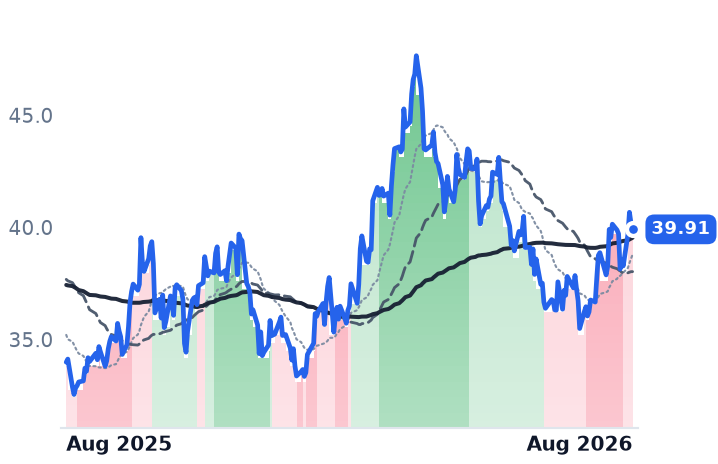
RRC | Range Resources | Appalachian Shale | ⚠️ Emerging Bear | +11.8% | +18.6% |
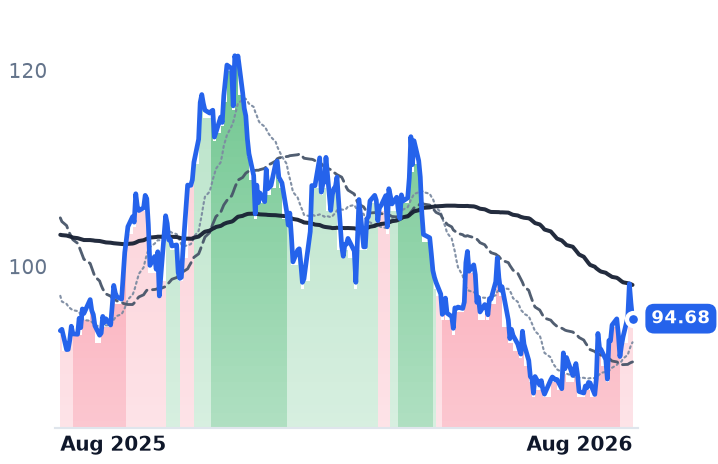
EXE | Expand Energy | Appalachian Shale | 🔴 Cont. Bear | +8.2% | +1.4% |
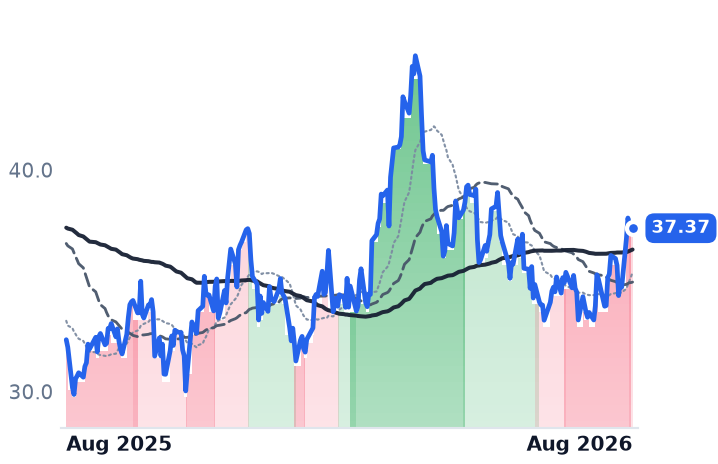
AR | Antero Resources | Appalachian Shale | 🔴 Cont. Bear | +11.3% | +15.6% |
CNX | CNX Resources | Appalachian Shale | 🔴 Cont. Bear | +7.4% | +24.4% |
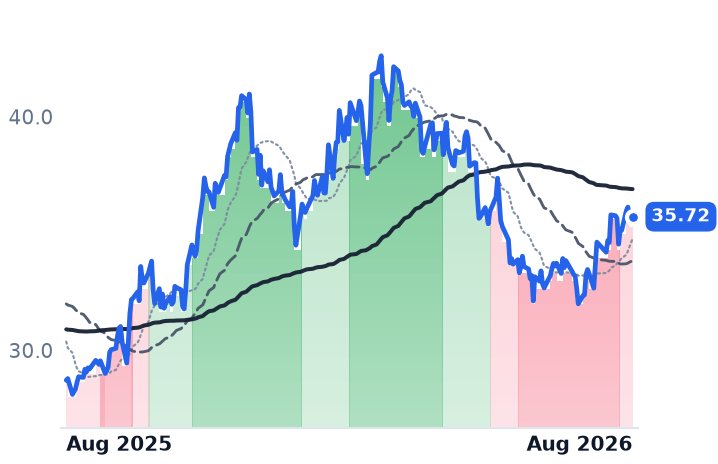
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EQT | $31.4B | 11.0x | 12.4x | 3.4x | 3.4x | 4.9x | 5.0x | 6.0x | 12.0% |
RRC | $8.9B | 10.5x | 9.3x | 2.7x | 2.5x | 5.6x | 5.3x | 7.0x | 13.1% |
EXE | $19.4B | 7.2x | 9.8x | 1.5x | 1.5x | 2.3x | 2.3x | 3.4x | 13.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AR | $10.4B | 9.6x | 7.9x | 1.8x | 1.5x | 7.1x | 5.9x | 6.3x | 13.6% |
CNX | $4.7B | 4.6x | 9.9x | 1.9x | 1.9x | 3.9x | 3.9x | 3.7x | 11.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EQT | Revenue | +9.9% | −0.8% | +11.9% |
| EPS | +37.2% | −5.4% | +40.3% | |
RRC | Revenue | +17.9% | +2.5% | +8.0% |
| EPS | +41.2% | −4.0% | +20.2% | |
EXE | Revenue | +14.7% | −4.1% | +6.9% |
| EPS | +43.3% | −1.6% | +24.1% | |
AR | Revenue | +31.0% | −0.1% | +8.3% |
| EPS | +135.1% | +3.9% | +26.9% | |
CNX | Revenue | +17.1% | −9.3% | +7.0% |
| EPS | +45.0% | +30.6% | +22.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Volumes up, spending down
EQT, the largest natural gas producer in the United States, with roughly 2 million gross acres concentrated in the Marcellus shale of Appalachia, sold 634 billion cubic feet equivalent in the second quarter — above the top end of its own guidance — on capital spending of $666m, 9% below the bottom end. It generated $330m of free cash flow at a realised price of $2.89 per million British thermal units (MMBtu), raised full-year production guidance by about 90 Bcfe and cut capital spending guidance by $25m. It also signed a 10-year deal to supply 325 million cubic feet a day to Competitive Power Ventures' 2-gigawatt Shay Energy Center in West Virginia from 2031 — priced off PJM wholesale power rather than a gas index, and worth roughly $100m of annual free cash flow at strip. Its quarterly realised differential to Henry Hub was $(0.67) per thousand cubic feet, better than guided despite basis widening.
Range Resources, the smallest of the three with about 794,000 net acres and a $9.3bn market value, earned an adjusted $0.79 a share against $0.65 consensus on revenue of $834m, having spent only 33% of its annual capital budget by mid-year. It tightened basis guidance to $0.35–$0.40 below Henry Hub and lifted its natural gas liquids premium guidance to $2.50 a barrel over the Mont Belvieu benchmark. Production of 2.3 billion cubic feet equivalent a day is tracking to 2.6 Bcfe/d by end-2027.
Expand Energy, formed from the Chesapeake–Southwestern merger in 2024 and holding about 5,000 wells across the Marcellus and the Louisiana Haynesville, agreed to buy gas marketer Twin Eagle for $1.25bn, repurchased $850m of stock — roughly 4% of its float — and authorised another $1bn, with management framing the buying against a $3.50–$4.00 per thousand cubic feet mid-cycle view and a $2.70 breakeven. It still has no permanent chief executive; Mike Wichterich remains interim.
The gas market moved against them
None of this was a commodity rally. Front-month Henry Hub fell to $2.78/MMBtu, down 4.3% over the month, with Lower 48 dry gas output at a record 110.6 Bcf/d. The EIA expects prices below $3.00 until November and a record 3,985 Bcf in storage at end-October, 5% above the 2021-25 average. Liquefied natural gas export demand weakened too: feedgas to the nine major plants averaged 16.9 Bcf/d in August against a year-to-date 18.85, on Freeport maintenance, though analysts see flows near 22 Bcf/d by year-end. What did improve is local: Appalachian seasonal basis strips for winter 2026/27 through winter 2027/28 each hit all-time highs, and 8.8 gigawatts of behind-the-meter gas generation is in development in Pennsylvania alone.
One business confirms, two contradict
Range is the only member with revenue growth and margin expansion: revenue up 19.1% year on year, operating margin 39.1% against 26.8%. EQT's revenue fell 29.2% and operating margin compressed to 25.1% from 44.3%; Expand's revenue fell 19.7% with margin at 22.3% from 34.4%, though gross profit rose 64.7%. Volumes rose at all three; price did the damage. Verdict on the business: CONFIRMS at Range, CONTRADICTS at EQT and Expand.
Valuation splits the same way. Expand trades at 3.75x trailing enterprise value to EBITDA, 1.16x book and an 11.6% free-cash-flow yield — a wide discount to EQT's 6.36x for a comparable asset base. Range is the only one whose forward price/earnings ratio (9.72x) sits below trailing (10.96x). EQT's forward 12.78x sits above its trailing 11.89x, because consensus 2026 earnings of $4.23 are below the trailing year. Consensus targets imply roughly 25-30% above EQT's $53.88 close, about 36% above Expand's $95.25, and only 11% above Range's $39.78 on a neutral rating. The catch: the same models show 2027 earnings falling 5.2%, 3.5% and 4.4% respectively before a 2028 recovery of 15-32%. Verdict on valuation: CONFIRMS for Expand, INCONCLUSIVE for EQT.
The tape agreed only partially. Between 5 and 12 August all three, plus peers CNX Resources and Antero Resources, moved out of their deepest downtrend reading into a milder one — 50-day averages still below 200-day, a less-bad downtrend rather than an uptrend. All three were in uptrends as recently as May and June before de-rating through the summer.
The setup
Where it stands — Company-specific news, not gas prices, drove August gains; only Range's income statement supports it.
Would confirm — LNG feedgas returning above 20 Bcf/d and end-October storage printing below the forecast 3,985 Bcf.
Would invalidate — 2027 consensus earnings cut further from $4.01 (EQT), $3.96 (Range), $8.75 (Expand).
Watch next — Expand's Twin Eagle close, expected in the third quarter, and its permanent CEO appointment.
Valuation — Expand 3.75x trailing EV/EBITDA versus EQT's 6.36x; EQT's 12.78x forward P/E exceeds its 11.89x trailing.