

Rotation Lifted Five Outsourcers 12%; Only Two Earned It
Prompt v1.2
Five companies that rent out human labour and data to other businesses — call-centre floors, insurance back offices, shopper panels, artificial-intelligence training data — jumped an average 11.6% in a month. Almost all of it landed in six sessions in late July, when money rotated out of chip stocks and into anything de-rated and services-shaped.
The earnings that followed split the group. ExlService, which runs analytics and claims operations for insurers, grew revenue 15.6% and raised full-year guidance to $2.39–2.415bn. Genpact, the finance-and-accounting outsourcer, grew 7.1% with its technology unit up 24.1% — and fell 5.17% the next session. Concentrix, the largest contact-centre operator, bounced 20% while its operating income fell 35.7% and it cut earnings guidance.
And Innodata, the one name whose revenue is growing 58%, is the only member down over the month, and is roughly half its June price.
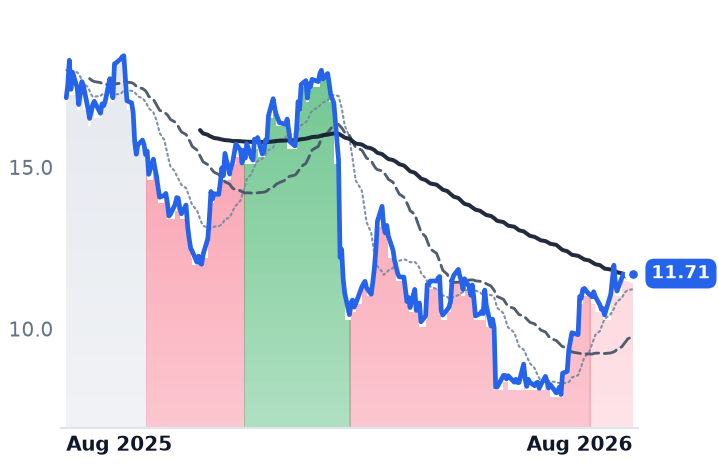
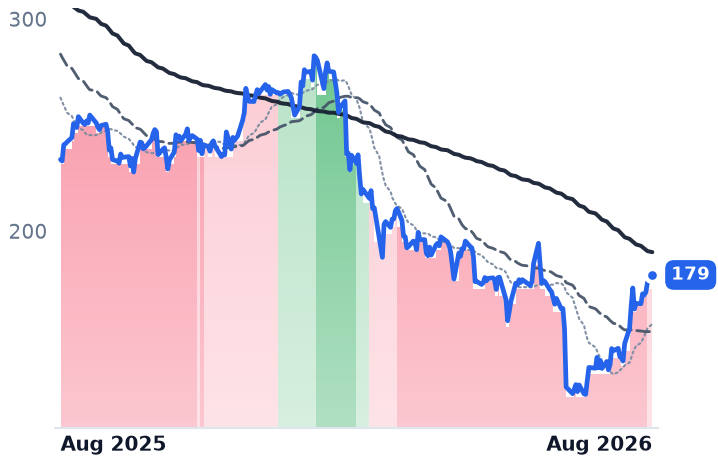
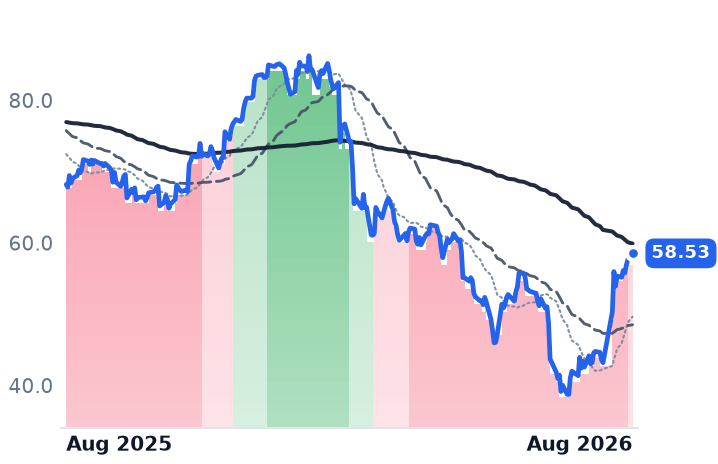
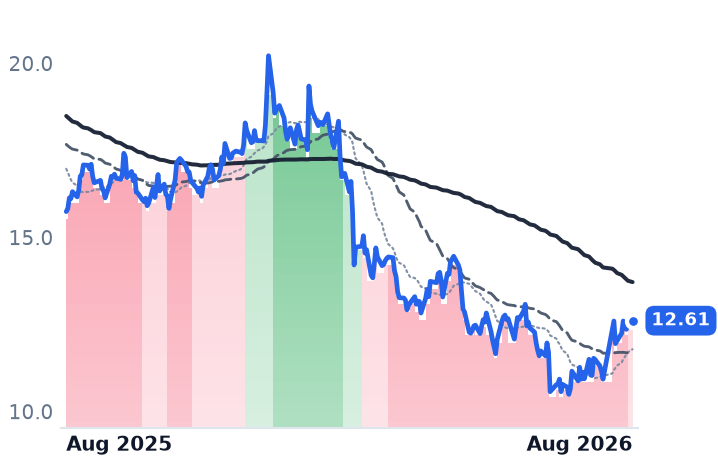
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
CNXC | Concentrix | Customer Experience & Operations | 🔴 Cont. Bear | +3.9% | −42.9% |
EXLS | ExlService | Customer Experience & Operations | 🔴 Cont. Bear | +23.4% | −16.4% |
G | Genpact | Consulting & Professional Services | 🔴 Cont. Bear | +12.5% | −20.0% |
INOD | Innodata | Research & Analytics Services | 🌱 Emerging Bull | −5.4% | +60.8% |
NIQ | NIQ Global Intelligence | Data, Analytics & Intelligence | 🔴 Cont. Bear | +5.8% | −31.7% |
ACN | Accenture | Consulting & Professional Services | 🔴 Cont. Bear | +29.5% | −23.3% |
CTSH | Cognizant Technology Solutions | Consulting & Professional Services | 🔴 Cont. Bear | +32.5% | −14.2% |
INFY | Infosys | Consulting & Professional Services | 🔴 Cont. Bear | +9.7% | −19.9% |
TCS.NS | Tata Consultancy Services | Information Technology Services | 🔴 Cont. Bear | +11.2% | −18.5% |
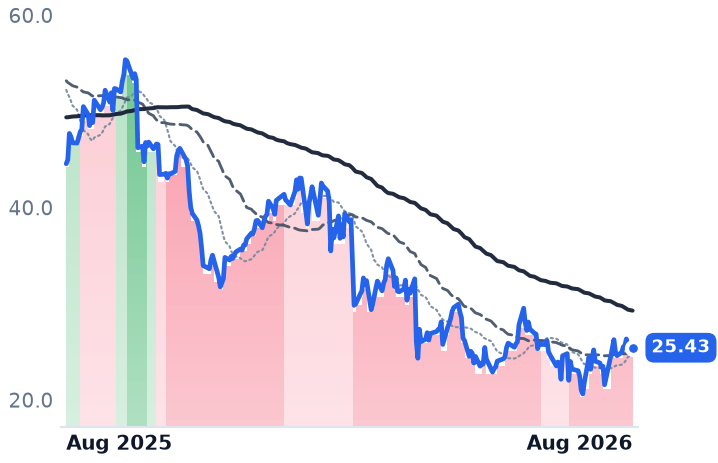
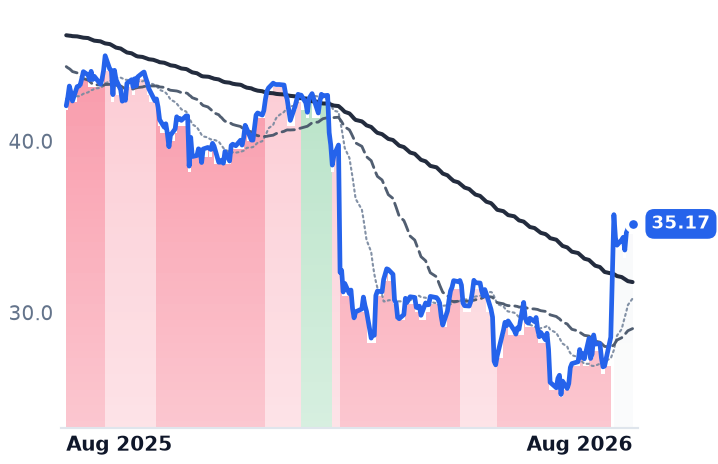
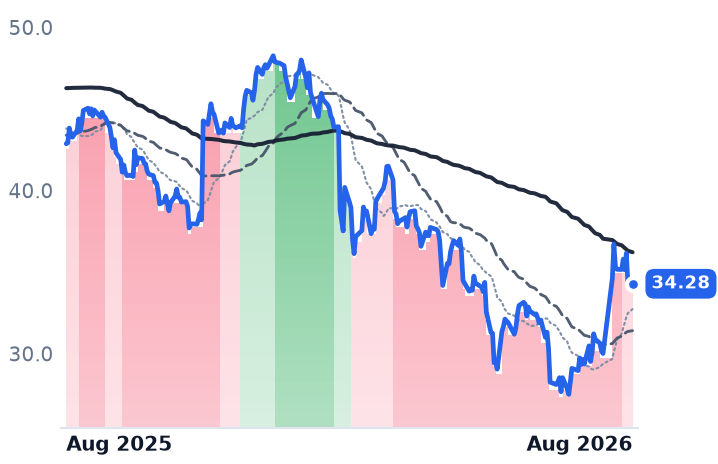
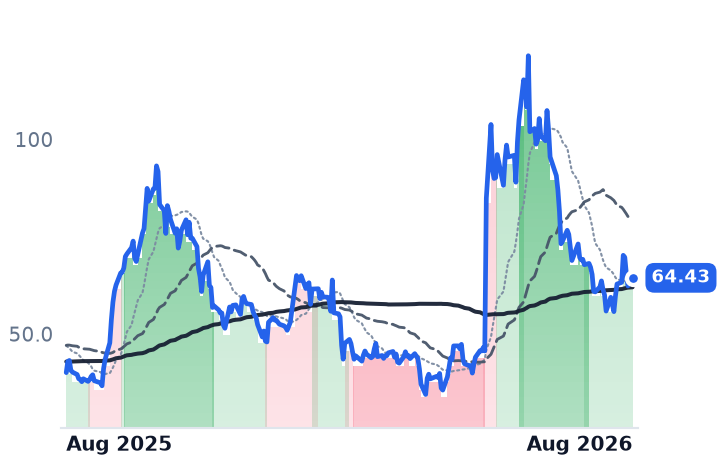
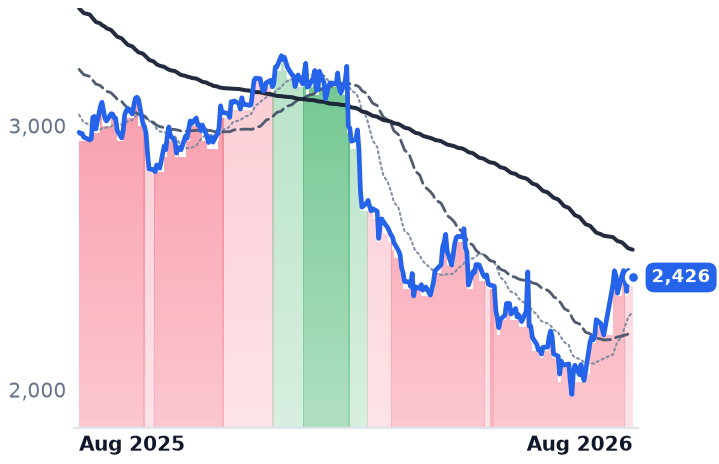
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CNXC | $1.9B | n/m | 2.7x | 0.2x | 0.2x | 0.6x | 0.6x | n/m | 31.0% |
EXLS | $6.5B | 25.7x | 18.3x | 2.8x | 2.7x | 7.2x | 7.0x | 15.9x | 4.2% |
G | $7.0B | 11.9x | 10.0x | 1.3x | 1.3x | 3.5x | 3.5x | 7.7x | 5.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
INOD | $2.1B | 44.7x | 59.1x | 6.6x | 5.8x | 15.4x | 13.7x | 27.4x | 10.5% |
NIQ | $5.2B | n/m | 17.8x | 1.2x | 1.2x | 2.3x | 2.2x | 12.1x | 7.7% |
ACN | $154.0B | 19.1x | 17.7x | 2.1x | 2.0x | 6.5x | 6.2x | 11.6x | 7.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CTSH | $28.9B | 11.8x | 11.2x | 1.3x | 1.3x | 4.1x | 4.1x | 7.2x | 8.2% |
INFY | $50.7B | 20.9x | 15.6x | 3.4x | 2.5x | 11.3x | 8.2x | 14.6x | 5.3% |
TCS.NS | $9.1T | 17.5x | 16.3x | 3.2x | 3.1x | 9.0x | 8.7x | 12.3x | 5.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | FY2029E | |
|---|---|---|---|---|---|
CNXC | Revenue | +0.4% | −0.3% | +1.1% | — |
| EPS | −2.8% | +4.2% | +2.3% | — | |
EXLS | Revenue | +17.3% | +12.9% | +11.0% | — |
| EPS | +23.1% | +12.8% | +14.5% | — | |
G | Revenue | +7.2% | +7.1% | +7.9% | — |
| EPS | +13.9% | +9.4% | +10.7% | — | |
INOD | Revenue | +43.5% | +28.4% | — | −64.1% |
| EPS | +23.0% | +60.1% | — | −53.9% | |
NIQ | Revenue | +7.1% | +5.1% | +5.0% | — |
| EPS | +220.5% | +23.4% | +20.2% | — | |
ACN | Revenue | +6.0% | +5.3% | +5.1% | — |
| EPS | +7.6% | +5.9% | +8.7% | — | |
CTSH | Revenue | +4.8% | +3.8% | +4.3% | — |
| EPS | +11.2% | +8.6% | +7.9% | — | |
INFY | Revenue | +1.6% | +5.4% | +3.2% | — |
| EPS | +2.4% | +5.3% | +4.5% | — | |
TCS.NS | Revenue | +4.0% | +10.1% | +4.6% | — |
| EPS | +4.0% | +9.0% | +4.0% | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
These five companies sell the same underlying thing in different wrappers: other people's work. Concentrix, based in Fremont, California, runs outsourced customer-service and back-office operations with 455,000 employees. Genpact, spun out of General Electric and now registered in Bermuda, runs finance, procurement and supply-chain operations for large corporates with 145,000 staff. ExlService handles claims, underwriting and analytics for insurers and healthcare payers. NIQ Global Intelligence sells consumer-measurement and shopper-panel data to brands. Innodata, the outlier, labels and curates the training data that large language models are built on — it is paid to build the software that could eventually delete the seats the other four bill for.
The gain has a date stamp
Almost the entire monthly move landed between 22 and 29 July. Concentrix rose 11.9% on 27 July; Genpact rose 15.3% into 28 July and 6.1% more the next day; NIQ rose 6.1% on 27 July; ExlService went from $28.56 to $35.71 in two sessions. The trigger was not company news. Jefferies upgraded Indian information-technology services from underweight to neutral on 27 July on explicitly tactical grounds, still forecasting only low-to-mid single-digit revenue growth through fiscal 2028. In the same month India's Nifty IT index gained 16.7% while the Philadelphia semiconductor index fell 21%, the widest monthly gap since 1999, as funds rotated out of crowded artificial-intelligence chip positions. Since 29 July the group has given ground: Genpact −6.6%, NIQ −2.4%, ExlService −2.3%, Concentrix −2.1%.
Two businesses are confirming
ExlService is the cleanest. Revenue growth has accelerated four straight quarters — 12.2%, 12.7%, 13.8%, 15.6% — to $594.8m, gross profit grew faster than revenue at 16.4%, and management raised full-year guidance to $2.39–2.415bn with data- and AI-led services at 61% of revenue. The blemish: operating margin fell from 15.77% to 14.68% and net income declined 2.3%. At 14.96x forward earnings against 21.53x trailing — and roughly 27.6x trailing at the end of 2025 — the de-rating is real. Business verdict: CONFIRMS. Valuation: CONFIRMS.
Genpact is the divergence. Second-quarter revenue rose 7.1% to $1.343bn, adjusted earnings per share 13.6%, and Advanced Technology Solutions revenue 24.1% to 27% of the total, with full-year growth guidance for that unit lifted to at least 25% from at least 20%. Gross margin widened to 36.50% from 35.88%. The stock fell 5.17% the following session. It trades at 8.42x forward and 10.09x trailing earnings, 7.52x enterprise value to EBITDA, with a 9.8% free-cash-flow yield — against roughly 14.9x trailing at the end of 2025, on higher earnings. Business verdict: CONFIRMS; the tape does not.
Two are contradicting, in opposite directions
Concentrix bounced 20% on deteriorating numbers. Revenue growth decelerated to 1.9%, gross profit fell 2.9%, operating income fell 35.7% and operating margin halved to 3.88%. Management cut full-year adjusted earnings guidance to $10.83–11.18 from $11.48–12.07, citing a three-point revenue drag from clients moving work offshore faster than planned. It carries a $1,523.3m goodwill write-off against the $4.8bn Webhelp acquisition and 3.2x leverage. At 2.27x forward earnings, 0.56x book and a 33.7% free-cash-flow yield, the market is priced for terminal decline; the quarter did not refute it. Business: CONTRADICTS.
Innodata is the inverse. Second-quarter revenue rose 58% to a record $92.1m with 49% adjusted gross margin and adjusted EBITDA up 92%, full-year growth guidance of 40%-plus reiterated, and largest-customer concentration down to 37% from 56%, alongside an announced chief-executive transition. The shares are down roughly 49% from their 4 June peak. At 58.6x forward earnings and 5.79x forward sales, the de-rating is of the multiple, not the business.
NIQ is unresolved: first-quarter revenue grew 1.3% with a $90.1m net loss, $3.2bn net debt at 3.4x leverage and reaffirmed 5.0–5.3% organic growth guidance. Second-quarter results are due after the close on 10 August. INCONCLUSIVE.
On the tape, ExlService and NIQ cleared their downtrends on 28 July and Genpact on 3 August, its 50-day average turning up. Concentrix never repaired — it remains in its steepest downtrend despite the bounce — and Innodata was downgraded twice, on 10 and 28 July.
The setup
Where it stands — A late-July rotation lifted all five; only ExlService and Genpact have earnings that match the move. Would confirm — Genpact recovering the 5.17% post-earnings drop and holding above its 50-day average through September. Would invalidate — Concentrix's next quarter showing revenue growth below 1.9% or further cuts to $10.83–11.18 guidance. Watch next — NIQ's second-quarter results after the close on 10 August 2026, against 5.0–5.3% organic growth guidance. Valuation — Genpact 8.42x forward vs 10.09x trailing and ~14.9x at end-2025; Innodata 58.6x forward.