

Fiserv Cut Guidance 11% Below Consensus While Seven Peers Rose 9.5%
Prompt v1.2
Fiserv, which processes card payments and runs the Clover checkout system for small merchants, told investors on 6 August that revenue fell 5% on a like-for-like basis last quarter and cut its full-year adjusted profit forecast to $7.20-$7.40 a share. The stored analyst consensus still reads $8.11 — roughly 11% above what management now guides.
That sits oddly against a group of eight payments and bank-software stocks that rose about 9.5% in the past month. The businesses do not tell one story. Fiserv's operating margin fell to 16.7% from 27.2% a year earlier, and NCR Voyix is burning cash. But Broadridge, which runs proxy voting and shareholder communications for brokers, grew recurring revenue 8%, lifted its dividend 12% and still trades at about 16 times forward earnings against 27.8 times a year ago.
Only one of the eight has actually re-established an uptrend.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
BR | Broadridge Financial Solutions | Fintech Solutions | 🔴 Cont. Bear | +12.9% | −35.9% |
FIS | Fidelity National Information Services | Fintech Solutions | 🔴 Cont. Bear | +1.9% | −37.5% |
FISV | Fiserv | Fintech Solutions | 🔴 Cont. Bear | +3.9% | −60.4% |
FLYW | Flywire | Payment Processing & Solutions | 🟢 Cont. Bull | +0.9% | +52.5% |
JKHY | Jack Henry & Associates | Fintech Solutions | 🔴 Cont. Bear | +3.7% | −0.6% |
PAY | Paymentus | Payment & Fintech Infrastructure | 🔴 Cont. Bear | +36.6% | +12.9% |
VYX | NCR Voyix | Fintech Solutions | 🔴 Cont. Bear | +2.4% | −32.9% |
WAY | Waystar | Revenue Cycle & Finance | 🔴 Cont. Bear | +8.0% | −29.7% |
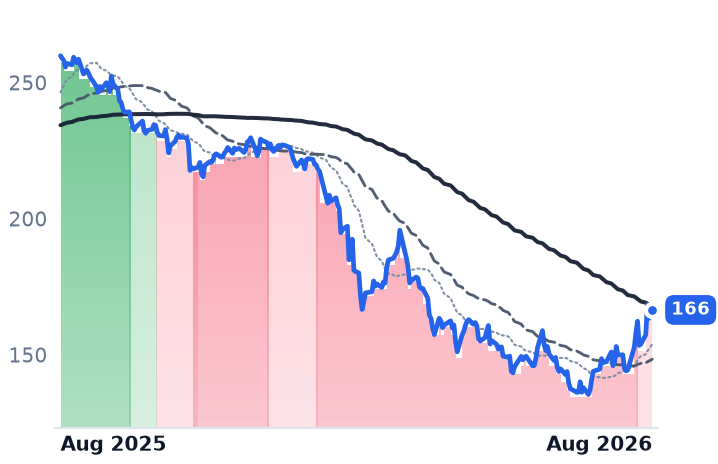
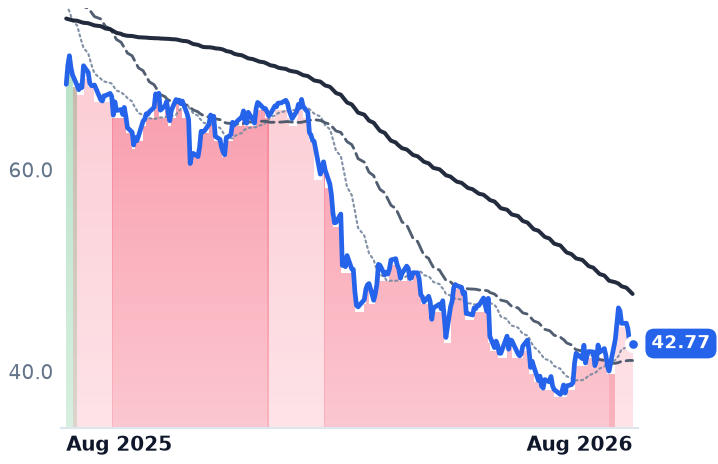
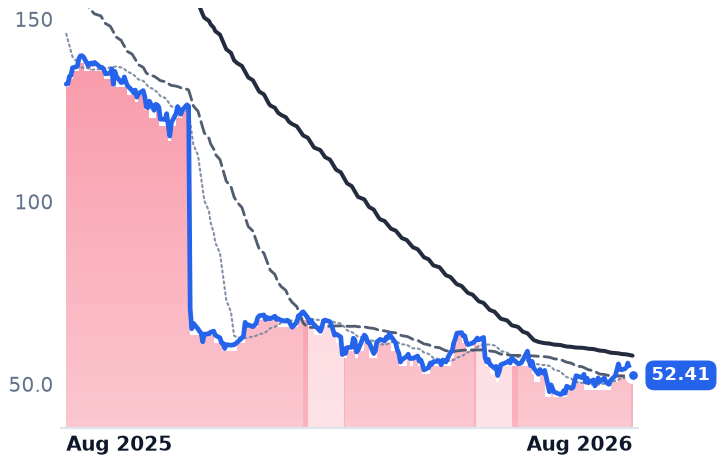
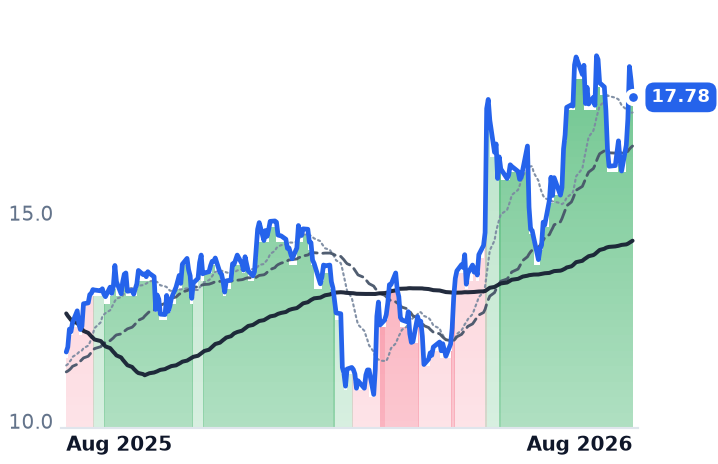
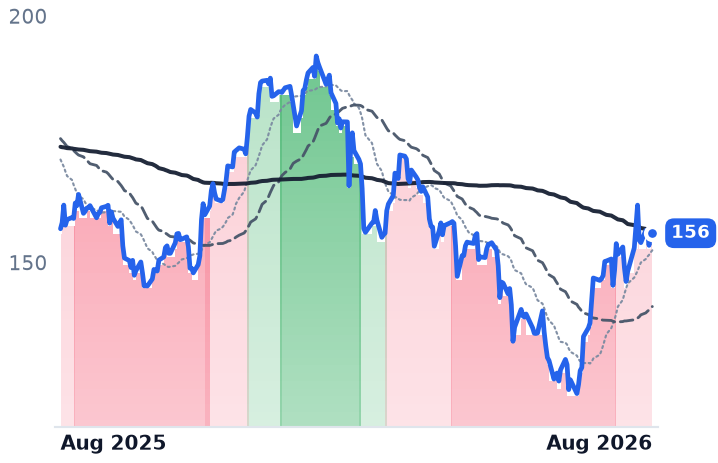
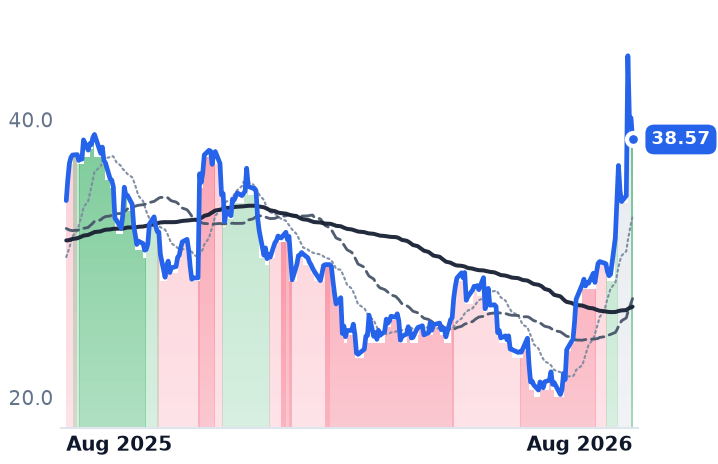
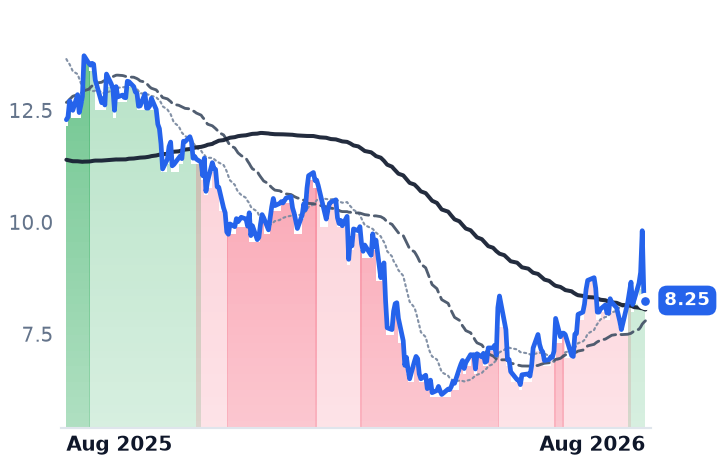
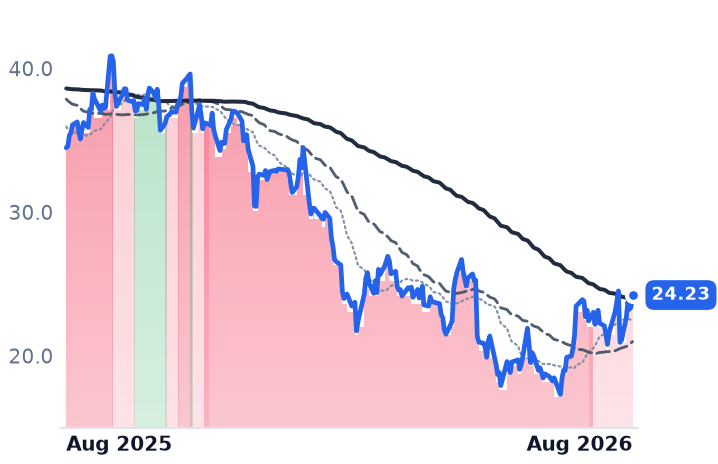
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BR | $21.5B | 20.9x | 18.0x | 2.8x | 2.7x | 9.0x | 8.7x | 13.5x | 6.3% |
FIS | $14.8B | 4.3x | 4.6x | 1.1x | 1.1x | 3.2x | 3.0x | 7.4x | 16.2% |
FISV | $33.4B | n/m | 8.6x | 1.6x | 1.7x | 3.5x | 3.7x | 94.3x | 9.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLYW | $2.2B | 65.8x | 43.1x | 3.0x | 2.8x | 5.3x | 5.0x | 24.5x | 7.1% |
JKHY | $12.1B | 23.8x | 23.5x | 4.7x | 4.5x | 10.7x | 10.3x | 13.8x | 5.9% |
PAY | $4.8B | 57.6x | 42.9x | 3.6x | 3.3x | 14.3x | 13.4x | 31.2x | 3.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VYX | $1.3B | 13.4x | 10.6x | 0.6x | 0.6x | 2.1x | 2.3x | 9.6x | -10.2% |
WAY | $4.6B | 33.7x | 14.6x | 3.9x | 3.6x | 5.6x | 5.2x | 14.1x | 5.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BR | Revenue | +8.0% | +5.8% | +4.8% |
| EPS | +12.5% | +10.6% | +9.4% | |
FIS | Revenue | +28.8% | +4.3% | +3.5% |
| EPS | +7.4% | +7.2% | +10.1% | |
FISV | Revenue | −1.4% | +3.3% | +3.5% |
| EPS | −15.0% | +9.2% | +13.1% | |
FLYW | Revenue | +26.7% | +15.3% | +15.4% |
| EPS | +291.8% | +60.0% | +38.5% | |
JKHY | Revenue | +7.0% | +6.4% | +7.0% |
| EPS | +12.6% | +7.8% | +9.6% | |
PAY | Revenue | +22.9% | +17.5% | +18.0% |
| EPS | +37.5% | +19.0% | +29.1% | |
VYX | Revenue | −17.2% | −1.3% | +1.4% |
| EPS | +4.3% | +12.0% | +0.4% | |
WAY | Revenue | +17.9% | +10.7% | +11.8% |
| EPS | +14.0% | +12.6% | +15.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Fiserv's new chief executive used the company's 6 August results to reset expectations rather than defend them. Adjusted revenue of $4.96bn fell 4% year over year, organic revenue fell 5%, earnings per share dropped 37% to $1.17, and full-year guidance came down to roughly flat organic revenue and $7.20-$7.40 of adjusted earnings, blamed on delayed client projects, weakness in Argentina and softer hardware sales. Management called 2026 a transition year, with growth troughing now and accelerating by the fourth quarter.
That is the largest company in a group of eight that sell the plumbing of finance — card acceptance, core deposit systems for banks, bill payment, healthcare claims and shareholder communications. The group has gained about 9.5% in a month after a year in which it lost roughly 17.5%. The month is not the recovery it looks like.
The month was mostly one stock
All eight names rose over the 30 days to 7 August, but Paymentus — a cloud platform that lets utilities, insurers and municipalities bill and collect from customers — rose 37.7% alone, contributing about 4.1 of the 9.5 percentage points. Strip it out and the group is up 5.4%, much of that earned in two sector-wide sessions on 27 and 29 July, when FIS, Fiserv, Jack Henry, Waystar and NCR Voyix each gained 5-7% on the same day with no company-specific news, against a macro backdrop of a Federal Reserve that held rates rather than cutting them. Paymentus has already given back 13.5% from its 4 August peak. As of 7 August only Paymentus trades in a confirmed uptrend; six names are trendless and Broadridge remains below its longer-run average.
Where the de-rating is earned
Fiserv's Q1 operating income fell 39.9% year over year. At 6.7 times forward earnings and a 14.3% trailing free-cash-flow yield it is statistically the cheapest thing here, but the forward multiple only looks like a 73% collapse from February 2025's 26.9 times because earnings are falling too. The one encouraging disclosure: Clover gross payment volume grew 9%, or 11% excluding a gateway conversion — volume growing faster than revenue, which points to pricing and mix, not merchant loss.
NCR Voyix, which sells point-of-sale and self-checkout systems to retailers and restaurants, is the weakest: revenue down 1.8% last quarter, a trailing free-cash-flow yield of -31.3%, and full-year revenue guided down 16.9% as it sells its Japan bank-technology business. FIS, which supplies core banking and capital-markets software, grew Q2 revenue 29% and raised its full-year free-cash-flow outlook to $2.2bn — but most of that came from an acquired card-issuing business, and capital-markets growth guidance was cut to 3-3.5% on what management called self-inflicted execution misses. For these three, the business explains the tape: CONFIRMS.
Where the business and the tape disagree
Broadridge is the clearest divergence. Its 4 August results showed 8% constant-currency recurring revenue growth, 12% adjusted earnings growth, $305m of closed sales and 110% free-cash-flow conversion, with guidance for another 6-8% and 8-12% next year; it also raised the dividend 12% to $4.36 and authorised $1.5bn of buybacks. The stock is down 37.4% over twelve months and its forward multiple has halved from 27.8x to about 16x. Waystar, whose software chases insurance claims and patient bills for hospitals, raised full-year guidance on 29 July with 18% revenue growth, 43% adjusted margins and 108% net revenue retention, yet its entire 30% twelve-month decline is multiple compression — 20.8x to 14.6x forward on unchanged estimates. The caveat matters: Waystar's organic growth is 7%, 10% normalised; the rest is acquired. Jack Henry, the core-banking supplier to community banks, is quietly accelerating — revenue growth of 7.3%, 7.9% then 8.7% across three quarters, with margin guidance raised to 75-95 basis points from 20-40 — but at 21.6x forward it never de-rated much. Here the tape CONTRADICTS the fundamentals.
Where the advance is stretched
Paymentus genuinely beat — $360.7m of revenue, up 28.8%, adjusted margins at a record 41.3%, against consensus of $334.7m — but at 42.8x forward earnings and 31.1x trailing enterprise value to EBITDA it is the most expensive name here, and its own third-quarter guidance implies deceleration to 15-17%. Flywire, which handles cross-border tuition and hospital payments, is up 50.8% over the year at 37.7x forward; its 41% revenue growth came with gross margin falling to 50.7% from 53.2%.
On the structural worry — that stablecoins and automated commerce compress transaction fees — nothing in these disclosures supports it yet. Paymentus's average price per transaction rose to $1.69 from $1.59, Waystar's retention held, and Broadridge is explicitly building for tokenized markets. On the group as a bottoming trade: INCONCLUSIVE.
The setup
Where it stands — A 9.5% month, nearly half of it one stock, over eight businesses whose results range from 8% growth to a guidance cut. Would confirm — Fiserv's fourth quarter showing the promised re-acceleration, and Broadridge holding 6-8% recurring growth. Would invalidate — Consensus cutting Fiserv toward $7.30 with the stock falling further, or Clover volume growth dropping below revenue growth. Watch next — Jack Henry reports fourth-quarter results after the close on 18 August 2026. Valuation — Fiserv 9.2x trailing and 6.7x forward; Broadridge 16.7x and 15.1x versus 27.8x a year ago.