

Celestica Sold Discounted Equity to Fund Capacity While All Six Assemblers Beat and Raised
Prompt v1.2
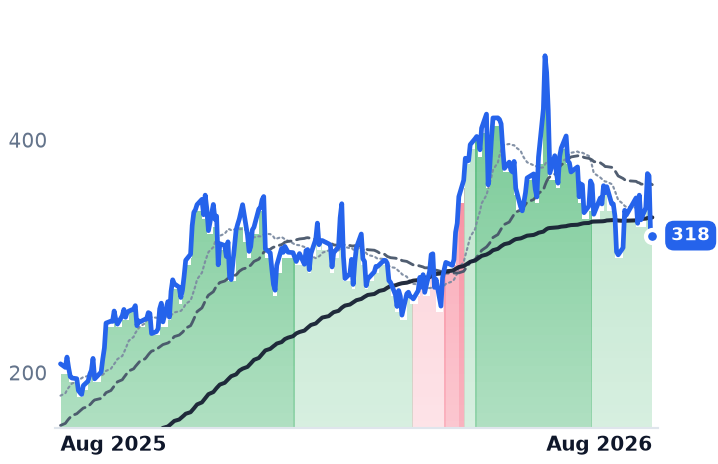
Celestica, the Toronto company that assembles switches and custom server racks for cloud giants, told investors on 5 August it would sell $3 billion of new shares — priced at $310 against a $362.76 close, roughly 8.3% dilution — to pay for factory capacity. The stock fell 14.8% the next day.
The businesses are not the problem. Between 27 and 30 July all six large contract manufacturers beat and raised: Celestica lifted full-year revenue to $20.5bn (+65%), Flex to $33.7–35.2bn, Sanmina to about $14.1bn on roughly 100% earnings growth. Five of six expanded operating margins. Forward multiples have compressed since spring — Celestica from about 40x to 27.9x, Flex to 25.8x — so the last leg was earnings, not repricing. Plexus is the exception at 31.5x forward on 19.5% growth.
What changed is who funds the buildout: capital spending, not demand, is now the variable.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
CLS | Celestica | Contract Manufacturing | 🟢 Cont. Bull | −10.4% | +53.1% |
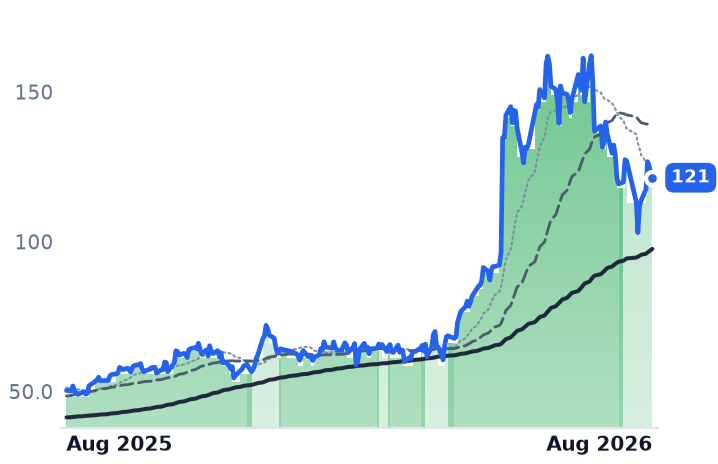
FLEX | Flex | Contract Manufacturing | 🟢 Cont. Bull | −13.3% | +141.1% |
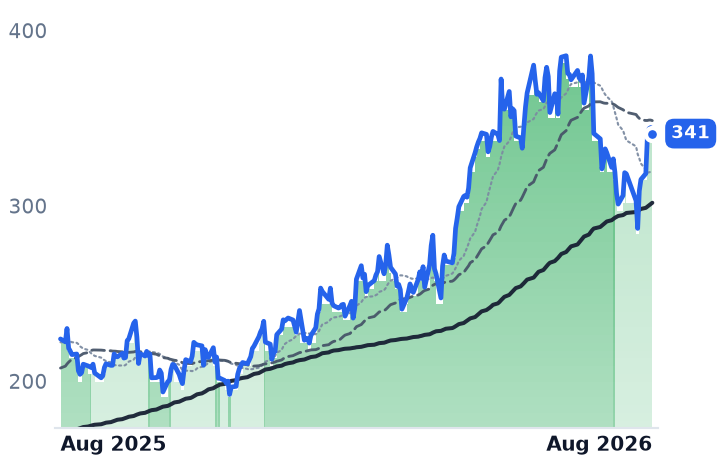
JBL | Jabil | Contract Manufacturing | 🟢 Cont. Bull | +2.6% | +52.3% |
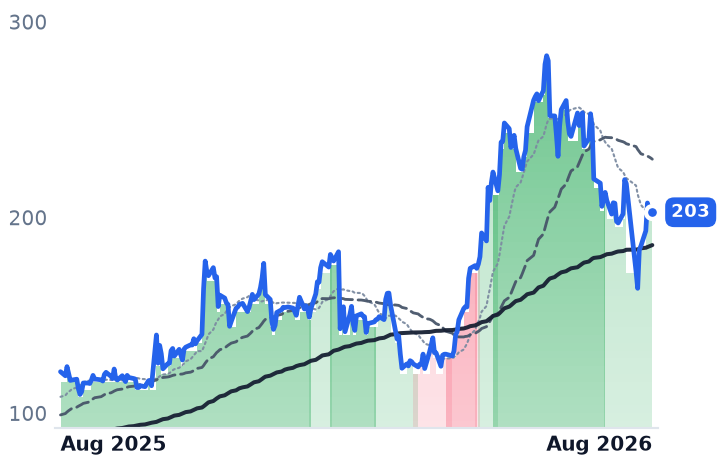
SANM | Sanmina | Contract Manufacturing | 🟢 Cont. Bull | −4.8% | +67.2% |
PLXS | Plexus | Other | 🟢 Cont. Bull | −0.1% | +108.6% |
BHE | Benchmark Electronics | Contract Manufacturing | 🟢 Cont. Bull | −3.4% | +116.9% |
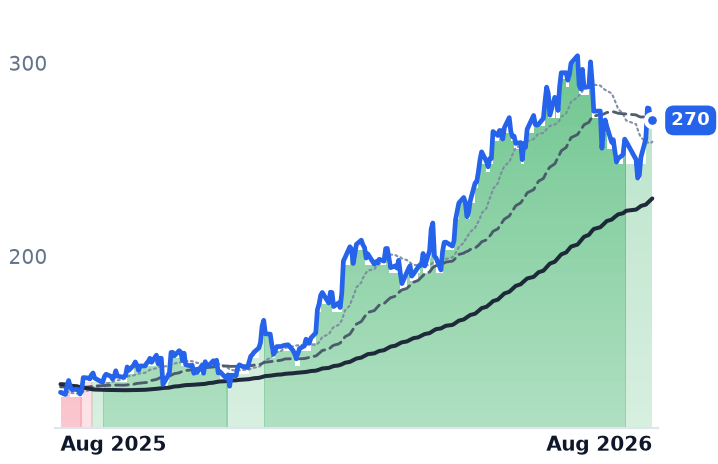
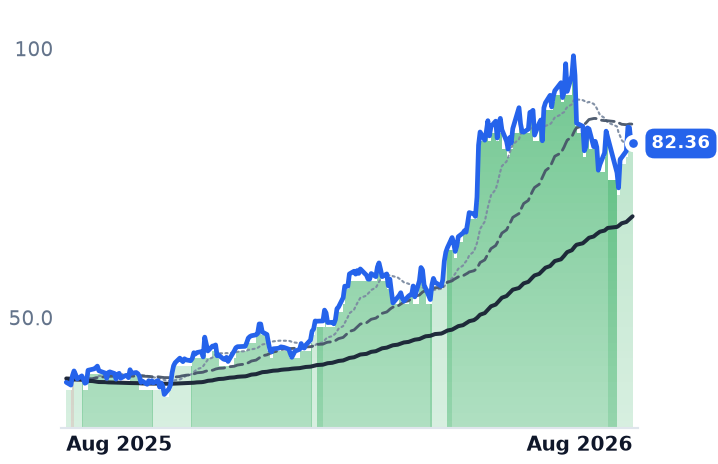
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CLS | $28.1B | — | 19.3x | — | 1.3x | — | — | 14.6x | 1.9% |
FLEX | $28.9B | 28.2x | 15.6x | 0.9x | 0.8x | 9.7x | 8.5x | 14.8x | 3.6% |
JBL | $26.0B | — | 14.3x | — | 0.6x | — | — | 12.5x | 5.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SANM | $8.0B | 21.4x | 10.6x | 0.6x | 0.5x | 5.8x | 5.0x | 10.1x | 6.7% |
PLXS | $5.5B | 27.1x | 19.1x | 1.1x | 0.9x | 10.9x | 9.2x | 17.1x | -0.5% |
BHE | $2.3B | 40.6x | 20.8x | 0.8x | 0.7x | 7.4x | 7.1x | 14.9x | 5.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CLS | Revenue | +70.3% | +90.0% | +41.7% |
| EPS | +93.2% | +91.5% | +44.4% | |
FLEX | Revenue | +6.8% | +29.5% | +30.6% |
| EPS | +24.2% | +54.8% | +54.1% | |
JBL | Revenue | +20.3% | +27.7% | +15.5% |
| EPS | +36.0% | +38.5% | +24.7% | |
SANM | Revenue | +74.9% | +17.5% | +16.8% |
| EPS | +103.5% | +16.2% | +15.4% | |
PLXS | Revenue | +21.6% | +19.8% | +9.0% |
| EPS | +21.0% | +23.8% | +14.4% | |
BHE | Revenue | +16.2% | +8.0% | +5.0% |
| EPS | +30.6% | +13.5% | +10.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Contract manufacturers have historically been the least capital-hungry link in the electronics chain: they buy components, assemble to a customer's design at low-single-digit margins, and hand back cash. That arrangement is being renegotiated in public. Celestica, a Toronto-based builder of routers, switches, interconnects and custom server racks for hyperscale cloud operators, announced a $3 billion equity offering on 5 August to fund investments supporting what it called unprecedented multi-year demand. The 9,677,419 shares were priced at $310 against a prior close of $362.76 — about 8.3% dilution on roughly 116 million diluted shares, before a 15% underwriter option — and the stock fell 14.8% the following session, the largest single-day move in the group this year.
The raise is a symptom, not an outlier. Celestica's capital spending has gone from 1.1% of revenue a year ago to 5.6% last quarter, with $1bn budgeted this year and a $1.5bn placeholder for next. Flex cut its free-cash-flow conversion guidance to about 40% from 60% on $1.5–1.6bn of capex. Celestica, Sanmina and Benchmark have all paused or deprioritised buybacks in favour of capacity. The assembly layer is becoming an asset-heavy business while the market is asking harder questions about who finances the artificial-intelligence buildout.
The tape moved before the numbers did
All six names — not four — stepped down from their strongest uptrend classification inside 22 trading days, sequenced by AI exposure: Celestica on 30 June, Sanmina 8 July, Jabil 14 July, Flex 17 July, Plexus 21 July, Benchmark 22 July. Every one of those dates precedes the company's own results. That is a sector de-rating, and it coincides with a credit event, not a demand event: tech bonds sold off on 23 July on fears about the scale of the debt-funded AI boom, hyperscalers and Nvidia issued $225bn of bonds by midyear, up roughly 974%, with Amazon paying 18–21 basis points extra on a $25bn deal, and loan investors began demanding better terms on AI credit in the week to 1 August. Drawdowns from June highs are far deeper than the group's 2.9% monthly average suggests: Celestica −32.8%, Sanmina −28.2%, Flex −24.9%.
The businesses went the other way
Celestica's June quarter revenue rose 62.4% to $4.699bn — a fourth straight quarter of acceleration — with operating margin at 9.75% against 9.42%, and it raised full-year guidance to $20.5bn and $11.30 of earnings per share while disclosing 2027 rack programmes for OpenAI and interconnect work for AMD.
Flex, the Singapore-founded manufacturer that also makes switchgear, busway and modular power systems for data halls, grew revenue 20.6% to $7.928bn with gross margin up from 8.70% to 9.42%; its Cloud & Power Infrastructure unit grew 35% to $2.2bn at a 9.7% operating margin and is guided to 65–75% growth this year. Its supposedly soft legacy book grew 12% with margins up 130 basis points. The shares still fell about 9% on the print.
Sanmina, the San Jose maker of backplanes, enclosures and printed circuit boards now carrying the acquired ZT Systems server business, grew revenue 69.7% to $3.464bn with operating margin up 173 basis points — the best expansion in the group — as cloud and AI reached 62% of revenue. It beat on both lines but guided the current quarter about 2% below consensus on legacy programme timing.
Jabil, the Florida manufacturer serving networking, storage, healthcare and semiconductor equipment customers, is the one decelerator: revenue growth slowed to 11.8% from 23.1% and operating margin slipped six basis points, though it lifted AI-related revenue guidance to about $13.6bn, up 50%. It last reported on 17 June, so it has had no late-July reset.
The two names assumed to have no AI exposure do. Benchmark Electronics, the Arizona builder of aerospace, defence, medical and semiconductor-equipment hardware, grew its advanced computing unit 71% and guided to a record $3.0bn year. Plexus, the Wisconsin manufacturer of medical, industrial and defence electronics, disclosed roughly $0.5bn of data-centre funnel and a record $4.5bn total funnel. Both are the least damaged on the tape — and, with Jabil, are what masks the declines elsewhere.
Verdict A — does the business explain the move? CONTRADICTS. Five of six accelerated, five of six expanded operating margins, and all six raised guidance into the selloff. Demand upstream also rose: the four largest cloud buyers lifted 2026 capital spending plans to roughly $725bn, up 77% — and were sold for doing so.
Verdict B — does valuation justify it? INCONCLUSIVE, and it splits. Celestica trades at 32.7x trailing and 27.9x forward against roughly 40x forward in this Desk's May reading; Flex at 46.9x trailing but 25.8x forward, versus 59x trailing in May; Jabil 42.1x/26.8x with a 4.2% free-cash-flow yield. Multiples compressed while guidance rose, so the last leg was earnings. Sanmina is the cheapest at 16.8x forward, 17.1x enterprise-value-to-EBITDA and a 9.5% free-cash-flow yield on consensus earnings growth of 103%. Plexus is the opposite: 31.5x forward, 29.0x EV/EBITDA, a 0.9% cash yield, 19.5% expected growth and the only contracting reported margins in the group. Benchmark sits at 27.8x forward with growth slowing to 13% next year.
The unresolved question is not orders. It is that Celestica's top three customers are about 65% of revenue, up from 51%, and it just funded their capacity with discounted equity.
The setup
Where it stands — Six assemblers beat and raised into a July de-rating; Celestica then diluted holders 8.3% to fund capacity.
Would confirm — Flex's Cloud & Power segment printing 45–55% growth next quarter and Celestica holding $20.5bn full-year revenue.
Would invalidate — Any of the six cutting AI-segment guidance, or a second equity raise in the group at a discount.
Watch next — Jabil's fiscal fourth-quarter results in late September, the first fresh guidance since 17 June.
Valuation — Group forward earnings multiples run 16.8x (Sanmina) to 31.5x (Plexus), against roughly 28–59x trailing readings in May.