

Data-Center REITs' Flat Year Hides a Landlord/Non-Landlord Split
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
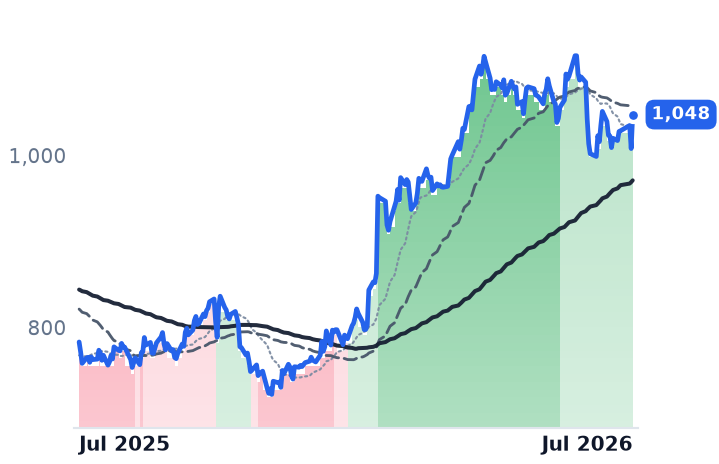
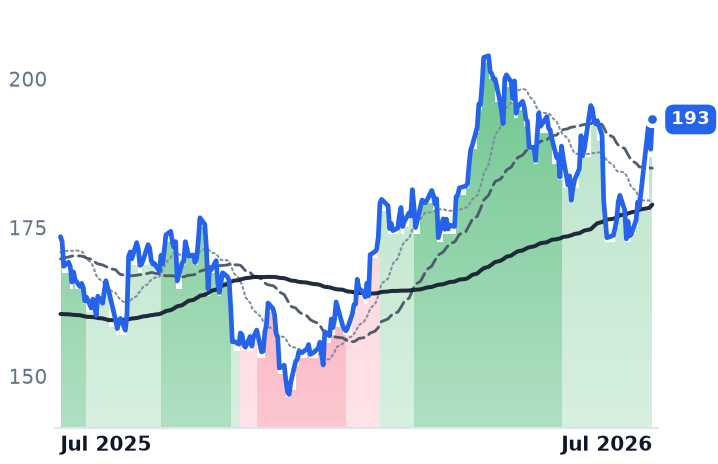
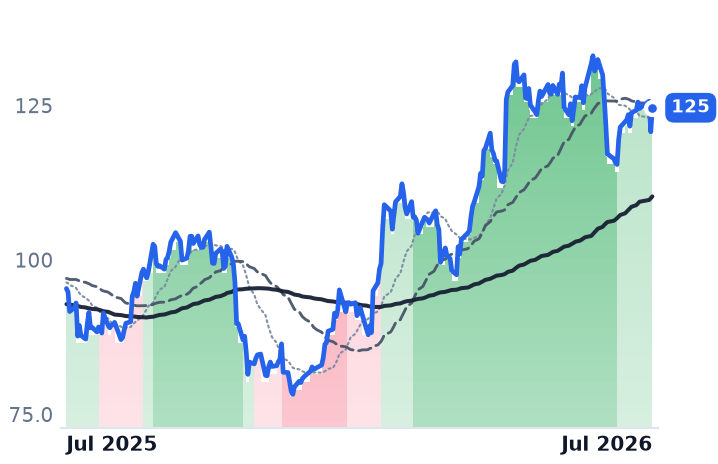
The AI2 Data Center REITs bucket looks stalled at roughly flat over the past year, but that average is a mix artifact: EQIX (+26.5%), IRM (+23.3%) and DLR (+6.1%) rerated on record AI-driven leasing while towers, China-listed operators and a newly diluted NextDC dragged the cohort average down for reasons largely unrelated to data-center demand.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
EQIX | Equinix | Data Center & Colocation | 🌱 Emerging Bull | +0.5% | +33.8% |
DLR | Digital Realty Trust | Data Center & Colocation | 🟢 Cont. Bull | +7.6% | +11.4% |
IRM | Iron Mountain Incorporated | Records & Information Management | 🟢 Cont. Bull | −1.3% | +30.7% |
GDS | GDS | Data Center & Cloud Infrastructure | ⚠️ Emerging Bear | +6.5% | −9.4% |
VNET | VNET | Data Center & Cloud Infrastructure | ⚠️ Emerging Bear | −9.0% | −8.7% |
AMT | American Tower | Wireless & Fiber Infrastructure | 🔴 Cont. Bear | +6.7% | −14.0% |
CCI | Crown Castle | Wireless & Fiber Infrastructure | 🔴 Cont. Bear | +1.0% | −25.9% |
NXT.AX | NEXTDC | Information Technology Services | 🌱 Emerging Bull | −12.3% | −10.5% |
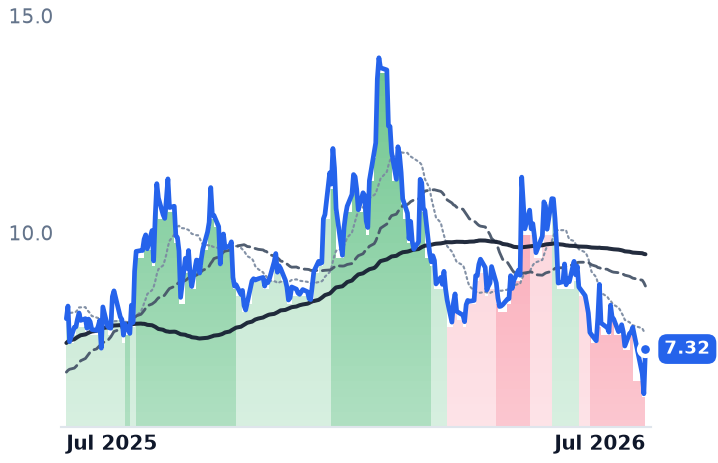
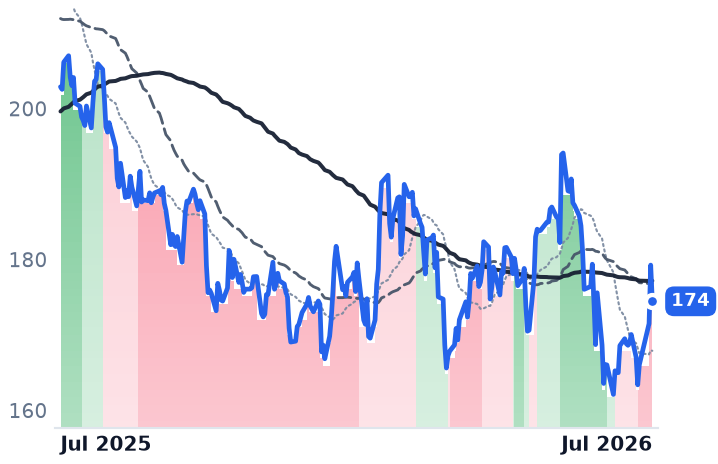
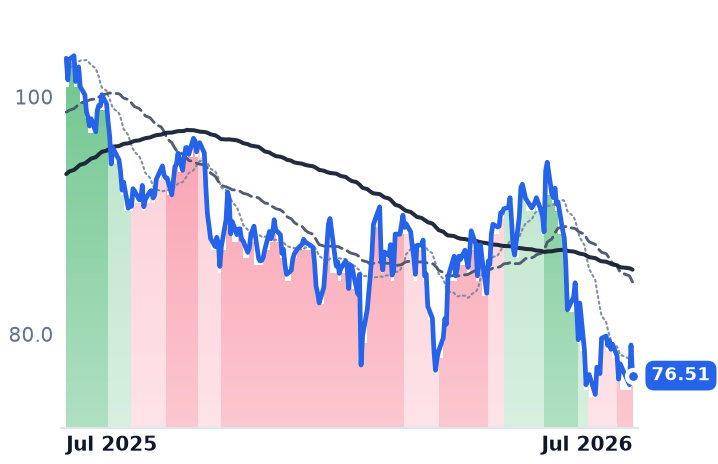
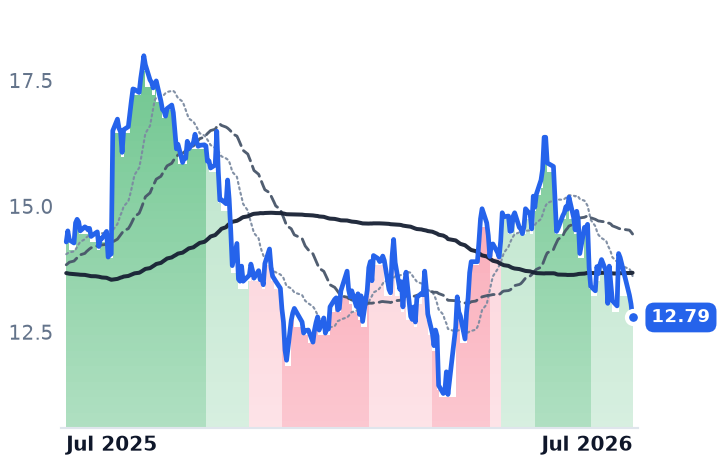
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EQIX | $108.3B | 70.4x | 63.8x | 11.0x | 10.6x | 21.4x | 20.4x | 29.1x | 1.3% |
DLR | $73.2B | 91.2x | 75.6x | 10.7x | 10.4x | 77.7x | 75.7x | 26.3x | 1.9% |
IRM | $36.0B | 86.5x | 50.4x | 4.8x | 4.5x | 8.8x | 8.3x | 15.8x | -1.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GDS | $6.6B | 12.8x | — | 3.8x | — | 15.7x | — | 14.4x | -1.7% |
VNET | $1.8B | n/m | — | 1.2x | — | 5.6x | — | 9.4x | -47.8% |
AMT | $80.4B | 23.7x | 25.1x | 7.3x | 7.3x | 10.0x | 10.0x | 17.6x | 4.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCI | $33.0B | 30.6x | 38.2x | 7.9x | 8.2x | 12.6x | 12.9x | 20.4x | 7.3% |
NXT.AX | $10.2B | n/m | — | 22.6x | 14.0x | 730.6x | 453.6x | 57.5x | -16.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EQIX | Revenue | +11.0% | +10.7% | +11.2% |
| EPS | +16.6% | +9.5% | +9.5% | |
DLR | Revenue | +16.0% | +11.1% | +14.1% |
| EPS | −28.5% | −3.7% | +25.8% | |
IRM | Revenue | +16.2% | +8.8% | +7.7% |
| EPS | +20.1% | +9.3% | +16.4% | |
GDS | Revenue | +11.2% | +11.0% | +18.0% |
| EPS | −13.3% | −75.5% | +48.9% | |
VNET | Revenue | +20.1% | +21.0% | +18.6% |
| EPS | −37.8% | −261.0% | +74.7% | |
AMT | Revenue | +4.0% | +3.3% | +5.9% |
| EPS | +34.5% | +1.4% | +10.5% | |
CCI | Revenue | −5.0% | +1.3% | +2.3% |
| EPS | +112.8% | +44.5% | +5.5% | |
NXT.AX | Revenue | +13.5% | +49.6% | +51.1% |
| EPS | +111.5% | +95.8% | +22.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The average is misleading
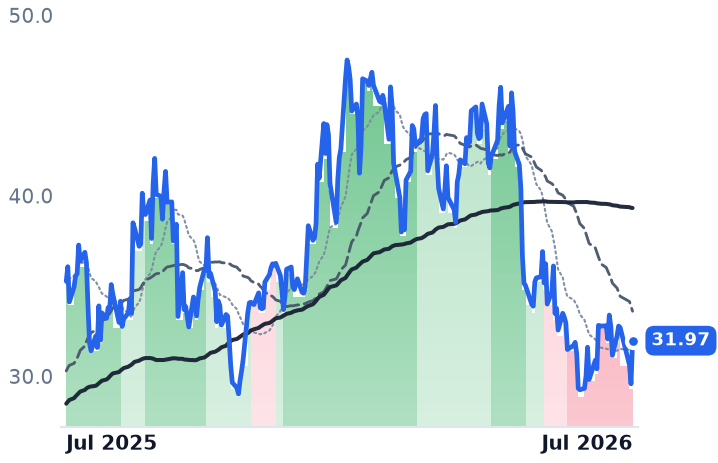
Across the eight names in the bucket, one-year price returns range from EQIX's +26.5% to CCI's -26.1% — a roughly 50-point spread hiding behind a near-flat cohort average. Trend bands as of July 29-30 confirm the split is structural, not noise: EQIX, DLR and IRM sit in mildly bullish, while AMT, CCI, GDS and VNET are in strongly bearish, and NXT.AX just flipped from mildly bullish to mildly bearish.
The landlords are working
The three best performers are also the names with the clearest AI-leasing proof points. Equinix's Q2 2026 call disclosed annualized gross bookings of $424M, up 23% and the highest-ever Q2 total, with the CEO noting the vast majority of its largest deals were AI-workload driven. Digital Realty posted record colocation/interconnection bookings of $108M, 25%+ cash re-leasing spreads and a record $1.9B backlog, plus two post-quarter hyperscale leases worth $410M in annualized rent — and about 20% of its sub-megawatt deployments are now AI-related, broadening demand beyond hyperscalers. Iron Mountain, the legacy records-storage name, has quietly become an AI-landlord story too: record data-center leasing in 2026, 21.6% revenue growth and a raised annual forecast, backed by 1.4GW of developable capacity with 400MW energizing over the next 24 months.
The draggers aren't demand stories
AMT and CCI are towers, not data-center landlords, and their weakness looks like rate/duration beta rather than an AI signal — even as American Tower's CoreSite data-center segment grew 13.4% and drove a guidance raise, the stock has traded on rate-sensitive REIT selling separate from that data-center optimism. Crown Castle's decline traces to its $8.4B fiber-asset sale, a structural non-AI event. GDS and VNET carry a China geopolitical discount rather than a demand problem — both jumped 7-9% on reports of a roughly $295B five-year Chinese data-center investment plan, and Goldman Sachs has named both among its top China data-center picks. NextDC's fresh mildly bullish→mildly bearish flip traces to a large dilutive capital raise — an A$1.5B entitlement offer, A$1.7B hybrids and A$750M notes — even as its contracted utilization hit a record 740MW and forward order book rose to 565MW on a new 250MW hyperscale win, suggesting the crack is a funding/dilution event rather than a demand miss.
The risk that unites them
The entire group remains structurally rate-sensitive: heavy debt-financed construction means a return to 5%+ long-term rates could again pressure valuations broadly, as it did during the 2023-2024 yield spike.