

Analog/Auto Semis Cool in Unison, Not Unraveling, After a Blowout Year
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
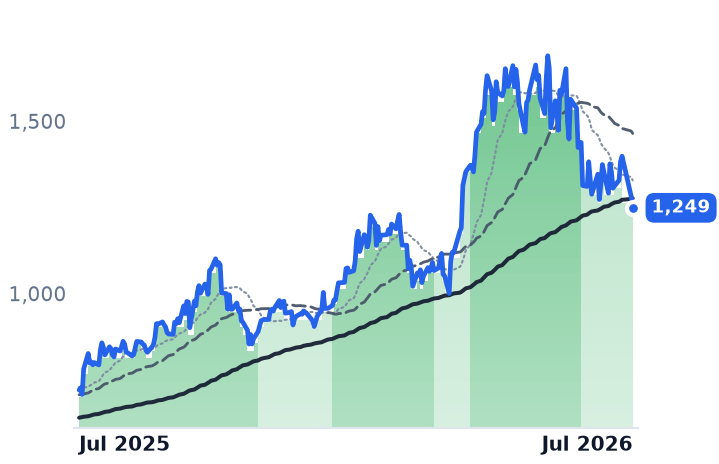
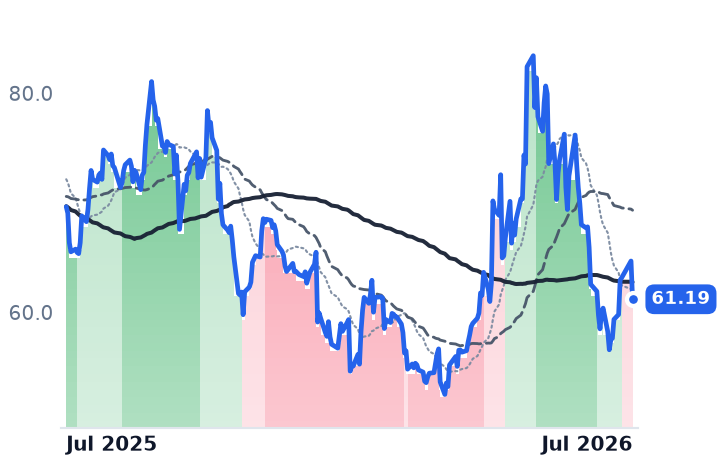
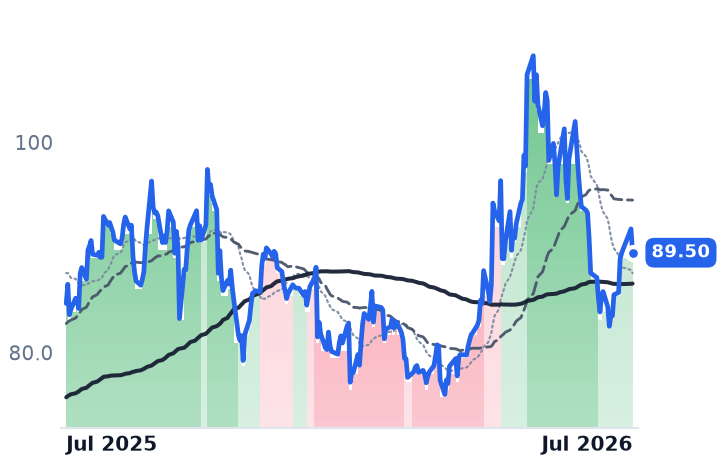
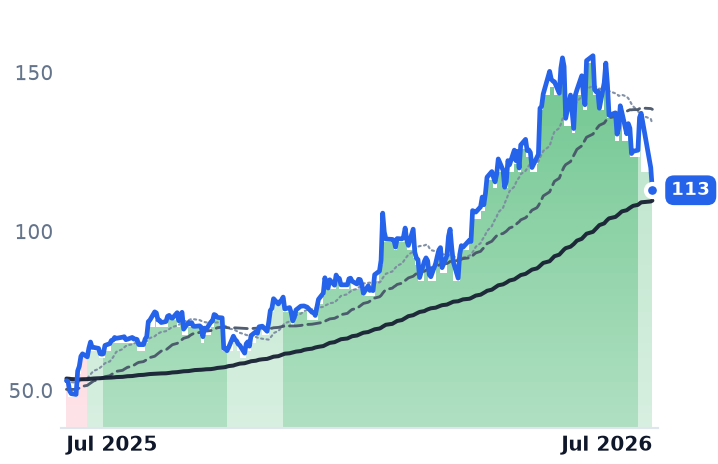
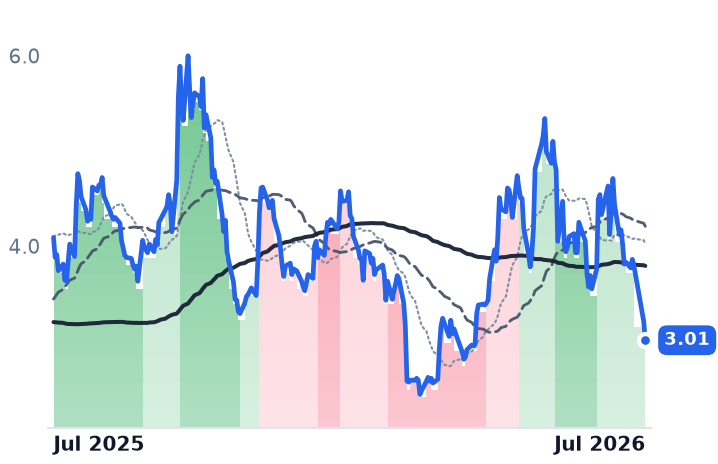
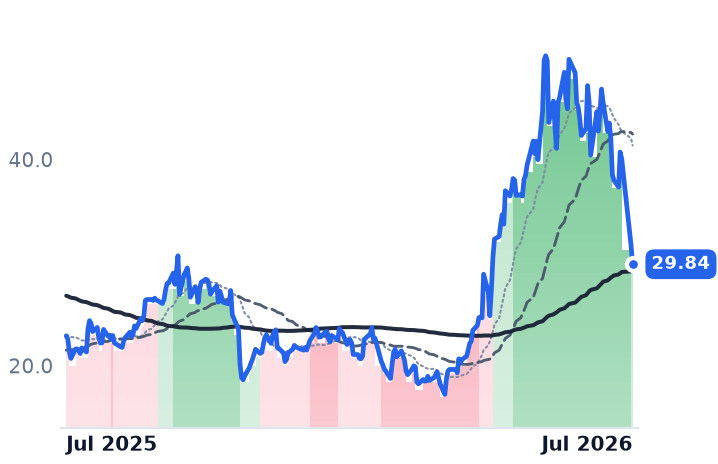
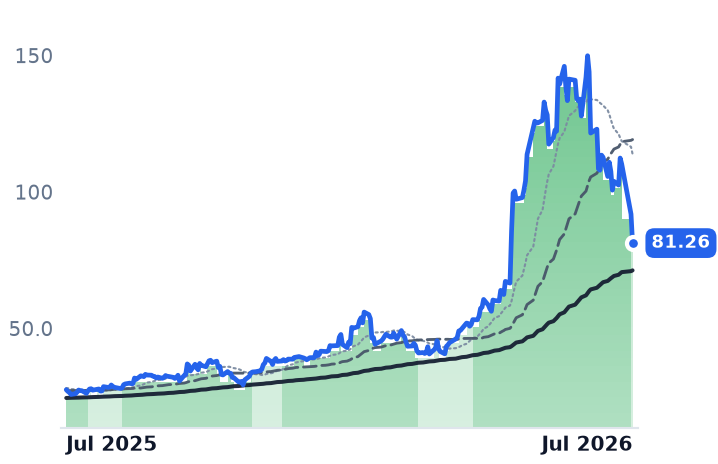
The Fabless/Analog, Auto & Specialty bucket's July slide is a synchronized step-down from strongly bullish to mildly bullish across nearly the whole cohort rather than a breakdown — bookings, book-to-bill and pricing power at the analog core still point to a recovery building, not fading.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | −9.8% | +54.8% |
NXPI | NXP Semiconductors | Analog & Mixed-Signal | 🟢 Cont. Bull | −13.4% | +7.8% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | −19.9% | +3.2% |
ON | ON Semiconductor | Analog & Mixed-Signal | 🟢 Cont. Bull | −11.0% | +35.1% |
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | 🟢 Cont. Bull | −4.7% | +73.3% |
SWKS | Skyworks Solutions | Analog & Mixed-Signal | 🌱 Emerging Bull | −9.6% | −12.1% |
QRVO | Qorvo | Analog & Mixed-Signal | 🌱 Emerging Bull | −4.3% | +5.7% |
LSCC | Lattice Semiconductor | Specialty Semiconductors | 🟢 Cont. Bull | −23.0% | +112.9% |
INDI | indie Semiconductor | RF & Wireless | 🟢 Cont. Bull | −19.9% | −26.4% |
| Compared against · context, not the story | |||||
CEVA | CEVA | Specialty Semiconductors | 🌱 Emerging Bull | −30.7% | +30.3% |
VPG | Vishay Precision | Precision Motion & Sensors | 🟢 Cont. Bull | −42.8% | +195.0% |
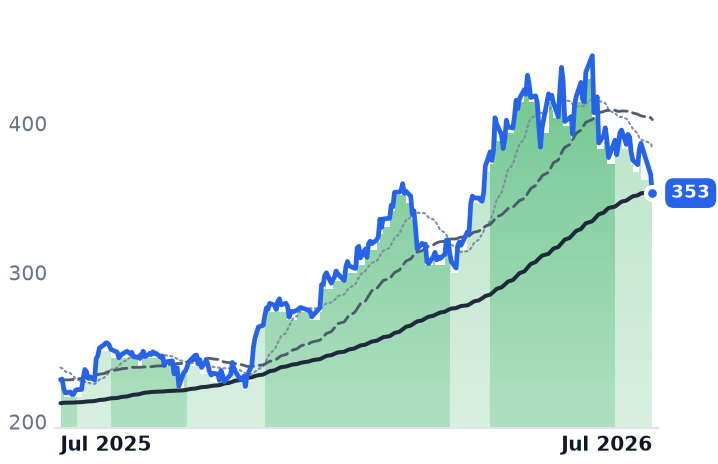
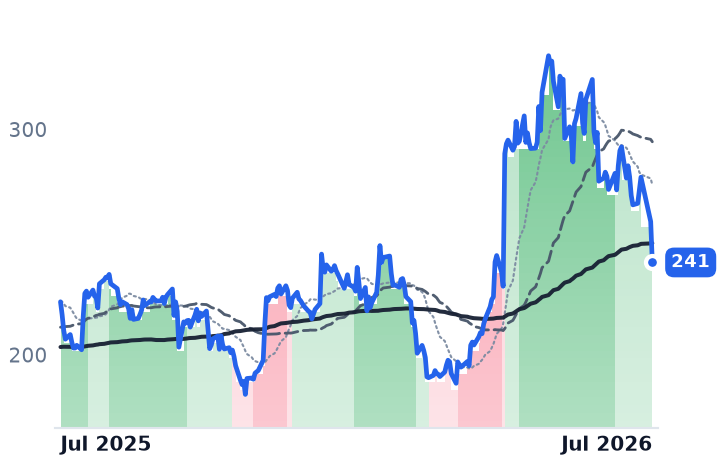
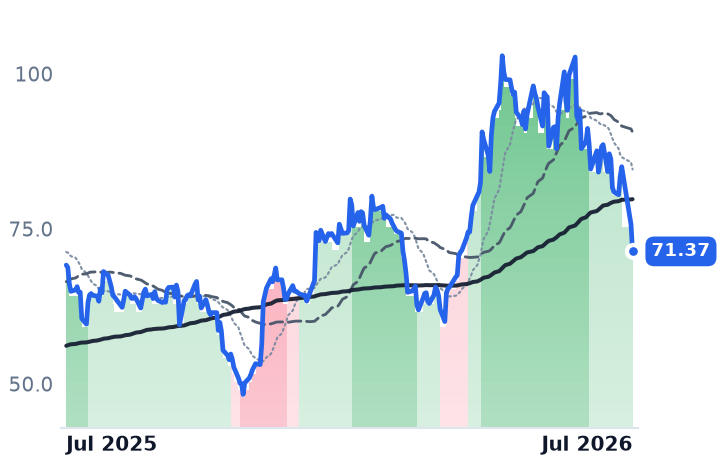
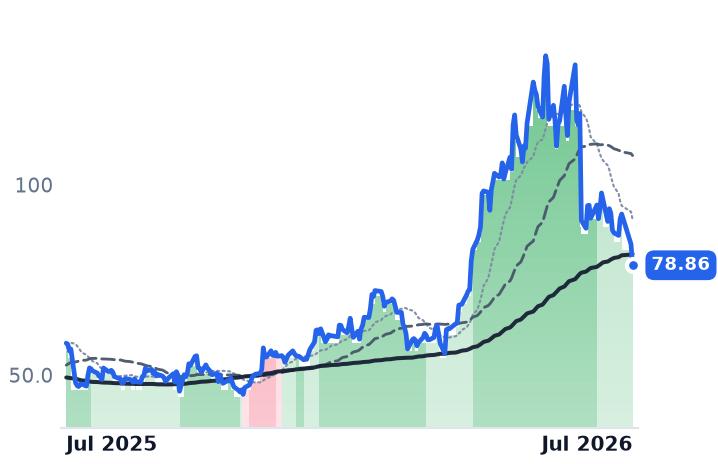
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADI | $183.5B | 55.7x | 30.4x | 14.4x | 12.4x | 22.3x | 19.3x | 30.5x | 2.5% |
NXPI | $57.6B | 19.4x | 15.1x | 4.4x | 4.0x | 7.8x | 7.2x | 13.4x | 5.1% |
MCHP | $42.5B | 108.3x | 24.5x | 8.3x | 6.8x | 13.8x | 11.3x | 28.2x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ON | $32.5B | 52.8x | 26.1x | 5.2x | 5.0x | 14.0x | 13.2x | 26.4x | 5.5% |
MPWR | $69.6B | 86.3x | 52.1x | 21.3x | 16.9x | 38.5x | 30.6x | 67.8x | 0.8% |
SWKS | $10.2B | 34.9x | 13.4x | 2.5x | 2.6x | 6.2x | 6.3x | 12.7x | 1.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
QRVO | $8.5B | 22.1x | 12.8x | 2.3x | 2.4x | 4.8x | 5.0x | 11.2x | 7.7% |
LSCC | $18.2B | 501.6x | 62.3x | 27.9x | 19.8x | 41.3x | 29.2x | 208.2x | 1.2% |
INDI | $995.2M | n/m | — | 4.3x | 3.7x | 20.0x | 17.4x | n/m | -8.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEVA | $927.2M | n/m | 62.7x | 8.0x | 7.6x | 9.2x | 8.6x | n/m | -0.1% |
VPG | $1.3B | 219.1x | 96.7x | 4.1x | 3.7x | 10.4x | 9.5x | 45.1x | -0.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ADI | Revenue | +34.6% | +16.0% | +9.7% |
| EPS | +59.8% | +21.6% | +15.0% | |
NXPI | Revenue | +16.6% | +11.5% | +8.2% |
| EPS | +28.0% | +20.6% | +15.7% | |
MCHP | Revenue | +6.2% | +33.3% | +16.1% |
| EPS | +20.7% | +103.7% | +31.1% | |
ON | Revenue | +9.2% | +12.9% | +13.5% |
| EPS | +37.1% | +41.7% | +31.7% | |
MPWR | Revenue | +47.9% | +26.0% | +13.5% |
| EPS | +53.3% | +28.2% | +13.2% | |
SWKS | Revenue | −2.0% | +1.8% | +7.0% |
| EPS | −11.0% | −2.2% | +17.8% | |
QRVO | Revenue | −0.8% | −4.7% | +4.5% |
| EPS | +21.6% | +14.8% | +6.6% | |
LSCC | Revenue | +2.3% | +76.6% | +45.0% |
| EPS | +11.9% | +102.7% | +50.7% | |
INDI | Revenue | +22.8% | +35.4% | +44.7% |
| EPS | −44.1% | −131.9% | +471.0% | |
CEVA | Revenue | +12.3% | +13.7% | +11.8% |
| EPS | +27.5% | +54.9% | +23.5% | |
VPG | Revenue | +14.8% | +6.1% | +6.6% |
| EPS | +47.4% | +79.5% | +69.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's happening
Across the 11-name analog/auto/specialty bucket (ADI, NXPI, MCHP, ON, MPWR, SWKS, QRVO, LSCC, INDI, CEVA, VPG), the past 30 days have produced red across the board — from roughly -2% (QRVO) to -35% (VPG). But the trend-band data tells a more specific story than a rout: nine of eleven names simply stepped down one notch, from strongly bullish to mildly bullish, in a tight late-June-to-late-July window (MPWR on June 25, MCHP July 1, ADI/NXPI/ON July 6, QRVO July 7, LSCC July 20, VPG/CEVA July 28). Only SWKS actually crossed a full band boundary into mildly bearish, on July 22 — and that coincides with its pending acquisition of Qorvo, a corporate-action overhang rather than a demand signal, especially since Qorvo has suspended standalone guidance calls pending the merger's close.
The one-year gain is broader than it looks
The hypothesis that the year's +35% run rests on one or two AI-levered names doesn't hold up: over the trailing year, VPG (+233%), LSCC (+126%), MPWR (+77%), ADI (+59%) and ON (+45%) all posted big gains, with NXPI, QRVO and MCHP up more modestly and only SWKS (-10%) and INDI (-22%) negative. The analog core — ADI, NXPI, ON, MCHP — has participated, not just ridden along.
Fundamentals still support mid-cycle, not late-cycle
The underlying prints back this up. Analog Devices posted Q2 FY26 revenue up roughly 37% year-over-year with record bookings and channel inventory back to a normal 6-7 week range across all sub-markets. NXP's Q2 revenue rose 19% year-over-year with automotive up 12-17% and a raised 2024-27 auto revenue CAGR target of 8-12%. Monolithic Power guided Q2 revenue up roughly 35% year-over-year, with AI-server power revenue up nearly 98%.
Pricing dynamics also cut against the "Chinese substitution eroding margins" fear embedded in the hypothesis: Texas Instruments has pushed through three rounds of price hikes in six months, up 15-85% on some parts, with ADI and Infineon following suit — a sign of pricing power into strong demand, not erosion. The same reporting notes China's analog self-sufficiency remains below 10% even at 40-45% of global consumption, meaning domestic substitution is a real but early-stage risk concentrated in new design wins rather than existing programs.
The specialty-tail names have idiosyncratic stories: CEVA's July slide tracked a COO transition and analyst downgrades, even as TD Cowen raised its price target following a June AI licensing deal, while Skyworks and Qorvo's own results — a Q2 beat for SWKS and expanding margins for Qorvo — read as an improving RF cycle obscured by merger mechanics rather than deteriorating demand.
Why it matters
This reads as a broad, sector-wide profit-taking pause after an outsized run rather than the front edge of a rollover: fundamentals (bookings, inventory, pricing, auto content) are still confirming the recovery thesis across the analog core, even as smaller/specialty names took the sharpest near-term hits.