

Frac-Pumping Cohort Rolls Over: Four of Five Names Break Bull Bands in July
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
LBRT, RES, ACDC and PUMP have all flipped from bull to bear trend bands within a tight three-week window in July, driven by real pricing and utilization deterioration in pressure pumping — but PTEN and water-infrastructure peer WTTR have not broken down, showing the rollover is completions-pricing-specific rather than a gas-complex-wide reset.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LBRT | Liberty Energy | Well Services & Stimulation | 🟢 Cont. Bull | −34.9% | +35.4% |
PTEN | Patterson-UTI Energy | Onshore Land Drilling | 🟢 Cont. Bull | −2.3% | +52.9% |
PUMP | ProPetro | Well Services & Stimulation | 🟢 Cont. Bull | −30.7% | +61.0% |
RES | RPC | Well Services & Stimulation | ⚠️ Emerging Bear | −11.9% | +6.5% |
ACDC | ProFrac | Well Services & Stimulation | 🌱 Emerging Bull | −37.8% | −55.8% |
| Compared against · context, not the story | |||||
WTTR | Select Water Solutions | Water Services & Energy Solutions | 🟢 Cont. Bull | −9.0% | +86.3% |
SEI | Solaris Energy Infrastructure | Proppant & Logistics | 🟢 Cont. Bull | −45.2% | +29.5% |
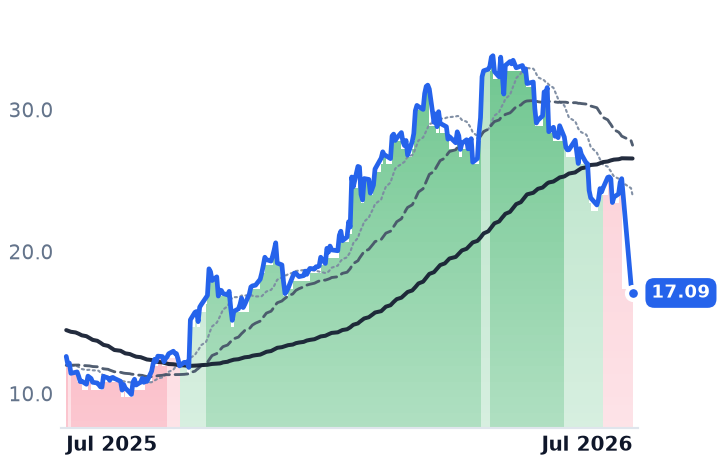
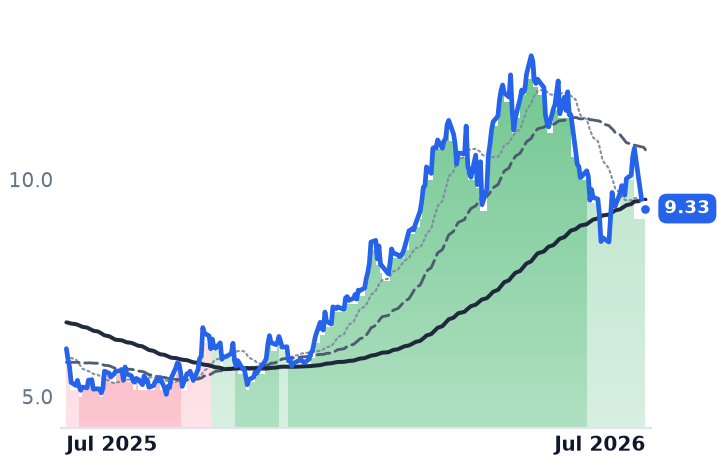
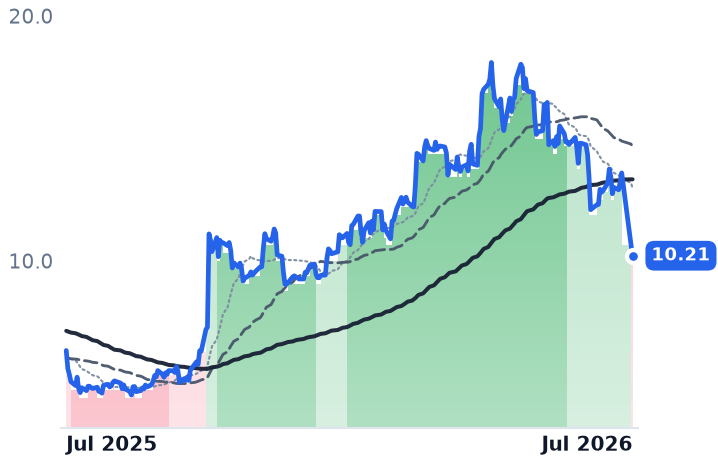
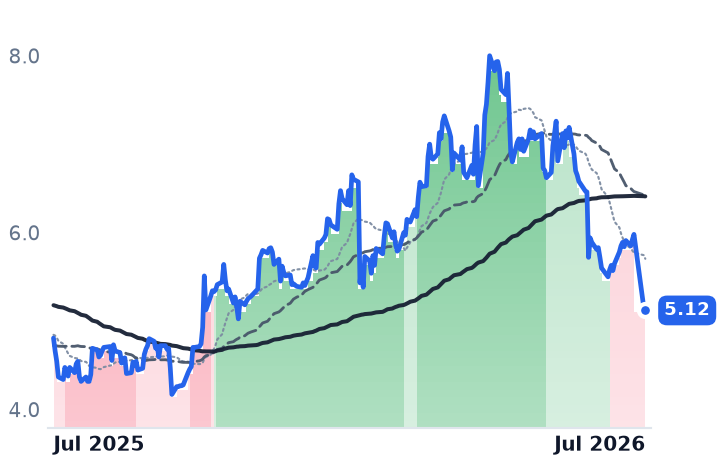
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LBRT | $5.4B | 35.5x | 490.6x | 1.3x | 1.3x | 12.4x | 11.9x | 9.2x | -3.6% |
PTEN | $4.3B | n/m | — | 0.9x | 0.9x | 6.5x | 6.4x | 6.4x | 4.1% |
PUMP | $2.1B | n/m | — | 1.8x | 1.7x | 21.9x | 21.1x | 13.7x | -0.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RES | $1.5B | 73.3x | 34.6x | 0.9x | 0.9x | 7.7x | 7.7x | 6.3x | 2.9% |
ACDC | $1.3B | n/m | — | 0.7x | 0.7x | — | — | 21.7x | 0.2% |
WTTR | $1.9B | 92.6x | 34.9x | 1.4x | 1.3x | 7.7x | 7.1x | 10.0x | -4.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SEI | $3.5B | 59.0x | 46.1x | 5.1x | 4.3x | 15.1x | 12.6x | 22.6x | -16.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LBRT | Revenue | +9.9% | +9.1% | +17.9% |
| EPS | −205.6% | +497.4% | +163.6% | |
PTEN | Revenue | −0.5% | +7.7% | +1.6% |
| EPS | −78.0% | −499.4% | +119.3% | |
PUMP | Revenue | −2.9% | +17.1% | +10.5% |
| EPS | −98.3% | −42917.5% | +227.4% | |
RES | Revenue | +6.5% | +4.8% | −2.3% |
| EPS | −30.3% | +40.0% | +42.9% | |
ACDC | Revenue | −3.0% | +8.7% | −2.1% |
| EPS | −26.1% | −42.5% | −51.3% | |
WTTR | Revenue | +8.6% | +6.6% | +5.9% |
| EPS | +118.6% | +33.5% | +70.1% | |
SEI | Revenue | +36.7% | +48.2% | +35.0% |
| EPS | +13.1% | +101.2% | +98.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's happening
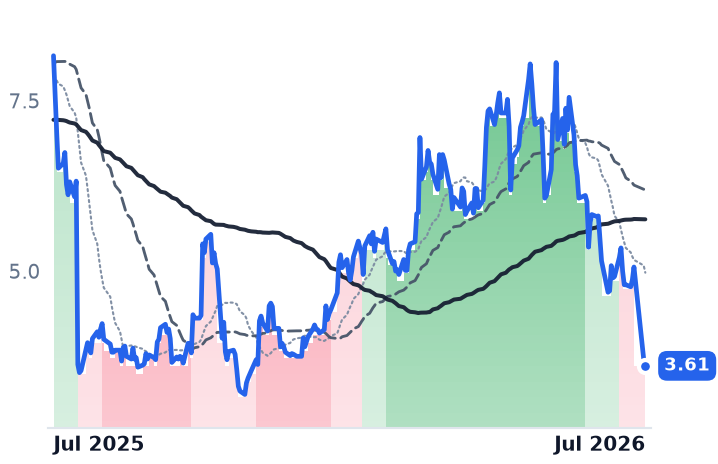
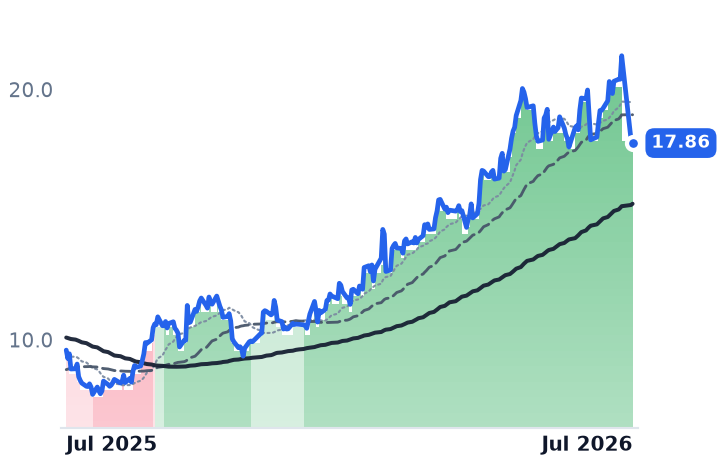
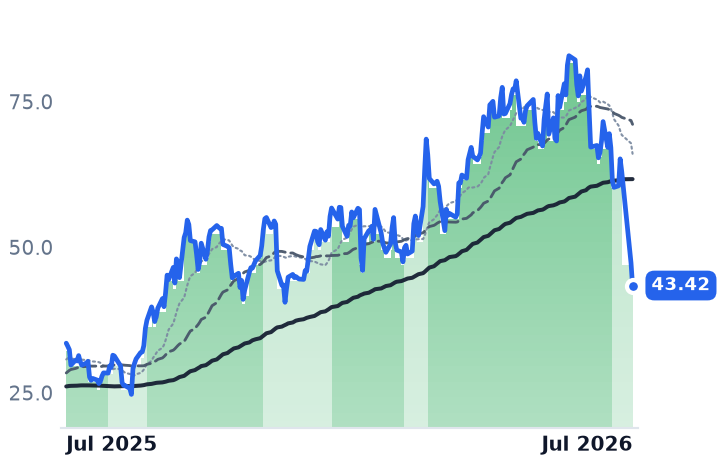
Four of the five starred names in the pressure-pumping bucket have crossed from bull into bear trend bands inside a narrow window this month: LBRT flipped on July 10, RES on July 7, ACDC on July 13, and PUMP — the name the original hypothesis flagged as the lone outlier — joined them on July 28. Only PTEN has held mildly bullish continuously since late June, with a 30-day drawdown of just -4% versus -28% to -36% for the other four. Adjacent water-infrastructure peer WTTR remains in an unbroken strongly bullish band with a much shallower -8.3% pullback, and trailing-12-month returns diverge sharply: WTTR +84%, PUMP +72.8%, PTEN +46.9%, LBRT +35.5%, RES +4.2%, and ACDC actually down -54.4% despite its mid-cycle bull run.
The fundamentals behind the crossings
This looks like more than a synchronized multi-day selloff. US frac spread crews have fallen to 196 active, down nine over two weeks, and spot Henry Hub sat at $2.80/MMBtu on July 20 even as the EIA raised its full-year 2026 average forecast to $3.67. The earnings prints back up the band breaks: RPC (RES) missed Q2 estimates with adjusted EPS down 46.7% year-over-year, explicitly citing weakness in pressure-pumping activity and pricing. ProFrac (ACDC) posted an 85.7% EPS miss against consensus, with revenue also lagging estimates by over 7%. Even Liberty Energy (LBRT), which beat on revenue and EBITDA, fell 13.7% post-earnings on margin-compression concerns, with management noting pricing gains are pacing more gradually than hoped, deferred largely to H2. ProPetro (PUMP), reporting July 29, carries a still-subscale power-generation offset — roughly 240 MW contracted against a multi-gigawatt ambition — and shares are already down about 16% over the trailing month on bearish oilfield-services sentiment.
Why PTEN and power-gen are the exceptions
Patterson-UTI's completions segment is the outlier, with stronger-than-expected Q2 pricing and high fleet utilization, with further improvement guided into Q3 alongside a rig count climbing toward 100 by year-end. Meanwhile pure-play power-generation comparable Solaris Energy Infrastructure raised its EBITDA guidance and holds 3,200 MW of capacity under long-term tech contracts, suggesting the data-center power thesis itself remains intact — it just hasn't scaled enough yet at LBRT, ACDC or PUMP to decouple earnings from frac pricing. Broader E&P capital discipline compounds the pressure: Wood Mackenzie projects overall 2026 E&P budgets falling as firms prioritize shareholder returns over drilling-and-completion growth, even as shale-gas-focused capex is set higher at select operators. Prior conviction ratings on this cohort had already flagged PUMP, ACDC and RES as fragile-earnings, high-beta names even during the uptrend, consistent with them being first to roll over while PTEN's stronger backlog kept it insulated.